

Will Hongkong Land seek to control the manager of Suntec Reit or the trust’s most prized properties?
Investing in a Reit where another group is the sponsor may be hardly optimal for the property giant
[SINGAPORE] In late October 2024, Hongkong Land unveiled a new strategy to double underlying profit before interest and tax, double dividend per share, recycle capital of up to US$10 billion and grow assets under management (AUM) to US$100 billion with active participation by third-party capital by 2035.
The group has since been executing its strategy. Among various moves, it sold its property development business in Singapore and Malaysia, MCL Land, to Sunway Group.
The property giant also established its inaugural private real estate fund – the Singapore Central Private Real Estate Fund (SCPREF). Qatar Investment Authority and APG Asset Management are founding investors, and Hongkong Land manages this fund.
Investors have rewarded Hongkong Land – its share price on the local bourse as at Tuesday (Apr 28) of US$7.89 has more than doubled from the US$3.89 on Oct 29, 2024, prior to unveiling the new strategy.
However, does Hongkong Land’s purchase of a 10.8 per cent stake in Suntec Real Estate Investment Trust (Reit) from ESR Group for S$541 million or S$1.70 per unit make sense?
Hongkong Land said on Mar 19 that the acquisition will enable it to deploy recently recycled capital into prime, income-producing commercial assets in Singapore.
The group said that the acquisition aligns with its positive outlook and conviction in the Republic’s prime commercial property market, and that the yield derived from the Suntec Reit investment will contribute to diversifying Hongkong Land’s earnings profile.
Hongkong Land bought into Suntec Reit at a 16 per cent discount to the trust’s net asset value per unit of S$2.03 as at end-2025. And it could gain from the Tang Organization working with the trust’s manager – Acrophyte Asset Management – on a comprehensive strategic review of Suntec Reit’s portfolio, with the aim to strengthen portfolio performance and enhance capital efficiency.
Acrophyte is a wholly owned subsidiary of Tang Organization, which replaced ESR as Suntec Reit’s sponsor. Gordon and Celine Tang control Tang Organization. The couple, their children and other family members are collectively Suntec Reit’s largest unitholder group, owning about 36 per cent of the trust’s units.
Investment rationale
While Hongkong Land’s entry price in Suntec Reit is below the trust’s book value, should the property giant with its big ambitions to grow as a fund manager earning management fees from managing third-party capital invest in a Reit where another group is the sponsor and owns the manager?
Suntec Reit posted encouraging results for the first quarter, with distribution per unit up 24 per cent year on year. Still, the trust traded on Tuesday at S$1.47 per unit – below Hongkong Land’s entry price.
With interest rates possibly being elevated due to higher energy prices driving rising inflation, improving Suntec Reit’s unit price might be challenging.
Importantly, the Suntec Reit investment may not really deliver on growing Hongkong Land’s exposure to Singapore’s prime commercial property market.
For financial year 2025, while Singapore assets accounted for 78 per cent of Suntec Reit’s AUM, assets in Australia and the UK accounted for 12 per cent and 10 per cent of the trust’s AUM, respectively.
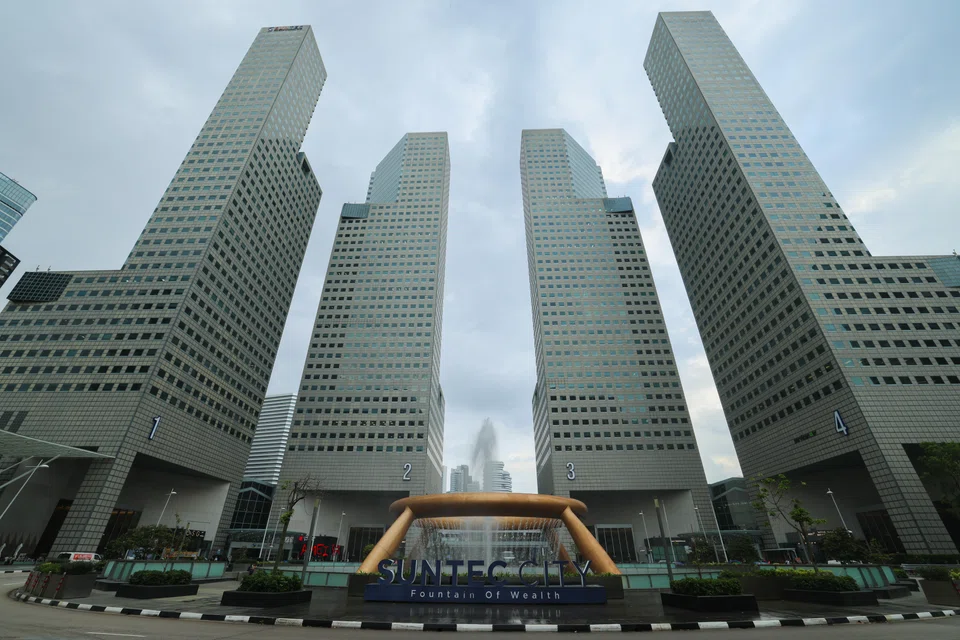
Within Suntec Reit’s Singapore portfolio, its one-third interests in top Central Business District (CBD) Grade A office properties One Raffles Quay and Marina Bay Financial Centre (MBFC) Towers 1 and 2, as well as Marina Bay Link Mall, fit well with Hongkong Land’s focus on top-tier commercial properties.
However, the trust’s ownership interests in Suntec City Office Towers, Suntec City mall and Suntec Singapore Convention and Exhibition Centre may not represent the highest-grade assets that Hongkong Land is typically associated with, in my view.
Control of manager or prized assets
Perhaps, Hongkong Land’s investment in Suntec Reit can truly pay off if it paves the way for the property giant to have an entity which it owns replace Acrophyte as the trust’s manager.
Controlling a manager of a Singapore-listed Reit will help Hongkong Land grow in managing third-party capital, boost management fees and build fund management track record in the listed-Reit space here.
The Tang family’s interest in Suntec Reit helps entrench Acrophyte’s position as the trust’s manager. Still, Hongkong Land may try persuading the Tang family, possibly with support from other investors, that there is much value in having Hongkong Land actively involved in managing the Reit.
Might Hongkong Land raise its stake in Suntec Reit to strengthen a potential bid to control the Reit’s manager?
Alternatively, perhaps Hongkong Land could try to parlay its investment in Suntec Reit into snaring control of the Reit’s interest in One Raffles Quay, MBFC Towers 1 and 2, and Marina Bay Link Mall.
For one, SCPREF should be happy to raise its interests in the above top CBD properties. Launched with AUM of S$8.2 billion at inception, office-focused SCPREF’s initial portfolio included one-third stakes in One Raffles Quay, MBFC Towers 1 and 2, and Marina Bay Link Mall.
Hongkong Land could stay in the background and hopefully reap benefits from the Tang Organization and Acrophyte crafting a new strategy for Suntec Reit and the subsequent execution on the said strategy.
For example, the trust could sell overseas assets. If Suntec Reit’s manager executes well on an effective new strategy, all unitholders, including Hongkong Land and retail investors, stand to gain.
Nonetheless, don’t rule out a reinvigorated Hongkong Land trying to snare control of Suntec Reit’s manager or the trust’s best Singapore properties in order to maximise value from its foray into Suntec Reit.
The writer is an investor in Suntec Reit
TRENDING NOW

Britain’s mansion tax shows the difficulty of targeting wealth

Once staunchly pro-China, Malaysian Chinese businesses are now distancing themselves from Beijing

The only common thing in S-E Asia is that we all eat rice: Cisco’s Asean president
Singapore data centre operator DayOne opts for US IPO at likely US$20 billion valuation

