

Win-win investment property deals exist, but lower interest rates raise risk of bad deals
While the CLI-CICT Ion Orchard agreement arguably benefits both parties, investors should be wary of Reit managers bingeing on acquisitions
SOMETIMES, win-win deals do not exist. In trading a pair of currencies, one party benefits from a particular currency strengthening while the counterparty suffers a loss.
In mega corporate and property deals, one often sees both buyer and seller gushing over the merits of the deal.
However, are win-win investment property deals the realm of fantasy? A seller may want to exit a property because he sees limited scope to add further value, grow rent or increase capital value.
Still, even if counterparties to a property deal might exaggerate the positives behind their respective actions, there are sound reasons behind why some investment property deals can be win-win deals.
Differing needs
A buyer and a seller of a particular property could have widely differing objectives, strategies, financial circumstances, skill sets and investment return requirements.
For example, a party with large exposure to a particular property asset class or geographic market might seek to reduce exposure to the segment because it wants greater diversification.
An owner of an investment property who is happy with owning the said property might look to divest because he needs funds urgently to pursue a new opportunity.
Investors may hold differing views on the value of freehold and leasehold properties here. A private fund or listed real estate investment trust (Reit) might find properties with shorter remaining land leases that offer relatively higher yields attractive, whereas a wealthy family keen on wealth preservation could prefer freehold assets despite much skinnier yields.
Also, an ageing property that requires substantial capital expenditure to redevelop might be a burden to an owner who cannot fund the expenditure or lacks development capabilities, but an opportunity to a buyer with access to funding and development capabilities.
Time horizons can vary too, among various players. Perhaps a party with a long-term horizon will view a location that takes 20 years to mature very differently from one whose time horizon is several years. While some owners may patiently hang on to strata-held retail units despite falling rents because of the hope of an en bloc sale, others may lack the patience to do so.
Ion Orchard
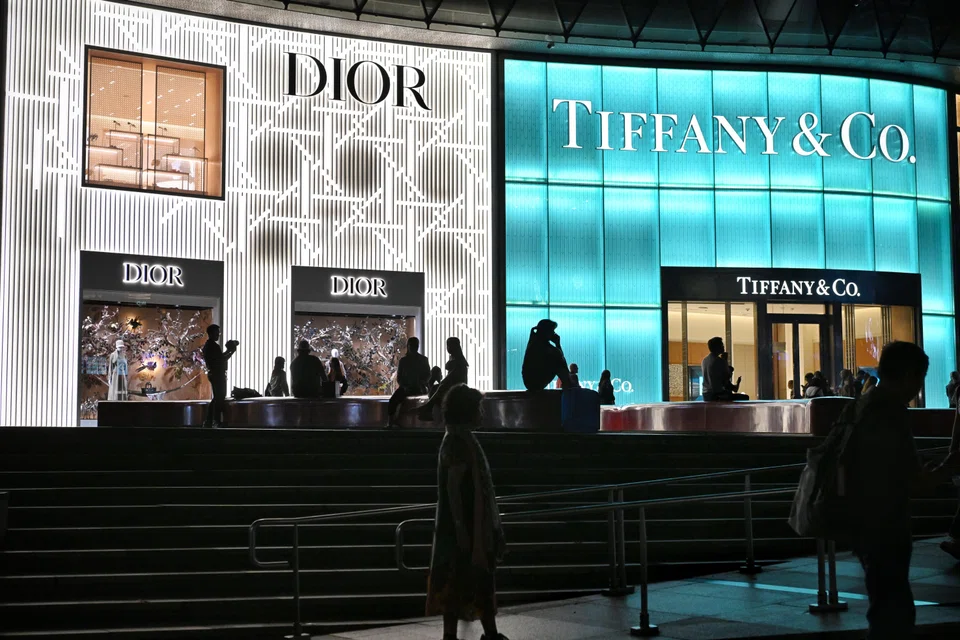
Debate rages over where Orchard Road stands as a shopping destination. However, Ion Orchard, at Orchard Turn, is probably among the most successful malls here.
The recently announced deal by CapitaLand Integrated Commercial Trust (CICT) to acquire a 50 per cent interest in Ion Orchard and the connecting underpass, Ion Orchard Link, from its sponsor CapitaLand Investment (CLI) is arguably a win-win deal.
Based on 50 per cent of the agreed property value, which amounts to S$1.85 billion, the total outlay for the deal is estimated at S$1.1 billion after also factoring in transaction-related expenses, an agreed value for 50 per cent of the property manager as well as 50 per cent of a secured bank loan.
Divesting Ion Orchard is in line with global real asset manager CLI’s asset-light strategy. Upon completing the proposed divestment, CLI will exceed its annual capital recycling target of S$3 billion. CLI will see its funds under management grow by S$1.85 billion and raise about S$1.1 billion, which can be recycled towards future growth opportunities.
As for CICT, it gets a best-in-class asset, grows its Orchard Road presence and enhances portfolio diversity. The trust also sees pro forma distribution per unit (DPU) accretion of 1.2 per cent to financial year 2023 DPU, and 0.9 per cent to H1 DPU from the proposed acquisition.
Moreover, Ion Orchard could enjoy tailwinds from rising visitor arrivals, Singapore’s attractiveness to wealthy individuals, as well as efforts to rejuvenate Orchard Road as a shopping and lifestyle precinct. However, CICT is buying a half-share in Ion Orchard and not all of it, with the remainder being held by Sun Hung Kai Properties.
The announcement of the mega deal comes on the back of improving investor interest in Reits amid softer bond and treasury bill yields, as well as expectations of lower interest rates.
With lower interest rates looming, unit prices of Reits have improved thereby placing them in a stronger position to raise equity. CICT is financing its Ion Orchard acquisition via equity fundraising through a private placement and pro-rata non-renounceable preferential offering.
Acquisition risks
Lower interest rates will likely boost property investment sales as buyers can access cheaper debt as well as equity. Recently, Lendlease and private equity group Warburg Pincus also joined forces to buy S$1.6 billion of industrial assets here from privately held Soilbuild Business Space Reit.
While investors in listed Reits will cheer lower interest rates boosting unit prices of the trusts as well as their DPU via lower borrowing costs, they should be wary of Reit managers bingeing on acquisitions.
Equity raisings by Reits could hurt existing unitholders by dampening unit prices of the trusts or diluting their proportionate interests, or requiring them to cough up money to subscribe for new units to help mitigate dilution. CICT’s unit price closed lower on the day trading in its units resumed after announcing the Ion Orchard deal and the results of the private placement.
Perhaps, the great danger with lower interest rates is the rising risk of property buyers striking bad deals.
Will we start seeing more property deals involving income support? Will deals be struck based on unrealistic assumptions or with insufficient accounting for risks such as a major tenant vacating a building?
Sure, there are many safeguards on interested-party transactions involving listed entities. Still, such deals require deep scrutiny especially when a particular party’s economic interest in the buyer and seller could differ.
Moreover, executing property deals entails much leakage. For its Ion Orchard buy, CICT will incur about S$6.4 million for expenses such as stamp duty, goods and services tax and professionals fees, as well as S$18.7 million of acquisition fees payable in units.
While win-win investment property deals exist, investors need to up the ante to discern what are good deals as the pace of investment property deal-making picks up.
TRENDING NOW

Grab CEO’s wife Chloe Tong on life with Anthony Tan and finding her purpose

HDB reviewing ‘jumbo’ flat scheme after Telok Blangah unit listed for sale at S$2.18m

He built the Vingroup empire. Now South-east Asia’s richest man is handing some key roles to his sons

Singapore judge raises doubts iron ore trader Radiant World is owed US$1 billion

