

CapitaLand needs to pull a rabbit out of the hat for Singapore's largest Reit to multiply
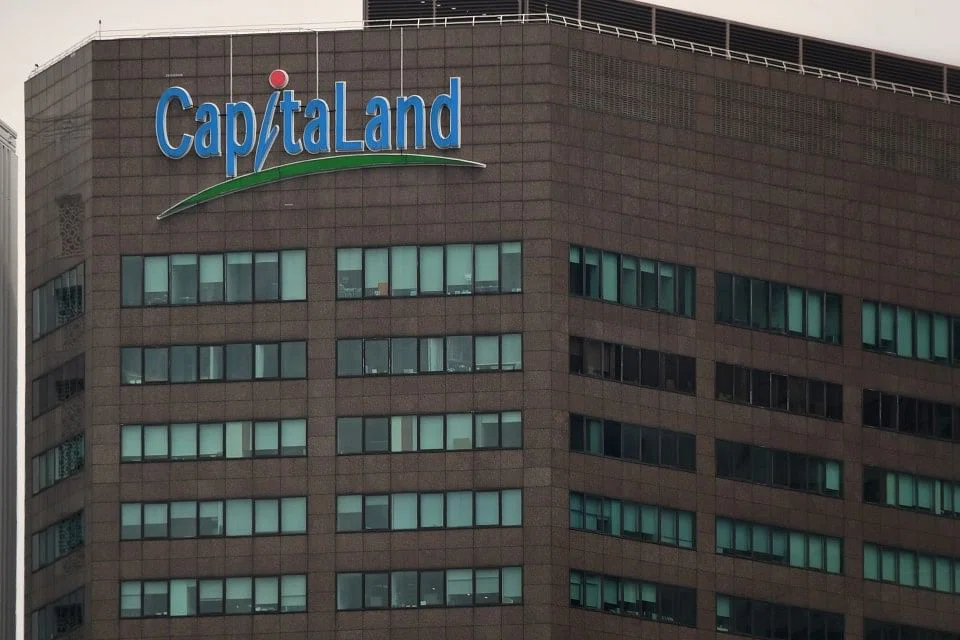
CAPITALAND traded at significant discount to its book value until the real estate giant restructured itself earlier this year, in an exercise that saw its property development business going private while its real estate investment management activities and lodging business remained in the public market under an entity called CapitaLand Investment (CLI).
Since its trading debut at S$2.95 on Sep 20, CLI has climbed 14.2 per cent. It closed on Dec 8 at S$3.37 - a 9.8 per cent premium to its book value of S$3.07 per share as at Sep 30.
Now, the CapitaLand group needs to pull another rabbit out of the hat to ensure CapitaLand Integrated Commercial Trust (CICT) - the largest of its real estate investment trusts (Reits) - remains a useful and viable asset securitisation vehicle.
Previously a retail property-focused Reit called CapitaLand Mall Trust, CICT took on its current moniker after merging with its parent group's office property Reit, CapitaLand Commercial Trust - a move it said would make it easier to raise funds and grow.
However, with the onset of the pandemic and the ongoing disruption of the retailing industry, CICT has struggled to deliver on this promise. Since the beginning of 2020, it has delivered a total return of minus 10.1 per cent.
Earlier this week, it tested the market's receptiveness to its growth story.
On Tuesday (Dec 7), before the market opened, CICT launched a private placement of 103.6 million new units at an issue price of between S$1.930 and S$1.981 apiece to raise at least S$200 million in gross proceeds.
The placement units were eventually priced at S$1.96. With the exercise of the upsize option, a total of 127.6 million new units will be issued, raising the total gross proceeds to around S$250 million.
The issue price represents a discount of 4.6 per cent to the volume weighted average price of S$2.0561 per unit for trades done on Dec 6 - the day before the placement agreement was signed.
'Strong demand'
CICT's manager described the private placement, including the upsize option, as "oversubscribed" and said it drew "strong demand" from new and existing institutional investors.
Based on the middle-of-the-road issue price and the Reit manager's muted statement on the oversubscription rate, market observers can only infer that the private placement enjoyed modest success.
Relative to the size of CICT's market capitalisation, which stood at some S$13.3 billion as at Dec 6, the placement size was relatively small. But it came in the wake of a string of placements by other Singapore-listed Reits (S-Reits).
For example, Manulife US Real Estate Investment Trust (Manulife US Reit) on Nov 30 raised gross proceeds of approximately US$100 million in a private placement.
On Nov 24, Mapletree Logistics Trust said it would raise S$400 million through a private placement. It also plans to raise some S$292.8 million through a preferential offering of new units.
On Oct 13, CICT's sister Reit CapitaLand China Trust raised S$150 million through its own private placement.
Earlier that same month, on Oct 5, United Hampshire US Reit raised around US$35 million in a private placement.
Apart from fundraising exercises by other S-Reits competing for investors' cash, there have also been new additions to the S-Reit universe.
Logistics and industrial Reit Daiwa House Logistics Trust (DHLT) made its debut on the SGX mainboard on Nov 26, while pure-play data centre player Digital Core Reit commenced trading on Dec 6.
Accretive acquisitions
Like its peers, CICT will use its placement proceeds to acquire new assets, which it claims will be immediately accretive to its distribution per unit (DPU).
CICT's manager said S$150 million or 60 per cent of the gross proceeds has been earmarked to fund the proposed A$330.7 million (S$322 million) acquisition of 2 Grade A office buildings in Australia, which was announced late last week.
Including other expenses of A$43.6 million and acquisition fees of A$6.7 million payable in the form of units, CICT's total acquisition outlay for the acquisition will come up to about A$381 million, subject to completion adjustments.
The Reit manager added that some S$95.9 million or 38.4 per cent of the gross proceeds of the private placement will be set aside to partially fund potential acquisitions in Singapore and other developed markets, as well as associated costs, repayment and refinancing of debt and capital expenditure, and asset enhancement initiatives.
The remainder of the gross proceeds from the private placement will be used to pay for the estimated transaction-related expenses.
According to pro forma estimates in CICT's announcements, the placement and acquisitions would have boosted its H1 2021 DPU by 1.9 per cent.
This is assuming a loan-to-value ratio of approximately 50 per cent for the acquisitions, with the balance of the purchase consideration to be funded by a combination of proceeds from the private placement as well as the divestment of its 50 per cent interest in One George Street.
Curiously, around 5 pm on Dec 7, before the placement results were out, CICT's manager walked back its estimated pro forma net asset value (NAV) accretion.
It had originally guided that post-acquisition and placement, the Reit's pro forma adjusted NAV would be 1.5 per cent or S$0.03 higher at S$2.04. However, it subsequently clarified that the Reit's adjusted NAV is "expected to remain largely unchanged" at S$2.01. It did not explain the disparity.
So far, the completion of the placement has not boosted investor sentiment towards CICT.
On Dec 8, CICT closed at S$2.04 - just a whisker below its NAV per unit of S$2.05 as at June 30.
Much of this boils down to CICT's sizeable exposure to shopping malls in Singapore.
Retail properties will still account for the largest segment of CICT's portfolio after the acquisition of the 2 Australian office buildings and the divestment of its interest in One George Street.
On a pro forma H1 2021 basis, the retail sector will account for 39 per cent of CICT's enlarged portfolio by net property income (NPI). Office assets will account for 33 per cent while integrated developments will make up the remaining 28 per cent.
CICT's portfolio will comprise 25 assets with a combined property value of S$22.4 billion. Some 93 per cent of the enlarged portfolio by property value will be based in Singapore, with 4 per cent in Germany and 3 per cent in Australia.
With the benefit of its size, CICT could gradually reconstitute its portfolio by divesting some of its retail properties and acquiring more exciting assets - without putting much of a dent into its DPU.
But this could take a long time.
Perhaps CICT should consider another merger - this time with Ascendas Reit. This could create a real behemoth with relatively less exposure to the retail property sector, which might garner stronger market valuations.
What is stopping such a move that could bode well for CICT and the S-Reit universe in general? Nothing perhaps, but imagination - and a wave of the wand from CapitaLand.
TRENDING NOW

Grab CEO’s wife Chloe Tong on life with Anthony Tan and finding her purpose

He built the Vingroup empire. Now South-east Asia’s richest man is handing some key roles to his sons

Singapore’s S$80 million vertical farm must pass the 50-cent test to succeed
Data centre energy demand from Asean telcos not a ‘big risk’, says industry group

