

Against Evergrande backdrop, CapitaLand shows right boldness
CLI strike is cheered by the market for the right dose of bravery - that is, without reckless debt load
THIS week saw the culmination of the corporate restructuring of CapitaLand Limited (CLL), with the trading debut of CapitaLand Investment (CLI) on Monday.
CLL split its business into a privately-held development arm and a new listed unit for investment management platforms and lodging under CLI, which is positioned as a real estate investment manager (REIM).
Based on pro forma net asset value (NAV) of S$14.7 billion as at December 31, 2020, excluding the effect of acquisitions and disposals, CLI's NAV per share is S$2.823.
On its first day of trading, CLI's share price closed at S$2.95. The share price has rallied further and closed at S$$3.40 on Thursday, which is 20.4 per cent above the end-2020 pro forma NAV.
In an investor presentation, CLL pointed out that a basket of REIMs - including Australia's Charter Hall Group, Goodman Group and Lendlease Group, as well as Hong Kong-listed ESR Cayman - trade at an average of 2.9 times NAV.
Perhaps CLI's board and management may think that CLI should trade at an even loftier premium to its end-2020 proforma NAV.
Still, shareholders of CLL, who are now shareholders of CLI, have much to cheer about. Shares in CLL were trading at more than 20 per cent discount to its latest reported book value prior to the announcement of the corporate restructuring in March.
Many property related plays on the local bourse trade at large discounts to book values. This has led to various property groups being privatised by their major shareholders.
Among property plays, the exceptions that trade at or above book value tend to be some of the real estate investment trusts (Reits).
By modelling itself as a REIM, CLI with S$119 billion of real estate assets under management as at June 30, 2021, appears to be succeeding in convincing investors that it deserves to fetch a premium to book value.
The group, which is behind six listed Reits and business trusts, and over 20 private funds, is also beefing up in its private equity business with senior new hires from BlackRock Real Estate and Brookfield Asset Management.
To be bold, not reckless
How well CLI trades from here on will hinge on CLI's ability to capture global capital flows into Asia to deliver robust financial numbers.
For now, the bold move by CLL to split itself and introduce CLI to the local market, where there is no peer, is paying off.
The management and board of CLL are to be lauded for being bold. Simultaneously, it is the trait of financial conservatism typically associated with Singapore property developers and the virtue of this trait that comes to mind when looking at the woes of Chinese property giant China Evergrande Group.
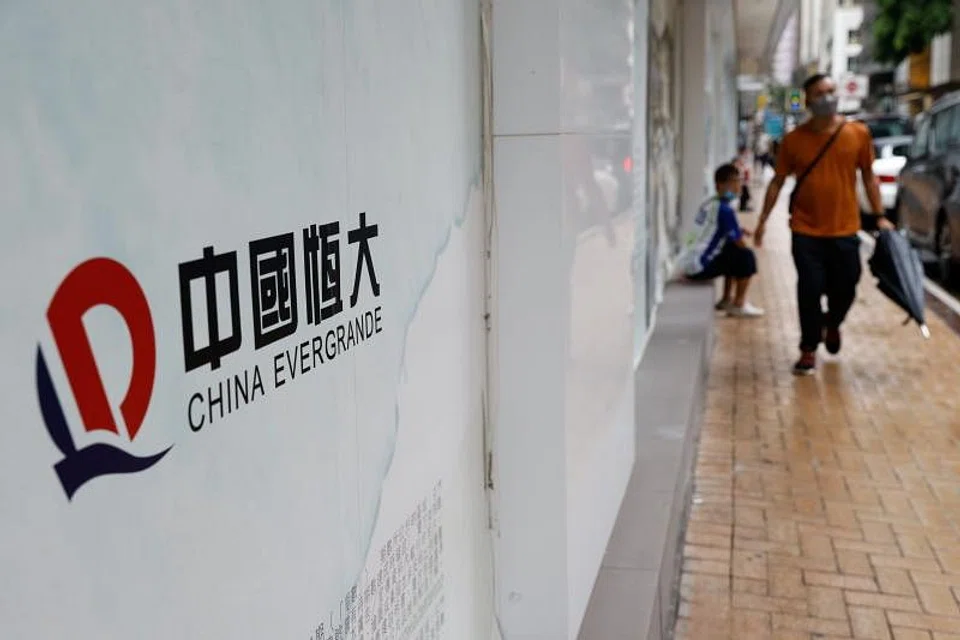
The potential collapse of Evergrande and the risk of contagion is rattling markets in China and beyond. Evergrande is faced with over US$300 billion in liabilities. It has overdue payables related to property development and some of its projects have stalled. Lenders worry over the group's ability to meet debt obligations.
Meanwhile, the pro forma gearing of CLI is about 0.56 times, which is lower than the 0.68 times gearing of CLL as at Dec 31, 2020, the scheme document released in July showed. Given this, shareholders will effectively own a direct stake in a company that is more-asset and capital-efficient, and with a lower gearing ratio, compared to CLL prior to the scheme, said the independent financial adviser.
Debt is a vital cog in property development. Taking on debt allows a developer to embark on larger scale projects and spread equity across more projects, thereby improving the return on equity and overall profitability.
Importantly, cash generation needs to be carefully monitored and managed so that a developer is timely in paying contractors, suppliers and lenders.
Miss making such payments due to cash flow shortages and a loss of confidence by service providers and lenders can send a business teetering.
Singapore groups tend to recognise that the property development business can be cyclical. Markets can overheat and then enter a period when sales slow be it due to excess supply or government intervention.
Earnings from property development are typically lumpy, being tied to progress of sales and project construction.
What this has led to is property groups generally being conservatively geared and building strong recurrent income from investment property portfolios.
All this helps provide certainty in meeting payments to service providers and lenders. It also helps groups tide through times when property sales are slow or when a group has few ongoing development projects.
Financial discipline
Singapore-listed property group UOL Group earned about 55 per cent of adjusted earnings before interest tax depreciation and amortisation in 2020 from property investments, which are largely office and retail properties.
The group's gearing as at June 30, 2021 was 0.29 times. Veteran banker Wee Cho Yaw has a direct and deemed interest totalling around 37 per cent in UOL.
Singapore-listed Wing Tai Holdings, which is active in the property and hospitality businesses, had a net cash position as at June 30, 2021. Wing Tai's chairman Cheng Wai Keung has a direct and deemed interest of around 60 per cent in Wing Tai.
According to its latest annual report, the founder and chairman of Evergrande, Hui Ka Yin, has a majority interest in the group.
Having a tycoon own a large stake in a listed group can give minority investors assurance that the tycoon has skin in the game.
Still, what the problems engulfing Evergrande show is that a tycoon having skin in the game may not offer much protection if a group becomes too aggressive in going for growth.
Evergrande's woes provide a timely reminder of the need to run a business with adequate provision for contingency as business plans may not always pan out the way they are supposed to.
In property development, it may mean holding back from taking on more leverage to take on one project too many or bidding beyond a price that one is comfortable with for a site simply because one is short of landbank and other bidders are flushed with liquidity.
In the current low interest rate environment, financial discipline still matters as credit conditions can tighten with credit becoming both more expensive and scarce.
Also, investors in property names would do well to take heed of how government actions play a major role in the property space. It was government efforts to push for deleveraging of properties groups that exerted pressure on debt-laden Evergrande.
Investors who are now banking on government intervention in resolving Evergrande's debt woes because it is too big to fail are in for a nerve-racking ride.
A business may languish by being too cautious but it can perish by being too adventurous.
Against a backdrop of economic uncertainty and disruption to various real estate asset classes, property groups and investors can study the developments at CLL and Evergrande and pick the right lessons to back the likely global winners.
Knowing when and where to be bold and cautious are critical for long-term success.






