

Cuscaden Peak should focus on growing SPH’s retail and student housing Reits
Leslie Yee
IT HAS been just over 8 months since Cuscaden Peak submitted a proposal to the board of directors of Singapore Press Holdings (SPH) to acquire all the shares of SPH.
Cuscaden has since prevailed over Keppel Corp in the fight for SPH, which was delisted in May. Resulting from acquiring SPH, Cuscaden made a mandatory chain offer for SPH Reit (real estate investment trust).
The chain offer for SPH Reit closed on Jun 30, 2022, with Cuscaden and its concert parties ending up with a stake of 61.7 per cent in SPH Reit.
Cuscaden is 40 per cent held by Tiga Stars, which is in turn 70 per cent owned by Hotel Properties Limited (HPL) and 30 per cent owned by Como Holdings. Tycoon Ong Beng Seng, popularly known by his initials OBS, is the managing director of HPL, where he is a substantial shareholder. Como is ultimately owned by OBS.
Stakes of 30 per cent each of Cuscaden are held by entities of Temasek unit CLA Real Estate Holdings, and Temasek-owned Mapletree Investments. CLA owns privately-held CapitaLand and is the biggest shareholder of CapitaLand Investment (CLI).
With the dust now settled on the corporate action front, what will or should Cuscaden do with unlisted SPH and listed SPH Reit?
SPH Reit
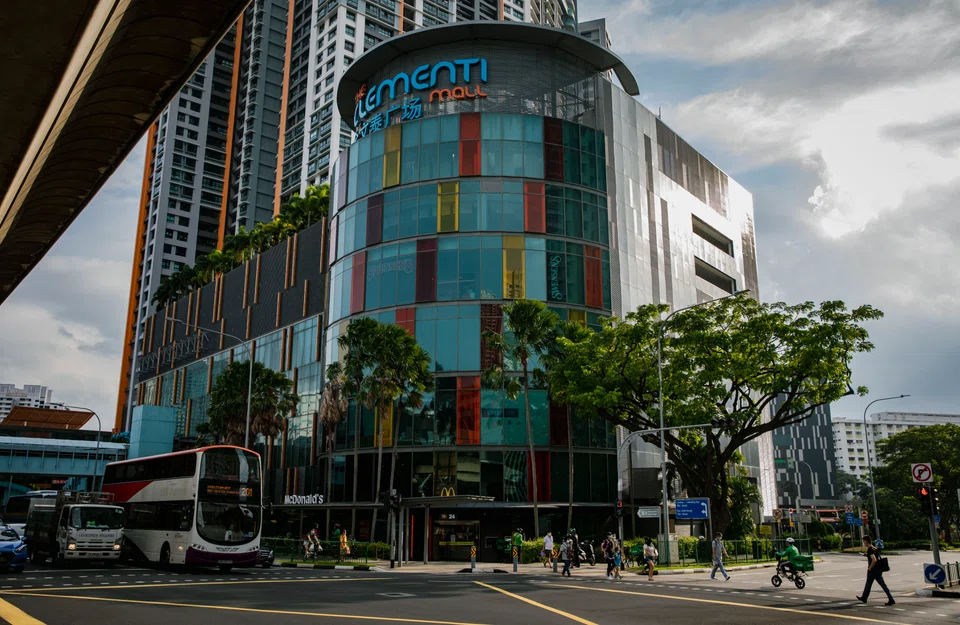
SPH Reit, with total assets and net assets of S$4.28 billion and S$2.89 billion as at Feb 28, 2022, is a crown jewel. SPH Reit’s portfolio includes Singapore assets - Paragon, The Clementi Mall and The Rail Mall - as well as 2 Australian malls.
As at Jun 30, 2022, SPH Reit traded at a slight premium to its end-February net asset value per unit of S$0.92. For its half year ended Feb 28, 2022, SPH Reit posted year-on-year growth in revenue, net property income and distribution per unit.
Looking ahead, SPH Reit could see the performance of its Singapore malls improve amid the country’s opening up.
With their strong track records as sponsors and managers of Reits, each of CLI and Mapletree may be keen to own 100 per cent of the manager of SPH Reit and emerge as the single largest shareholder of SPH Reit, thereby growing their funds under management and fund management income.
Possibly, SPH Reit can subsequently be merged into market leaders such as CapitaLand Integrated Commercial Trust or the soon-to-be formed Mapletree Pan Asia Commercial Trust.
But SPH Reit is not trading badly relative to book value. Also, HPL may be keen to start building a track record in Reit management and to earn stable and hopefully growing returns from owning units in SPH Reit.
Besides SPH Reit, valuable properties that have come into the hands of Cuscaden due to its takeover of SPH include purpose-built student accommodation assets, located mainly in the UK, which were valued at S$1.51 billion for the financial year ended Aug 31, 2021, as well as bungalows in Singapore worth S$144 million and 70 per cent of Seletar Mall, which was valued at S$481 million.
Cuscaden has also become the owner of a 50 per cent stake in The Woodleigh Mall, which is due to be completed soon, and has a gross floor area of around 28,000 square metres.
Perhaps, Cuscaden will be happy to own the stakes in Seletar Mall and The Woodleigh Mall, with an eye to either injecting these assets into SPH Reit or a private fund.
HPL owns retail properties in Singapore such as Forum The Shopping Mall, as well as shop units at Ming Arcade and Concorde Hotel & Shopping Mall. Thus, the rationale for HPL to hold interests in SPH’s retail assets may be strong.
Student housing assets
Possibly, the student housing assets held by SPH can be spun off to Mapletree, which has been actively building scale in this segment and may be looking to launch a student housing Reit. As at Mar 31, 2022, Mapletree’s student housing portfolio comprises 57 assets with over 24,000 beds across 38 cities in Canada, the UK and the US.
But, Mapletree may not be alone in eyeing SPH’s student housing assets. This asset class is sought after for its defensive qualities, and the SPH portfolio may appeal to CLI or Ascott Residence Trust, which is a listed trust in CLI’s stable, whose portfolio includes student housing assets.
As for HPL, it is familiar with the UK market, where it is involved in property development as well as the hotel business. Diversifying its UK exposure to include student housing can make sense for HPL.
Getting more exposure in property asset classes such as retail and student housing can help reduce HPL’s reliance on the hospitality business, where recovery may be uneven.
Time will tell if the shareholders of Cuscaden will harmoniously or perhaps acrimoniously divide the spoils of SPH and SPH Reit. The incentive for different parties to walk away with sole ownership and/or control of different assets can be strong. Each of HPL, Mapletree and CapitaLand may want to fully realise their own vision for Paragon or student housing assets.
Still, dividing up the spoils of victory can be tricky and messy. Time and energy spent on carving out the pie may be better spent on driving operational improvements of the assets.
Perhaps the best way forward is for Cuscaden’s shareholders to own and manage SPH and SPH Reit together as consortium partners. Let SPH compete with Mapletree in student housing, and SPH Reit compete with the commercial Reits owned by Mapletree and CLI.
Cuscaden may wish to focus on growing SPH’s student housing platform and launching an SPH student housing Reit. SPH’s student housing business has critical mass and prospects for the segment in the UK appear to be positive, given the country’s strength in higher education.
Cuscaden can look to invest proceeds from SPH’s joint-venture residential project The Woodleigh Residences and the sale of SPH’s properties, such as the bungalows and aged care homes, into growing SPH’s student housing platform.
Under Cuscaden’s stewardship, may the SPH name live on in the local bourse through a growing retail-focused SPH Reit, and a new SPH student housing Reit.






