

LSE and Brexit: time to tap opportunities in Asia
The sixth-largest stock exchange in the world must look beyond the EU.
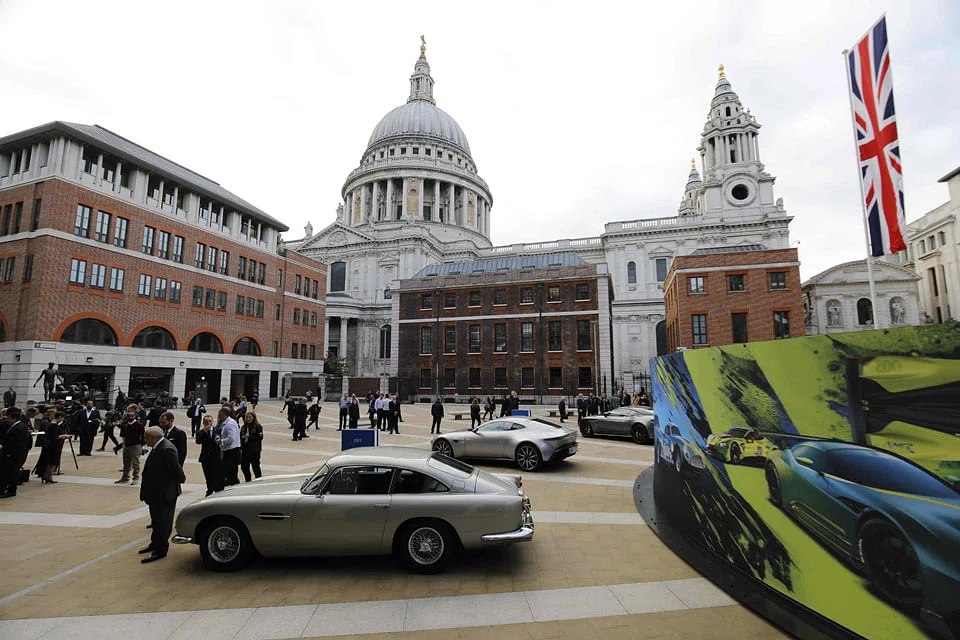
THE London Stock Exchange (LSE) may be the sixth-largest stock exchange in the world and the second in Europe (following Euronext), but it faces huge uncertainties following the Brexit decision from the June 2016 referendum.
Recently, some of the growth of the market has been fuelled by initial public offering (IPOs) from technology firms. In May 2018, Avast, a cybersecurity firm, had its debut on the LSE as the year's biggest tech IPO across Europe and one of the five largest tech IPOs of all time on the London Stock Exchange. The firm raised US$200 million in primary proceeds and US$616.6 million in secondary proceeds.
However, the strength of LSE remains in the financial sector. For example, the constituents of the FTSE 350 index (top 350 firms by market capitalisation listed on LSE) in November 2018 include 95 firms that are in the financial sector. These include banks (10 firms), equity investment instruments (20 firms), financial services (24 firms), life insurance firms (6 firms), real estate investment and services (7 firms) and real estate investment trusts (19 firms). On the other hand, the software and computer services sector, of which Avast is a member, comprises only eight firms.
VOLATILITY MAY BE ON THE RISE
Looking at market capitalisation gives the same picture. The largest firm by market capitalisation on November 30, 2018 was the giant banking firm, HSBC holdings, with a value of £134 billion (S$233 billion). This dwarfs the nearest firm in the software and computer services sector, which is the software firm, Micro Focus Intl, valued at £6.7 billion. Comparatively, Avast is valued at a mere £2.7 billion. Therefore, LSE's strength clearly lies in the financial services sector.
Even when looking at IPOs during the six months from May to October 2018, out of the 26 IPOs, about a third (18) were related to the financial sector while only three (Avast, BigDish, and Funding Circle) were from the technology sector. For example, the biggest IPO was that of Smithson Investment Trust, raising £822 million, compared to the £147 million by Avast.
Given the importance of LSE on the European and world stages, it is important to consider the future of the market amid the uncertainties of Brexit. The impact of Brexit on stock market prices to date has not been overwhelming. This was evidenced by the small drop in overall share prices around the referendum results (the FTSE350 index fell from 3,513 on June 8, 2016, reaching a low of 3,305 on June 14, 2016 - a drop of only 6 per cent). This has since recovered to 3,920 on Dec 4, 2018. The UK stock market during this period appears to be on an upswing, following similar patterns observed globally (for example, the United States).
A growing number of market commentators, however, also warn about rising volatilities. Particularly in the UK, the volatility could be fuelled during the deliberations on the Brexit deal currently offered to the UK government. Although a no-deal exit in March 2019 is presented as a big threat by market participants and politicians across the spectrum, even today it seems to be a plausible scenario.
Some evidence of cautiousness has already been observed. For example, there have been some discouraging IPO results recently. The Aston Martin IPO made a disappointing debut on Oct 3, 2018, dropping from £19 per share to £17.75, and is now trading at £14 (Dec 4, 2018). This IPO was seen as a test of investor appetite in view of the upcoming Brexit in March 2019.
The signs are not good. Therefore, one possibility is that the number of IPOs in the market may fizzle out. There is no concrete evidence of this so far. The month of October was one of the busiest for IPOs during the year with seven firms making their debut. This did, however, include two disappointing IPOs (Aston Martin and Funding Circle).
In addition, there is evidence of the weakening of the British pound (it reached a multi-week low with exchange rate to euro at 1.12 on Dec 4, 2018). This would impact hard on many of the retail firms listed on the LSE that have Britain as their main trading place.
However, this may actually boost the performance of the financial sector, which relies on the EU and the world for most of its activity. For example, HSBC Holdings is headquartered in London. However, it serves customers worldwide from around 3,800 offices in 66 countries and territories in Europe, Asia, North and Latin America, and the Middle East and North Africa. Given the diversity of clientele and that most of the services offered would not be in British pounds, they could actually fare well following Brexit.
Even so, HSBC appears to be concerned and has moved 1,000 jobs from London to Paris, where it will set up its EU headquarters. Other financial institutions that have followed the trend include Lloyd's of London, JP Morgan, Barclays, Bank of America, UBS, and Moneygram. Therefore, financial institutions appear to be wary of the effect of Brexit on the financial services industry.
If the UK leaves the European Union (EU) without a deal, then banks and financial services operating out of London would face troubles dealing with customers in EU countries.
Specifically, they would lose the ability to use the passporting system. The EU passporting system for banks and financial service firms enable them to trade freely in any other EU country with minimal additional authorisation, saving time and money.
This is especially important for the UK, which is the largest exporter of financial services in the EU.
Non-EU firms face significant regulatory barriers to providing cross-border banking and investment services to customers in the EU. There is legislation for third-country regimes which allow non-EU based firms to offer some services. However, they are quite limited. Furthermore, if the UK exits the EU without a deal, it is unlikely that any goodwill between the EU and the UK would remain, which would make it harder to agree on any further concessions or deals that could benefit UK firms.
The status of some financial contracts is also of concern. According to The CityUK, a trade body, the loss of EU passporting in the UK would call into question £26 trillion in derivatives. Given the current rules, clearing in London would no longer be available for clients in the UK. The only option would be for the UK to apply for the "third country" status - which is only possible after March 29, 2018. The EU has promised to treat the LSE as equivalent to exchanges and clearers in the EU on a temporary and conditional basis. Therefore, in the short term there may not be any impact on the stock exchange.
FORGING NEW PARTNERSHIPS
However, in the long term this is a different matter and uncertainty still exists. The LSE has been communicating its contingency plans in case of a hard Brexit in order to reassure investors. But it also acknowledges that it is the provisions of the Brexit deal that will ultimately determine the form of the arrangements. So, while the provisions of the Brexit deal are still unknown today, it is hard to predict the impact of Brexit on LSE's operations with certainty.
One possibility is for the LSE to try to forge partnerships with other exchanges in the EU and beyond. There are some glimmers of hope in this respect. In 2012, the London Stock Exchange Group assumed a majority stake in LCH, a global clearing service firm, offering clearing services across five continents and multiple asset classes. LCH has clearing services in repo and bonds, interest rate swaps, cash equities and equivalents, derivatives, and exchange products. The LSE has also forged alliances with Euronext. Recently, they ended a long-running dispute over derivatives clearing, finalising a deal that keeps the exchanges operator's business at LCH SA, the LSE's French clearing house.
A new 10-year arrangement was made, where Euronext will swap its 2.3 per cent stake in the UK-based LCH Group for an 11.1 per cent stake in the French arm, LCH SA. However, it may be time for the UK to expand out of the EU into other markets.
An example of one such alliance is the London-Shanghai Stock Connect, which aims to link up the Shanghai stock exchange with the LSE. Under the programme, shares of a company listed on a Chinese bourse could be issued by a global depositary bank in London, allowing them to be traded by global investors. At the same time, underlying securities listed in London could be issued by a Chinese bank for offer in China.
Huatai Securities, one of China's largest brokerages, plans to sell US$500 million in global depositary receipts on the LSE once the alliance is completed. The company plans to offer 825 million shares that already trade in Shanghai. Their share price rose 2.5 per cent following the announcement. The possibility for expansion of the client base of the LSE to the Chinese market would be the key factor in this relationship that can benefit the London-based exchange.
Given the breadth of companies listed on the Shanghai exchange and its size (second largest in Asia), this creates opportunities for expansion of the LSE constituents beyond the EU and US. Given the uncertainties around trading in the EU and the difficulty the UK faces on reaching a decision about its relationship with the EU post-Brexit, it may be time to tap into the Asian market.
One drawback is the regulatory requirements by the Chinese authorities in terms of firms listing on the combined exchange. In July 2018, China's mainland exchange said it would bar domestic investors from accessing foreign companies with multiple share classes listed on Hong Kong through Stock Connect, the trading link connecting bourses in China and Hong Kong.
Therefore, more has to be done to allow freedom of capital movement before these alliances would be viable. There are opportunities at this stage in the UK to move beyond the EU and explore further territories. How far this will be pushed will depend on the final Brexit deal reached and its effect on the financial sector.
TRENDING NOW
Stocks to watch: CapitaLand Ascott Trust, Keppel Infrastructure Trust, iFast, ESR Reit, First Sponsor
Indonesia says gas export cuts to Singapore remain within contract terms

If Europe goes to war, the fallout will be felt in East Asia

Government to bring forward raising of retirement age, give employers more financial support to create flexi-load jobs

