Singapore as a new venue for Russian IPOs
Don Agro's initial public offering in S'pore may set a precedent for Russian firms looking to access international capital.
WITH the implementation of a free trade pact with the Russia-led Eurasian Economic Union (EAEU) paving the way for greater business links between Singapore and EAEU markets - which comprises Armenia, Belarus, Kazakhstan, Kyrgyzstan and Russia - Singapore's capital markets could play host to a wave of initial public offerings (IPOs) by Russian firms.
The EAEUs' total gross domestic product (GDP) is estimated at US$1.9 trillion, and in terms of purchasing power parity (PPP) was estimated at US$5 trillion in 2018. The Russian economy, the sixth largest globally, is estimated at US$4.21 trillion on PPP terms.
Russia is also among the most resource-rich countries globally. A 2015 report for the European Parliament estimated Russia's subsoil wealth (oil, gas, coal and minerals) and other natural resources at US$75.7 trillion - which amounts to an immense opportunity for Asian investors.
While they have traditionally tapped the capital markets of London and New York, strategic competition and geopolitical frictions through the 2010s have constrained Russian enterprises somewhat from accessing them.
Singapore's capital markets may emerge as a new node to access international funds, especially amid Russia's geopolitical pivot to Asia. One example of this is the recent Singapore Exchange (SGX) IPO filing of the Russian operator of crop and dairy farms, Don Agro International, which operates in Russia's Rostov region.
The current sanctions regime does not directly preclude investing in the equity of most Russian companies for the majority of international investors. However, by repackaging themselves internationally and listing on SGX, and with vetting from major international advisory and law firms, Russian companies can become even more attractive to investors.
Singapore IPO rationale
There are compelling reasons why a Russian enterprise may choose to list in Singapore, even if the rationale is not immediately obvious. Geographically, close to three-quarters of Russia is in Asia with the Ural Mountains dividing the European and Asian parts of Russia.
Moreover, Russia has a substantial Pacific coast, with geo-economic initiatives such as the Indo-Russia Maritime Silk Road offering prospects for regional development. Russia is also a member state of the Asia-Pacific Economic Cooperation (Apec) forum; the city of Vladivostok hosted the 2012 Apec summit.
The pivot towards Asia by Russia is a strategic and long-term trend, driven by economic and geopolitical reasons, as well as strategic rivalries with the US and Europe. Evidence of this is the development and upgrading of transport infrastructure connecting its European and Pacific regions, with one such project being the renovation and extension of the Baikal-Amur railway. The Russian Far East - which stretches from Lake Baikal to the Pacific Ocean, and constitutes a third of Russia's territory - is also seeing the development of grain and coal transhipping infrastructure on the Pacific coast.
Rich in natural resources, including minerals, hydrocarbons, timber and fish, the region is economically underdeveloped. It faces several challenges, among them a harsh climate, sparse population, increasing out-migration, poor infrastructure and a lack of connectivity.
A maritime corridor linking Chennai to Vladivostok may easily interlock with the Chinese-driven Maritime Silk Road from the South China Sea to the Indian Ocean and beyond, also adding an additional layer to Russia's "pivot to Asia". Asian markets will profit from access to Russia's natural resources and energy, while offering a new investment asset for Asia's emerging middle classes.
As a global financial centre, Singapore is one of two obvious IPO venues in Asia for non-Chinese companies looking to access Asia's capital markets. Hong Kong's bourse offers more liquidity, but the territory is undergoing major civil unrest and is a somewhat less obvious venue for non-mainland Chinese issuers.
The Greater China equity market, much like the Japanese and Indian equity markets, can also pose problems for foreign issuers seeking to access capital. Strong domestic bias by local investors, currency risks, as well as differences in language and business culture may inhibit the ability to tap these capital markets.
A Singapore listing assumes an adherence to relatively high international standards of corporate governance. The international branding that this offers can substantially increase the value of assets for investors. Moreover, due to its small domestic economy, investors are familiar with international firms - close to 40 per cent of the issuers on Singapore's stock market are foreign companies - while many constituents of its stock market indices maintain a regional presence.
According to global valuation & advisory firm Duff & Phelps, the Singapore IPO market recovered strongly in 2019, with US$2.3 billion raised in the year. This is four times the amount raised in 2018, driven by the listings of several large real estate investment trusts (Reits) which included the Prime US Reit, Eagle Hospitality Trust and Lendlease Global Commercial Reit.
As a private wealth hub, Singapore's assets under management (AUM) stood at S$3.44 trillion as at 2018, according to the Monetary Authority of Singapore (MAS). Across the Asia-Pacific, PwC estimated that AUM could almost double from 2017 to about US$30 trillion in 2025, with Singapore set to ride this regional trend.
The downside of a Singapore listing is that companies are vulnerable to global economic pressures due to its open economy, with many IPOs on its bourse being postponed. The last few years have also seen liquidity on its equity markets lag behind regional peers - though industry rumours of reforms by its public sector may ameliorate this in coming years - with secondary markets relatively strong in facilitating fundraising through placements, bonds, rights issues, debt and other financial instruments.
Russian equities have emerged as an attractive value investing market. This is due to the good fundamentals of a low debt-to-GDP ratio for the Russian economy. As at November 2019, Russia's RTS Index year-to-date was the best performing stock market globally; the index reported a 37 per cent return in US dollar terms.
Despite the media discourse and frictions with the US and UK, investors from these jurisdictions still remain, by far, the largest foreign institutional investors (FIIs) in Russian equities. Russia is not a frontier economy like Vietnam or Myanmar but a major emerging market that is a member of the G-20. In 2018, it accounted for 3.12 per cent of global GDP in 2018 in PPP terms.
Its economy is also largely open, though subject to constraints due to Western sanctions. It offers compelling contemporary value and is a market with enduring fundamentals, which also synchronises with Singapore investors' preference for more stable, yield-based counters.
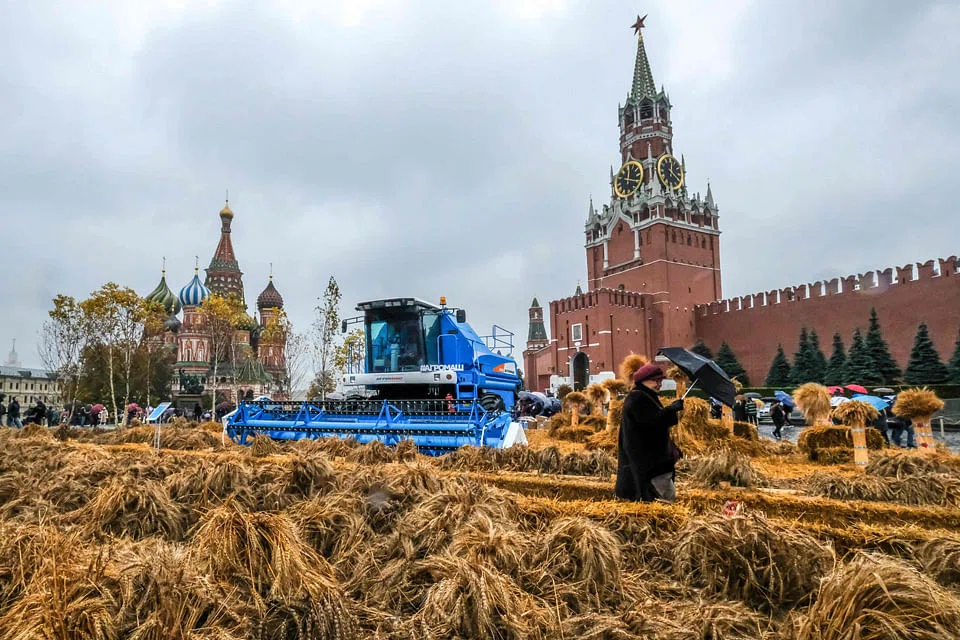
For instance, Russia's agriculture sector is a key strategic sector for the Kremlin, with US$70 billion planned to be invested in Russian agriculture by 2035. Russian agriculture has boomed through the 2010s, due to factors such as the devaluation of the Russian rouble in 2014 and bans on agricultural imports from countries that sanctioned Russia that year.
Due to the rouble's devaluation, Russian grain has gained market share in Africa and the Middle East, leveraging their advantages in geography and weather over competitors in North America, while undercutting prices. Russia's grain traders are now targeting growth markets such as Indonesia and even Mexico. Global macro trends are also driving this, as growing populations drive increasing food consumption.
Rising temperatures and improving technologies also translate to longer growing seasons, higher crop yields and wider swathes of arable land in much of Russia. Its latent agricultural potential is immense; millions of hectares of land abandoned after the Soviet collapse can now be reclaimed. Meanwhile, investments in digital technologies, where Russia lags, can boost productivity. But much of this requires investments into infrastructure development and upgrading, which has seen Chinese capital flow into Russian agricultural assets.
A successful Russian listing could kickstart a wave of IPOs by EAEU and Russian enterprises and entrepreneurs, reinforcing the global connectivity of Singapore's capital markets and its strength as a centre for dividend-yielding assets amid international uncertainty and volatile markets.