

Singapore reinvents itself as Asia's fintech hub
The republic has leveraged its well-developed infrastructure to create a controlled, yet thriving, financial technology ecosystem.
REMITTANCES to developing nations by migrants working abroad have long been an important lifeline for these countries. In Asean, which celebrates its 50th anniversary this year, remittances have contributed to the ongoing economic development and alleviation of poverty in the regional group. With four out of 10 Asean members in the World Bank's top 30 remittance-receiving countries, the importance of this cross-border flow of money within South-east Asia cannot be understated.
While the global remittance market has been traditionally dominated by banks and money transfer operators, the financial technology revolution is now creating newer, more convenient and economical methods of cross-border money transfers. According to the Medici Report, Moving With the Money, by Let's Talk Payments, fintech companies such as InstaReM are disrupting the traditional cross-border money transfer market by exploiting new technologies and processes. This results in time and monetary savings for the businesses and private individuals that use them, by providing fund transfers at costs that are well below traditional remittance rates. These lowered remittance costs are in line with the United Nation's sustainable development target, which seeks to reduce inequality between and among countries.
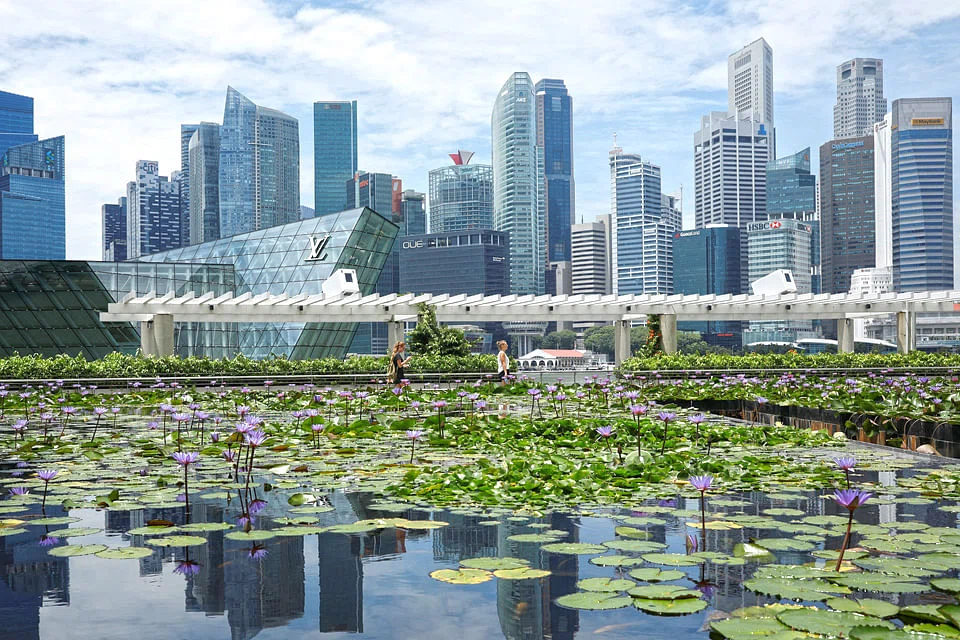
Singapore, in particular, is on its way to reinvent itself as Asia's fintech hub. Backed by solid government support, better-quality private funding and forward-thinking regulatory bodies that promote innovation and sandboxing, the country has leveraged its well-developed infrastructure to create a controlled, yet thriving, fintech ecosystem. This strong fintech ecosystem, coupled with Singapore's huge Asean migrant population, is transforming the country into a regional remittance hub, and has put the nation in a unique position to propel and facilitate the intra-bloc redistribution of wealth, and contribute to the economic development of its regional neighbours.
STRONG SUPPORT
Singapore's fintech landscape enjoys strong support from its central bank and regulatory authority: the Monetary Authority of Singapore (MAS). In 2016, MAS laid out its vision that would help the country transform into a Smart Financial Centre where innovation and technology would be pervasive. Leveraging its regulatory role, MAS has fostered a conducive and supportive environment for innovation by private sector players, and the establishment and growth of remittance startups and next-generation fintech disruptors. This encouraging and open ecosystem has resulted in Singapore achieving the fastest fintech growth rate in Asia. According to financial infrastructure company tryb, there are around 210 fintech firms operating in Singapore - all but a dozen of which started operations in the past two years. Many of these startups are already disrupting the traditional ways of money transfer. As more e-remittance startups begin operations in Singapore, they open up additional cross-border money transfer corridors within Asean, and inject much-needed competition into the traditional money transfer industry, bringing costs down for consumers in the process.
Additionally, MAS recently announced deregulation of the process where banks needed to seek approval before making investments in permissible non-financial businesses. This means greater freedom for banks to invest in or start an arm of non-financial business such as e-commerce e-payment platforms. Not only is MAS encouraging banks to adopt and adapt to the new game-changing business models, the regulatory body is also making a bigger statement - that e-payment and e-remittance would be the way of the future.
In addition to a forward-thinking regulatory body, the country's extensive digital infrastructure has helped support its fintech ambitions. As at 2017, Singapore's Internet penetration stands at 82 per cent, ranking second just behind Brunei's 86 per cent. Coupled with its high smartphone penetration rate of 91 per cent, the city-state has a clear lead over other countries in Asean in terms of providing a conducive environment for the development, and more importantly, for the wider adoption of fintech solutions.
According to professional services firm KPMG, only 27 per cent of South-east Asia's population owned a bank account in 2016, putting the number of unbanked individuals at 438 million. The World Bank also noted that globally, 59 per cent of adults cited a lack of enough money as a key reason for not having a bank account, implying that the poor were being excluded from accessing financial services because of their circumstance. This lack of access to basic financial services has created major barriers to poverty alleviation by rendering it almost impossible for people to borrow or save.
By providing the digital infrastructure required for the mass adoption of mobile, digital fintech solutions, Singapore has given its huge Asean migrant population greater accessibility to money transfer services than ever before, thereby increasing the cost-efficiency and transparency of their international money transfers back home.
INFLUX OF CAPITAL
In its early years, resource-scarce Singapore understood that it had to attract the attention of foreign investors in order to ride the wave of globalisation that was to come. In 2017, its goals have not wavered much. Now, it is seeking to attract large corporations and fintech startups by minimising red tape and providing avenues where fintech businesses can seek aid and advice.
Has this been successful? Without a doubt. According to latest figures, the total stock of foreign direct investment (FDI) in Singapore reached S$1,225.5 billion in 2015, with investments in the financial and insurance sector comprising close to half of the total FDI. As a result of its attractive infrastructure and supportive regulators, investors and businesses are finding Singapore to be an ideal destination to expand and start up, being both a financially lucrative investment on its own and also as a gateway into the rest of the region.
In the nation's relentless push to become a global fintech centre, it has found itself fast emerging as the remittance hub in the bloc. While the impact that this revolution will have on the industry's different players may vary, as customer awareness of fintech products increases, one thing is clear: Consumers will ultimately stand to benefit from this wave of innovation.
By providing a well-developed infrastructure and a supportive regulatory system, Singapore is facilitating the innovation of digital financial solutions that are providing broader access for the region's population to participate in the formal financial system. This increased access to basic services such as the international transfer of money should help the region come out of poverty by reducing income inequality, boosting job creation opportunities, accelerating consumption, and helping those in the low income bracket within the region manage risk and absorb financial shocks.
READ MORE: Heavyweight accelerator may help Singapore fintech punch above its weight
TRENDING NOW

He built the Vingroup empire. Now South-east Asia’s richest man is handing some key roles to his sons
Seatrium allocates S$200 million for new share buyback programme

32 companies, 6 individuals bag accolades at Singapore Corporate Awards 2026
Stocks to watch: Mapletree Logistics Trust, Seatrium, Keppel DC Reit, Food Empire

