

Firm property prices are a silver lining as rising interest rates batter listed property plays
MANY homeowners may be fretting over how rising home loan rates are affecting disposable income. The three-month compounded Singapore Overnight Rate Average (Sora), has jumped by over 220 basis points from the start of the year to 2.45 per cent per annum as at Oct 28, 2022.
For a borrower who is paying 1 per cent plus three-month Sora on a million-dollar home loan with a 25-year tenure, the monthly repayment increases by over S$1,100 when the interest rate rises from 1.2 per cent per annum to 3.5 per cent.
Spare a thought for the listed property groups and trusts, which may be hit even harder by rising interest rates.
Adverse effects
First, higher interest rates add to costs and depress profitability. A property development project costing S$500 million and financed 65 per cent by debt could see a 4 per cent increase in costs, if the annual borrowing cost jumps from 1.5 per cent to 3.5 per cent (assuming an average loan period of three years). Under such a scenario, a gross profit margin of 12 per cent shrinks to 8 per cent.
With an investment property that generates an annual net property income yield of 4 per cent and financed 40 per cent by debt, the return on equity falls from 5.7 per cent to 4.3 per cent.
Second, rising interest rates hit the trading prices of listed property plays as equity investors apply steeper discount rates to value property groups and real estate investment trusts (Reits).
One may have found a Reit that pays annual distribution yield of 4 per cent attractive when the alternative is receiving 0.5 per cent per annum from a Singapore-dollar fixed deposit. When one can earn over 2.5 per cent per annum from a fixed deposit, however, the required distribution yield from a Reit could be 6 per cent per annum.
Likewise, an investor who benchmarks Reits versus Singapore five-year government bonds may now need to get a distribution yield of over 180 basis points more from a Reit, versus the start of the year, in order to mirror the five-year bond yield’s rise from 1.4 per cent per annum at the start of 2022 to over 3.2 per cent as at Oct 28, 2022.
If distribution per unit holds constant, a Reit’s unit price needs to fall by about 17 per cent for annual distribution yield to rise from 5 per cent to 6 per cent.
Resilient property prices
But, the picture is not all bleak: Property-related groups enjoy pricing power due to the strength of physical property prices and rental rates in Singapore. Also, property groups are able to sell overseas assets at above valuation.
Rental and occupancy rates of some offices and malls are benefiting from Singapore’s opening up amid living with Covid. Hotels are seeing business bounce back as international travel recovers and more large-scale events are held, such as the Formula 1 Singapore Grand Prix.
For the period ended September, some Reits posted positive rental reversions plus growth in net property income and/or distribution income. CapitaLand Integrated Commercial Trust’s (CICT) manager said there was strong take-up of the trust’s Singapore office space in Q3 2022 and that leasing activity at its malls here started to pick up in Q3 with demand primarily driven by F&B (food and beverage) operators. Perhaps, improving asset performance can help various Reits provide the higher yield demanded by investors.
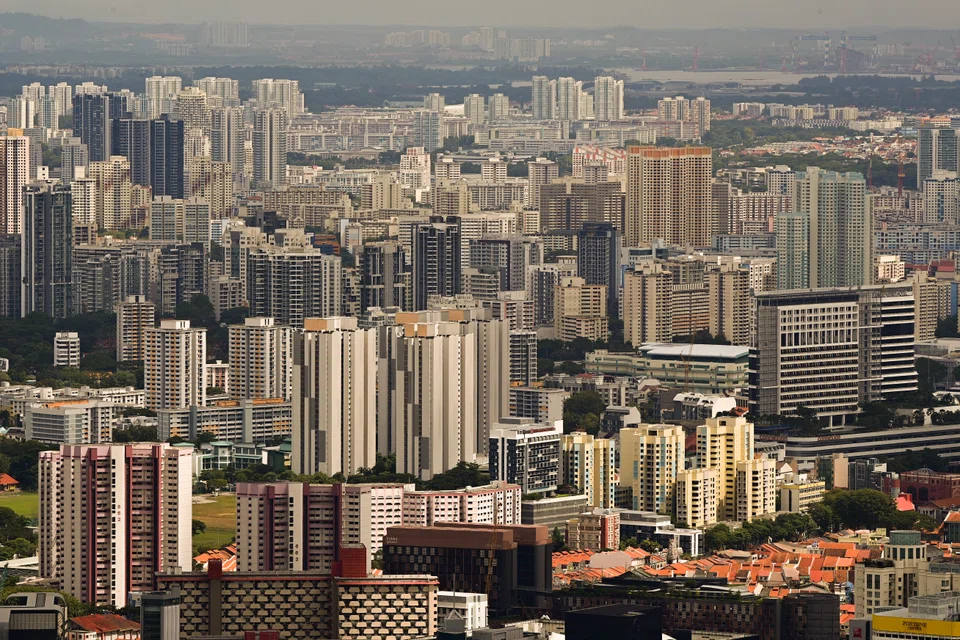
Appetite for physical assets in Singapore is strong. Private home prices in Q3 2022 rose 13.6 per cent from a year ago, according to the Urban Redevelopment Authority. New private homes sold in September more than doubled month on month, helped by major launches – Lentor Modern and Sky Eden@Bedok – that set new price benchmarks for suburban housing.
Outside of homes, the trustee of ESR-Logos Reit entered into a sales contract in late September to divest the trust’s purpose-built industrial building at 2 Jalan Kilang Barat in Singapore for S$35.3 million – translating to a 21.7 per cent premium to valuation.
Meanwhile, Stamford Land entered into an agreement in October to sell the property that houses the hotel Stamford Plaza Auckland in New Zealand for NZ$152 million (S$123 million) or about 8.5 per cent above market valuation as at end-March. Stamford Land is also selling Sir Stamford at Circular Quay, Sydney, Australia, which is mainly used as a hotel.
Despite woes afflicting China’s real estate sector, EC World Reit’s manager announced in early October the trust’s proposed divestment of indirect interests in stage 1 properties of Bei Gang Logistics and Chongxian Port Logistics, which are located in China, at the agreed property values of 1.2 billion yuan (S$243 million) and 820 million yuan, respectively, representing a premium of 2.9 per cent to each of their end-June appraised valuations. The manager expects to use the divestment proceeds largely to finance loans repayment, and also to pay unitholders a special distribution of around 451 million yuan.
The risk is whether rising interest rates will sting listed property entities further via hurting demand for their products. Higher home loan rates plus recent cooling measures may slow new home sales in Singapore and cause prices to soften.
Spending at malls and hotels could be affected by consumers having less disposable income due to rising debt costs. Demand for office and industrial space may weaken as higher financing costs hit cash flows and expansion plans of businesses.
Also, higher borrowing costs can reduce liquidity of chunky buildings. Premium commercial buildings here may outperform relative to other markets, should property investors overweight Singapore due to its safe haven and international gateway status. But, the capital values of buildings may dip because investors use higher capital costs to assess acquisition opportunities.
Trading prices of listed property entities have taken a beating over the past several weeks. As at Oct 28, 2022, City Developments Ltd traded at a discount to its end-June net asset value (NAV), adjusted for inclusion of fair value gains from investment properties, of 54 per cent; while CICT traded at a discount to end-June NAV of 11 per cent.
The equities market may be more than adequately pricing in the headwinds from higher interest rates – provided demand for physical properties stays strong, thereby supporting capital values and rental rates of properties.
TRENDING NOW

Government to bring forward raising of retirement age, give employers more financial support to create flexi-load jobs

If Europe goes to war, the fallout will be felt in East Asia

Indonesia stocks suffer worst plunge in nearly 30 years as MSCI proposes standalone status

Vietnam’s northern provinces, not Hanoi or Ho Chi Minh City, are powering near 10% GDP growth

