

Office rents in Singapore’s central region rise at a slower pace of 2.1% in Q3
Observers predict further slowdown in rent increases as leasing demand starts to falter amid macroeconomic uncertainties
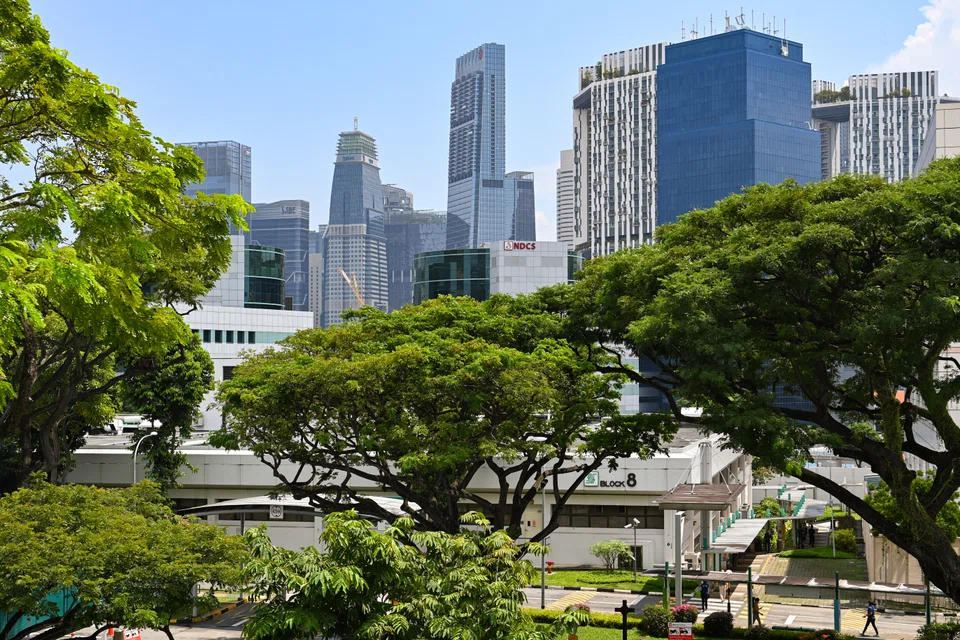
OFFICE rents in Singapore’s central region rose 2.1 per cent in the third quarter of 2022 over the preceding quarter, a slower pace of increase compared with the 2.4 per cent quarter-on-quarter (qoq) rise in Q2 2022.
This takes the total increase in the Urban Redevelopment Authority’s rental index for office space in the central region to 6.3 per cent in the first three quarters of 2022, following a full-year 2021 increase of 1.9 per cent.
Some property consultants predict that Singapore office rental growth can be expected to slow further in the fourth quarter, with the trend continuing next year as demand starts to weaken amid the uncertain macroeconomic environment. On the other hand, the countervailing factors cited for rental growth include a continuation of tight supply. Moreover, landlords have begun to pass on higher service charges (due to inflationary pressures) to tenants, resulting in higher gross effective rent figures.
Islandwide net office demand, as measured by the change in occupied space, increased by 258,334 sq ft of net lettable area (NLA) in Q3 2022, the same as that in the previous quarter. This takes the total net demand in the first nine months of 2022 to positive 376,737 sq ft, a reversal of the negative demand figures of 613,542 sq ft for the whole of 2021 and 850,348 sq ft in 2020. Pre-Covid, net demand for 2019 was positive 1.67 million sq ft.
The islandwide stock of office space shrank by 21,528 sq ft of NLA in Q3 2022, a smaller drop compared with the decrease of 473,612 sq ft in the previous quarter. The islandwide vacancy rate of office space dipped to 11.7 per cent as at the end of Q3 2022, from 12 per cent as at the end of Q2 2022.
CBRE’s head of research for South-east Asia, Tricia Song, said that key office demand drivers in Q3 were expansions by tech firms, flexible workspace operators and non-banking financial companies. “CBRE Research notes that fresh pre-commitments to upcoming new projects such as Guoco Midtown and IOI Central Boulevard Towers were also inked during the quarter.”
In July, The Business Times reported that Amazon signed a lease for about 369,000 sq ft at IOI Central Boulevard Towers. Pacific International Lines is understood to have signed a lease for two-and-a-half floors at Guoco Midtown totalling around 60,000 sq ft.
Cushman & Wakefield’s head of research for Singapore, Wong Xian Yang, said: “While we remain positive on the mid to long-term outlook of the Singapore office market, demand and rental growth could slow in Q4 2022 and 2023, as tightening financing conditions and an uncertain macro outlook dampen office demand.
“Tech companies, a key source of office demand, would be weighed down by tightening financing conditions as they adopt a wait-and-see stance and assess market liquidity.”
In similar vein, Colliers’ research head for Singapore, Catherine He, said office leasing enquiries have slowed in Q3 2022. “For the rest of 2022, geopolitical and economic headwinds as well as higher volatility in the equity markets have led to some firms announcing a hiring freeze or layoff. With companies becoming more conservative in their hiring or expansion plans, leasing demand is likely to be impacted,” she added.
On a more positive note, He said that multinational companies with healthy financials will continue to be attracted to Singapore for its macroeconomic stability and geopolitical neutrality.
The office rental growth in Q3 2022 was broad-based. URA’s data shows that the monthly median rental rate (based on contract date) for Category 1 office buildings (covering the better-quality buildings in the city area) rose 5.6 per cent qoq to S$10.66 per square foot (psf) in Q3 2022, contrasting with a drop of 1.6 per cent in Q2 2022.
The median monthly rent for Category 2 or the remaining office space in Singapore rose 3 per cent qoq to S$5.57 psf in Q3 2022, a bigger increase compared with the 1.7 per cent gain in Q2 2022. “Landlords were emboldened to raise their rental expectations in the tight supply environment,” said CBRE’s Song.
Colliers’ He pointed out that an ongoing withdrawal of existing stock for redevelopment (such as Fuji Xerox Towers and AXA Tower) has also exacerbated the office shortage.
JLL’s head of research and consultancy for Singapore, Tay Huey Ying, said that the tailwind from the reopening of Singapore’s economy helped the office leasing market to hold steadfast against the global economic headwinds and supported another quarter of rent increase in Q3 2022, albeit at a slower pace than in the previous quarter.
Demand continued to gravitate towards the newer and good-quality developments in the CBD that are more suited to accommodating the evolving workplace requirements, in particular, with regard to sustainability and employees’ health and well-being.
Tay added: “Nonetheless, there is increasing wariness among occupiers in light of the worsening global and domestic economic headwinds, and more are putting expansion and relocation plans on hold. This could intensify the competition among landlords of existing office buildings for replacement tenants to backfill spaces vacated by tenants relocating to the newer developments, and moderate rent hikes in the coming months.”
The gross effective average monthly rental value for JLL’s CBD Grade A office basket has climbed 8.1 per cent in the first nine months of 2022 and could close at about 10 per cent increase for full-year 2022. This would be a bigger increase compared with the 4.3 per cent rise for the whole of last year. Tay expects the rental growth to ease to below 5 per cent in 2023.
Also sounding a cautionary note on the future supply situation is Edmund Tie’s head of research and consulting, Lam Chern Woon.
“With the recent completion of Hub Synergy Point in Anson Road and the upcoming completions of Guoco Midtown office tower along Beach Road in late-2022 and IOI Central Boulevard Towers in 2023, the increase in supply of office spaces over the next 12 months will see competition among owners of the new buildings as they look to firm up on leasing deals.”
TRENDING NOW

He built the Vingroup empire. Now South-east Asia’s richest man is handing some key roles to his sons

Grab CEO’s wife Chloe Tong on life with Anthony Tan and finding her purpose

What role can Japan play in Asean’s future?

From folding clothes to factory work: Why China is sending humanoid robots to school

