

Funding crunch in Apac commercial real estate opens doors for local property players
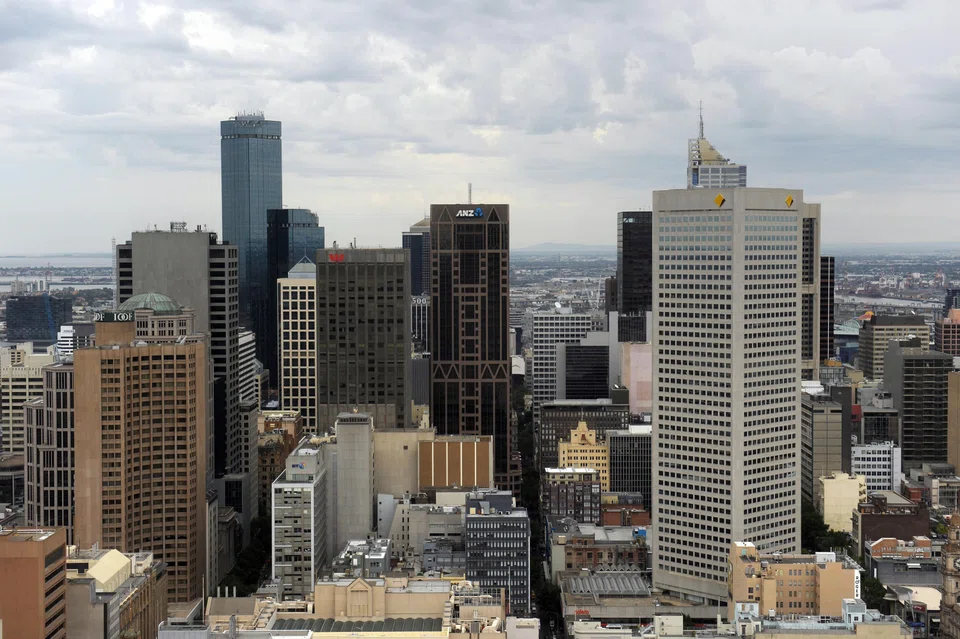
COMMERCIAL real estate markets in the Asia-Pacific (Apac) region face a US$5.8 billion funding gap between now and 2025 – but therein lie pockets of opportunities for local property players eyeing assets in distress.
In a report on the Apac commercial real estate debt market, CBRE estimated that the region has around US$177 billion of outstanding senior loans as at the first quarter of 2023. A funding gap of US$5.8 billion is expected to emerge through 2025, primarily due to declining capital values in today’s high interest rate environment, said the property consultancy.
The gap is calculated as the difference between the original equity value of an investment and the credit likely to be available for refinancing when the loan matures.
According to CBRE, the funding gap will begin in Australia and Korea in the coming year, before spreading to Japan in 2025.
In terms of total volume, Australia will face the biggest funding gap from now to 2025, followed by Japan, Korea and mainland China.
The report showed Singapore as the lone exception, with no expected funding crunch in the same period.
Capital values of some local commercial properties are likely to decline in the coming few years, due to an expansion of capitalisation rates (cap rates) amid interest rate hikes, said Henry Chin, CBRE’s global head of investor thought leadership and head of research for Asia-Pacific.
Still, values are coming off a high base, since the Singapore market had booked “quite substantial increments” in capital values in the past two years, Chin told The Business Times.
Investment volumes in Singapore’s commercial real estate market rose by 26 per cent year on year in 2022, unlike in other Apac markets, which saw declines of 10 per cent to 38 per cent.
For Australia, CBRE pointed out that their main concerns would be cap rate expansion and debt maturing in 2024.
“(But) many Australian real estate investment trusts (Reits) used 2021/2022 as an opportunity to extend their loan maturities and offset any refinance risks in the interim,” it said.
“Korea will face more immediate pressure, with 73 per cent of the total funding gap in this market due to emerge in 2023.”
The markets that are forecast to see the highest funding gap, as a proportion of the original equity amount, are the Australian and Hong Kong office sectors, as well as the Korean industrial sector.
The Australian and Hong Kong office sectors are predicted to have a gap of 26 per cent and 25 per cent, respectively, for new three-year senior loans maturing in 2023. This drops to 19 per cent for loans maturing in both markets in the following year.
Meanwhile, the Korean industrial sector is expected to experience a funding gap of 22 per cent for loans maturing in 2023. This swells to 27 per cent for loans maturing in 2024.
CBRE noted that the office sector is especially exposed to refinancing risks, and thus is likely to face the “greatest funding gap of any sector”.
This is mainly due to weakening investment sentiment and the rising cost of debt, which would drive capital values down, it said.
Apac office yields might consequently soften by 75 to 150 basis points (bps), said the consultancy. It also expects capital values in most markets to drop by 5 per cent to 20 per cent in the next three years.
Meanwhile, the funding gap will be “minimal” for the retail and industrial sectors, highlighted CBRE.
The former had already seen a correction in capital values at the onset of the pandemic; and for the latter, the cap rate compression experienced in the past few years is “still far greater than the forecast softening”, it said.
“Korea is the only logistics market in Asia-Pacific that will experience a significant refinancing challenge, with cap rates forecast to expand by 160 bps from peak-to-trough in combination with significant increases in borrowing costs.”
CBRE noted that growth in interest expenses may force some smaller investors and developers to offload assets and “shore up balance sheets in the short-to-medium term”. Developers and fund managers with refinancing risks in these markets are therefore likely to be net sellers in the coming year, it said.
Investors who are unable or unwilling to invest additional cash will also be forced to “return keys to lenders”, as “falling values and rising financing costs make it challenging to justify original underwriting assumptions”, said the consultancy.
Still, this could be an opportune time for equity investors to acquire assets on more “attractive valuations”, said CBRE.
Some Singapore players have already moved in. Mapletree Investments and Hong Kong-headquartered investment firm PAG formed a 50:50 joint venture in January to acquire Goldin Financial Global Centre in Hong Kong for HK$5.6 billion (S$953.7 million). PAG had noted that the agreed price was well below market value and represents “good value at a significant discount to replacement cost”.
In October 2022, CapitaLand Investment acquired Grade A office tower Borui Plaza in Beijing for 2.04 billion yuan (S$404 million) – a discount of 30 per cent from its earlier valuation of 2.9 billion yuan.
An Apac capital trends report by research firm MSCI Real Assets showed that more than US$2.5 billion worth of distressed sales were recorded in the first quarter of 2023. This represents almost 10 per cent of overall sales volume.
Besides the Goldin Financial Centre deal, Q1 2023 saw 10 other mortgagee sales in Hong Kong.
“The build-up in distressed sales had begun as early as 2021, but given the turmoil that real estate financing markets in China had undergone over the past year, volume broached the US$2 billion level in each of the last two quarters,” noted MSCI.
Tricia Song, CBRE’s head of research for South-east Asia, pointed out that Singapore Reits are generally very well-diversified, with assets both locally and overseas.
Some local developers might therefore engage in more capital recycling, selling their mature or non-core assets in Singapore and using that to expand abroad, she said.
CBRE also noted in its report that “there will also be solid prospects for alternative lenders, as returns for debt strategies are likely to outperform equity investments during this period”.
TRENDING NOW
Nvidia prepares to oust Jensen Huang who had second affair with exec: reports
Special dividend for SIA’s 80th anniversary? CEO says extra payout will need board’s nod

Higher rates, weaker spending: Is the Philippines entering stagflation?
Who could replace Jensen Huang? Nvidia’s top engineer and CFO tipped as CEO candidates

