

Higher prices, Covid-hit household income lower relative affordability of HDB resale flats in 2020
Singapore
HOUSEHOLDS in Singapore might need to save up more or take a slightly bigger mortgage to buy a Housing Board (HDB) resale flat, based on median incomes and prices in 2020.
Overall median prices of HDB resale flats transacted last year were about 3.9 times a household's median yearly earnings. This is a tad higher than 3.5 times in 2019, based on The Business Times' (BT) analysis of data from SRX, OrangeTee & Tie and the Department of Statistics (DOS).
The 2020 price-to-income multiple - known as an "affordability ratio" - suggests a household, without spending on anything else, has to save for 3.9 years to buy a public housing flat from the resale market.
The last time the ratio reached that level was in 2015 and 2016, before it resumed a gentle downtrend in the next three years, including in 2018 when a major round of cooling measures were introduced.
This means 2020 marked the ratio's first increase in seven years for HDB resale flats in general.
It reflects how household incomes, in the year of a pandemic outbreak, declined for the first time in more than a decade. DOS figures showed Singapore's 2020 median monthly household income from work falling 2.5 per cent year-on-year to S$9,189. In contrast, the HDB resale market ended 2020 on a strong note amid buoyant demand. Prices rose 5 per cent for the whole year - the steepest increase since the fourth quarter of 2012.
BT's analysis of the affordability ratio uses median property prices - based on absolute price quantums achieved in transactions - across all flat sizes, remaining land leases and locations. Median annual household income was derived by multiplying by 12 the median monthly household income from work including employer CPF contributions.
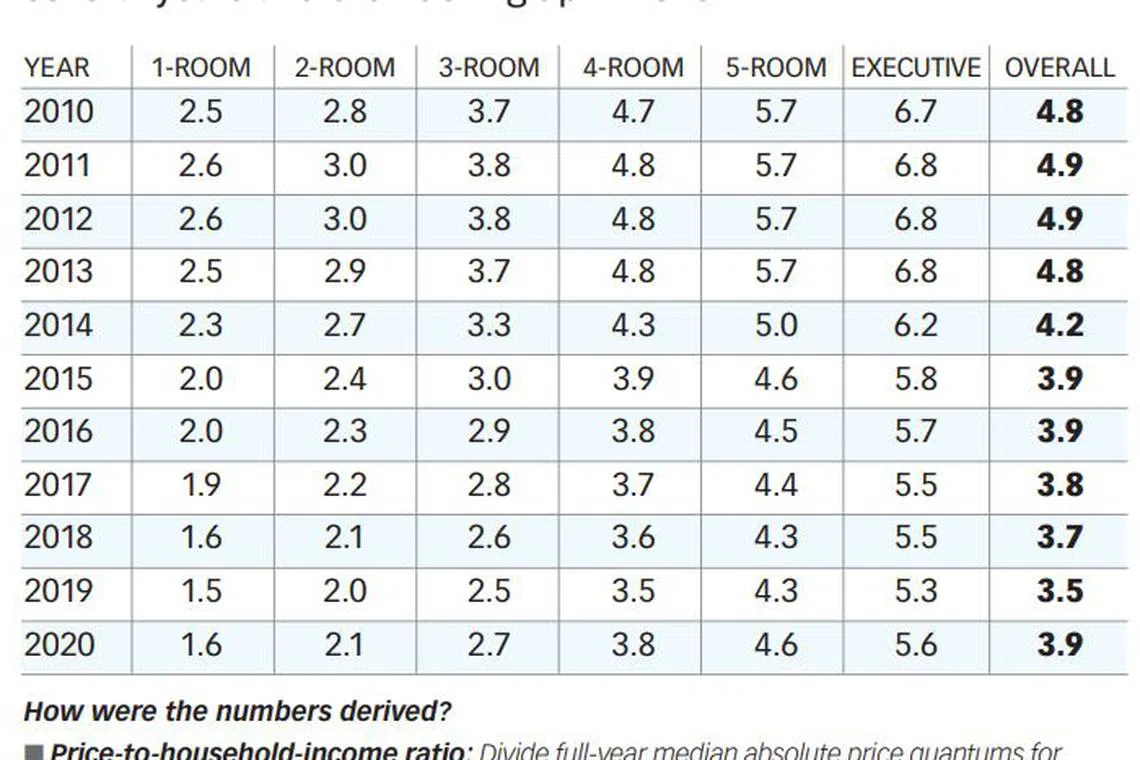
Although the 2020 gap between prices and incomes is the widest since 2016, it is already "much better" than the 4.8-4.9 ratios in 2010-2013, noted Colliers International research head Tricia Song. And on an absolute basis, last year's 3.9 ratio "still looks very low", she added. For perspective, data shows that between 2010 and 2020, median income growth was 45 per cent. In that same period, the overall median price of HDB resale flats grew about 15 per cent.
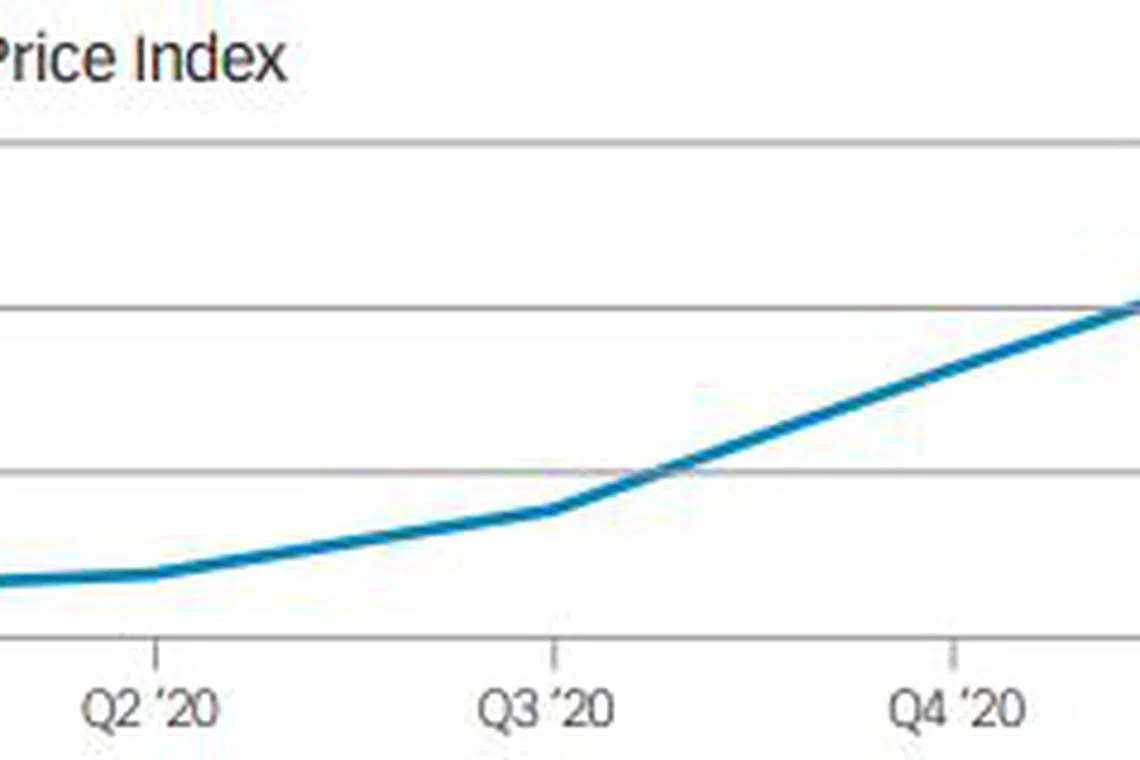
In the last quarter of 2020, growth in the HDB resale price index accelerated to 3.1 per cent quarter-on-quarter, pointed out ERA Realty research head Nicholas Mak in a recent commentary. This was the highest quarterly rate of price growth since the third quarter of 2011 when the HDB resale price index grew by 3.8 per cent quarterly.
Barclays regional economist Brian Tan said the price-to-income ratio's growth in 2020 should be seen in the context of the "astonishing" price jump in the second half of the year.
The HDB resale price index climbed 5 per cent in the whole of 2020 - faster than the 0.1 per cent uptick in 2019, and driven by year-on-year increases of 5 per cent in Q4 2020 and 2.3 per cent in Q3 2020.
"The speed in the second half is a little worrying," Mr Tan told BT. "It could be an indication of investment demand spilling over from the private segment to public housing, and price pressures potentially broadening into the rest of the market."
HDB resale prices in the first quarter of 2021 climbed 2.8 per cent from the previous quarter, and were up 8 per cent year-on-year, according to flash estimates. These prices were just 5 per cent lower than the peak recorded in the second quarter of 2013, OrangeTee & Tie senior vice-president of research and analytics, Christine Sun said. A new peak may be formed by the second half of this year if the current pace of price growth is sustained, she added.
ERA Realty's Mr Mak expects the HDB resale price index to increase 7-10 per cent in 2021. "The last time it grew at this rate was in 2011 and 2012, before the government intervened by reducing the mortgage servicing ratio from 35 per cent to 30 per cent, as one of the cooling measures," he said.
OrangeTee & Tie's Ms Sun pointed out that the Covid-19 pandemic's impact was a "major confounding factor" on housing affordability.
For instance, the lower-income groups were hit harder financially whereas the upper-income groups fared better in general. "Thus we cannot say affordability worsened across the board and therefore is a cause for concern," she said. "If the pandemic situation recovers, affordability would probably improve this year or next year, even for the low to middle-income groups."
Early this year, the government reiterated that the housing market should remain "stable and sustainable" for Singaporeans. Earlier this month, Monetary Authority of Singapore (MAS) chairman and Senior Minister Tharman Shanmugaratnam also warned home buyers about rising interest rates, which raises cost of debt.
For private non-landed homes, BT earlier reported that the gap between median household incomes and prices of new sales continued to grow in 2020 to its widest in a decade. The affordability ratio for new condos rose to 15.4 last year, from 14.7 in 2019, based on median per-square-foot prices multiplied by a standardised 1,000 square feet unit.
The strength of the overall residential market, including private housing, has prompted analysts to speculate that the government could introduce another round of property curbs.
Still, the government may want to monitor the economy's performance in Q1 this year before deciding on any new measures, Ms Sun said. "If Singapore's gross domestic product (GDP) picks up substantially in Q1 2021, then the price growth of properties may not be such a major issue," she added.
Private-sector analysts expect GDP to shrink 1.1 per cent year-on-year in Q1 2021, better than the 2.4 per cent contraction in Q4 2020. They also foresee the economy turning around in Q2 2021 with a 14.6 per cent year-on-year GDP growth, according to MAS' latest quarterly survey.
READ MORE:
- Million dollars for a coveted HDB unit not an aberration
- As rates rise, what should consumers watch for in their mortgages?
- HDB resale prices rise for 9th straight month in March
- HDB Q1 resale prices up 8% yoy, with 53 million-dollar flats sold
- Are rising HDB prices the new normal?
- The other Covid contagion - around the world, property prices are rising
TRENDING NOW

He built the Vingroup empire. Now South-east Asia’s richest man is handing some key roles to his sons

Grab CEO’s wife Chloe Tong on life with Anthony Tan and finding her purpose

What role can Japan play in Asean’s future?

From folding clothes to factory work: Why China is sending humanoid robots to school

