

Hikes in DC rates mirror broad-based recovery in most segments of S'pore property market
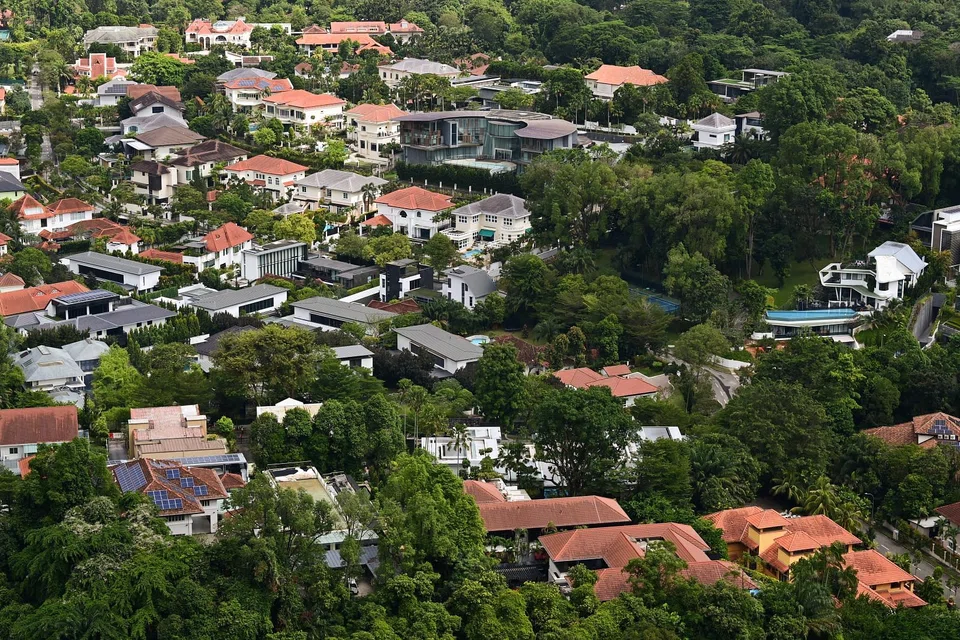
Reflecting the broad-based recovery in most segments of Singapore's property market in the past 6 months, the government has raised development charge (DC) rates for the landed and non-landed residential, commercial and industrial use groups.
The exception was for the use group that includes hotels - a sector that has posted a relatively muted performance under the weight of the prolonged pandemic - which saw a 0.7 per cent drop in the average DC rate for the next half-year starting Mar 1, 2022.
Developers pay a DC for the right to enhance the use of some sites or to build bigger projects on them. The Ministry of National Development has raised DC rates for the landed residential use group by an average of 4.8 per cent and those for non-landed residential use by an average of 0.3 per cent for the the Mar 1 to Aug 31, 2022 period.
ERA Realty Network head of research and consultancy, Nicholas Mak, noted that the Urban Redevelopment Authority's price index for landed residential properties rose 6.6 per cent in the second half of 2021, outpacing the 6 per cent rise in the price index of non-landed private homes over the same period.
Huttons Asia's senior director of research, Lee Sze Teck, also highlighted strong demand and prices in the Good Class Bungalow segment.
JLL's head of research and consultancy for Singapore, Tay Huey Ying, described the 0.3 per cent average rise in the DC rate for non-landed residential use as modest, given the pick-up in non-landed private home prices and collective sales activity in H2 2021.
"The chief valuer had likely factored in the expected easing of market exuberance in light of the December 2021 cooling measures."
Tay added that the collective sales market will remain supported by developers that are eager to replenish their land banks given unsold inventory has declined to an all-time low of 14,333 as at the end of Q4 2021. "That said, developers are expected to remain selective given the added risks such as higher additional buyer's stamp duty rates, rising interest rates and higher construction costs."
MND also announced average DC rate increases of 0.7 per cent for commercial use and 2.2 per cent for industrial use.
The DC rates remain unchanged for the remaining use groups: place of worship/civic and community institution; open space; agriculture; and roads/railways.
MND revises the rates on March 1 and Sept 1 each year, in consultation with the taxman's chief valuer (CV). DC rates are based on the CV's assessment of land values and take into consideration recent land sales. They are stated according to use groups across 118 geographical sectors in Singapore.
For the landed residential use group, DC rates have been increased in all 118 geographical sectors by between 1 per cent and 10 per cent. The biggest hike of 10 per cent applies to Sector 67 (which includes Nassim, Orange Grove, Ladyhill and Fernhill areas).
For non-landed residential use, DC rates were raised in 6 geographical sectors by 3-15 per cent, while being left unchanged in the remaining 112 sectors. The biggest increase of 15.4 per cent is for Sector 92 (which includes Guillemard, Mountbatten, Dunman and Tanjong Katong areas).
Leonard Tay, head of research at Knight Frank Singapore, this was most probably due to the sale of the consolidated private freehold development sites at Thiam Siew Avenue (sold at S$1,488 psf per plot ratio (psf ppr) in November 2021), and the state tender for the Jalan Tembusu plot which was awarded for S$1,302 psf ppr.
Sector 50 saw a 7.7 per cent DC rate hike which Tay attributes to the collective sale of La Ville in Tanjong Rhu at S$1,540 psf ppr.
For commercial use group, DC rates have been increased by 3 per cent in 29 sectors, and unchanged in the remaining 89 sectors. The sectors affected by the 3 per cent increase include the central business district, Chinatown, Boat Quay, Clarke Quay, Robertson Quay, Farrer Park, Bukit Timah Road, Oxley area, Tanglin Road and River Valley Road.
Cushman & Wakefield's head of research for Singapore, Wong Xian Yang, highlighted the string of office deals in the past half year including One George Street, PIL Building and Robinson 112. JLL's Tay also pointed to the first sign of recovery in the retail property market in Q4 2021 and strong sentiment in the shophouse market.
For the industrial use group, DC rates have gone up in all 118 sectors by between 2 per cent and 5 per cent. The largest increase is for Sector 114 (Boon Lay/Jurong West/Pioneer/Tuas/Sungei Kadut/Choa Chu Kang/Lim Chu Kang area).
As for the hotel use group, DC rates have been cut for 25 sectors by between 2 per cent and 10 per cent with with no changes for the other 93 sectors.
The biggest chop of 10.4 per cent is for Sector 11 (which includes the Marina Bay area). Market watchers attribute this to IOI Properties' purchase of the Marina View white site (which has a mandatory hotel component) at a lower-than-expected S$1,379 psf ppr.






