Luxury condo sales hit a high in 2025; what’s behind the buzz and will it continue?
Sales of luxury condos transacted at S$5 million or more rise 55.9% on the year to S$2.6 billion in 2025
[SINGAPORE] A flurry of new projects launched in the prime Core Central Region (CCR) spurred fresh interest in luxury condominiums, where sales of large, prime units rose last year to their highest level since 2023.
The substantial injection of new 99-year leasehold units lifted median prices in the overall CCR market, bringing both older freehold resale properties and ultra-luxury homes into sharp relief, analysts said.
Steep stamp duty hikes introduced in 2023 have continued to keep foreign buyers at bay and curb investment demand.
Nevertheless, the total value of luxury condos (defined as non-landed CCR homes of at least 2,000 square feet (sq ft) in size costing S$5 million or more) rose 55.9 per cent to S$2.6 billion in 2025, from S$1.6 billion in 2024, according to data compiled by Huttons Asia as at Jan 23, 2026.
Huttons’ data showed that the volume of luxury condos sold totalled 294 units last year, up 41.3 per cent from 2024’s 208 units. The 2025 tally was nearly 10 per cent higher than the 270 transactions recorded in 2023, but still some 30 per cent below a 2021 peak of 442 units sold.
According to Huttons, of the 294 luxury homes sold in 2025, 57 were priced at S$10 million or more – about a 67 per cent jump from the 34 transacted at those levels in 2024.
A separate report by Realion (OrangeTee & ETC) Research also indicated that sales of ultra-luxury condos – priced at more than S$10 million – rang in at their highest since 2022, when 72 such units changed hands.
After analysing the prices of CCR apartments of more than 2,000 sq ft which sold for at least S$3,000 per square foot (psf) as a proxy for the luxury segment, CBRE found that median psf prices of luxury apartments moved up by just 4 per cent in 2025. In comparison, the overall CCR median psf price rose 20 per cent.
As a result, the price gaps between luxury homes and the wider CCR market have narrowed to some of their smallest in the last 20 years.
Luxury home prices on a psf basis are now around 25 per cent higher than overall CCR prices, said Tricia Song, CBRE head of research for South-east Asia. In 2006, the median price of luxury condos was between S$3,000 and S$3,500 psf, about 70 per cent higher than CCR prices as a whole, according to CBRE data.
Today, developers marketing new 99-year leasehold launches in the CCR have to tailor and price projects for a predominantly local market, resulting in smaller units and higher psf prices, as Alan Cheong, executive director of research and consultancy at Savills Singapore, pointed out.
With the median price of new CCR units now pitched at more than S$3,000 psf, the threshold for what Savills considers “super luxury” has now moved up from S$3,000 psf to S$4,000 psf.
Meanwhile, CBRE’s Song noted that ultra-luxury homes, such as at The Marq on Paterson Hill, can trade much higher. “Even older but well-maintained projects such as Ardmore Park and Nassim Park Residences have seen their median prices rise above the general luxury market since 2021,” she added.
Professor Qian Wenlan, director of the National University of Singapore’s Institute of Real Estate and Urban Studies, suggested that the ultra-luxury segment is effectively decoupling from the broader CCR market, creating a two-tier market.
Units at “top-tier ‘trophy’ condominiums” such as Park Nova, Skywaters Residences and Sculptura Ardmore transacted at more than S$6,000 psf – roughly double the typical S$3,000 psf of the broader CCR market.
Prof Qian added: “Such a price divergence suggests that ultra-luxury condominiums may now be behaving like a distinct asset class within the CCR itself, given that purchases in this market segment are anchored by high-net-worth buyers focused on wealth preservation and who are less susceptible to policy shifts or the interest-rate environment.”
At the same time, older prime properties are surfacing on buyers’ radars.
At the top end of the market, the median price of new high-rise luxury homes spanning more than 2,500 sq ft in size reached S$4,692 psf in 2025, noted Knight Frank research head Leonard Tay. In comparison, prices of resale properties of the same parameters registered a much lower median of S$2,173 psf.
With new high-end apartments priced at more than double the resale levels, Tay said that buyers can find better value in older CCR projects, where larger family-sized units often trade at a “substantial discount” and can be as affordable as homes in non-prime areas.
Will momentum continue?
Mark Yip, Huttons Asia chief executive officer, observed that the demand for luxury condos was buoyed by a flurry of new project launches last year. These included Kheng Leong’s freehold 21 Anderson; 99-year leasehold Upperhouse at Orchard Boulevard by UOL and Singapore Land; and IOI’s branded residence W Residences Marina View Singapore.
In total, 2,618 new CCR homes hit the market in 2025, compared with 680 units in 2024 and 630 in 2023. Sales totalled 1,915 new units last year, far exceeding the 378 CCR new private homes sold in 2024.
While the CCR came into focus over the year, caveats data showed momentum trailing in the last quarter of 2025. In the fourth quarter, CCR sales volume fell 11 per cent quarter on quarter, said Han Huan Mei, List Sotheby’s International Realty research director.
Overall CCR prices softened in Q4 with a shift in the new launch mix. In the third quarter, sales were anchored by River Green at a median price of S$3,111 psf; The Robertson Opus at S$3,359 psf; and Upperhouse at S$3,277 psf. In Q4, added Han, Skye at Holland was the main sales driver, with a median price of S$2,948 psf.
As a result, median new-sale prices declined 7.4 per cent, and that of resales dipped 1.3 per cent – contributing to a 3.5 per cent quarter-on-quarter drop in the broader CCR price index, she noted.
Overall, CCR prices rose 1.9 per cent for the year in 2025, lagging other regions. The segment was also the only one to see a price decline in Q4 of 3.5 per cent.
The high-end condo market continues to draw interest. In January 2026, a 6,232 sq ft five-bedder at freehold The Marq on Paterson sold for S$37 million or S$5,937 psf. This netted the seller more than S$5 million in profit from its original purchase price of S$31.4 million.
Another two vertically stacked units at the 99-year leasehold Seven Palms Sentosa Cove, totalling 8,794 sq ft, sold for S$23.9 million or S$2,717 psf last month. Both units were bought by Singaporeans.
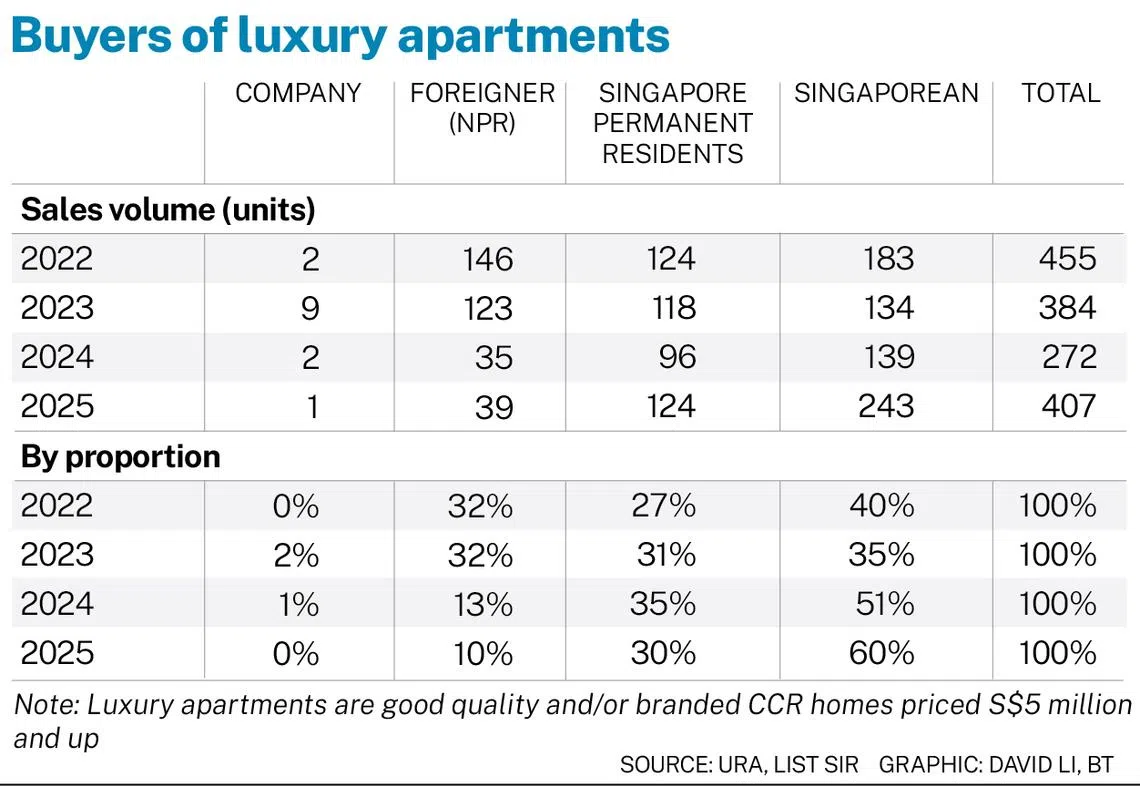
Locals accounted for 60 per cent of buyers in 2025, up from 51 per cent in 2024 and 35 per cent in 2023, according to Han.
Permanent residents (PRs) also returned to the luxury market, purchasing 124 units – similar to the level seen in 2022 before the additional buyer’s stamp duty (ABSD) hike – amid strong economic growth, a firm Singapore dollar and easing interest rates, she noted.
Industry sources suggest that many buyers were newly minted citizens or PRs purchasing their first residential property – a trend likely to persist as foreigners wait to obtain PR or citizenship to avoid hefty stamp duties, Han added.
Mohan Sandrasegeran, head of research and data analytics at Singapore Realtors Inc, said: “Importantly, the rise in (ultra-luxury) transactions occurred alongside stable overall sales volumes and orderly price growth.” In 2025, prices of non-landed CCR homes rose 1.9 per cent even as volumes surged – new sales jumped five times to 1,916 units and resales rose 8 per cent to 2,699 units.
“This suggests that ultra-high-value demand is acting as a supportive layer within the CCR market, rather than a driver of wider pricing momentum,” he added. “Buyers in this segment are typically less leveraged and more insulated from short-term economic fluctuations, which helps anchor price stability and reinforces the resilience of the prime residential market.”
Linda Chern, CBRE head of residential services in Singapore, noted that wider pricing trends did not affect the ultra-luxury market as much, due to tighter stock and ultra-high-net-worth buyers’ willingness to pay for preferred attributes. For example, a 1,798 sq ft Aman-branded ultra-luxury unit was sold for S$11.7 million or S$6,501 psf in October 2025 – a record for a 99-year leasehold property in psf terms.
Upcoming CCR launches include GuocoLand’s River Modern, which is slated to start taking bookings in March; and two projects on state-land sites in Dunearn Road and Holland Link. Together with Newport Residences, these projects will house nearly 1,300 new units.
“Furthermore, Singapore’s ongoing rejuvenation of the Downtown Core into a live-work-play precinct will support luxury buying activity,” said Realion. “New neighbourhoods in prime Newton and Holland will be key growth areas to watch as more land for housing will be released.”
A coveted Newton area site in Bukit Timah Road was sold in November at S$1,820 psf per plot ratio, a much higher-than-expected bid. At that land rate, the project is expected to be priced at an average of around S$3,500 psf.
Still, prime real estate brokers sounded a cautious note, with the 60 per cent ABSD for foreigners still in place.
CBRE’s Chern said: “We do not expect volumes to go back to pre-ABSD regime as the 60 per cent ABSD is still a deterrent for the luxury end of the condo market.”