

Prime London homes are increasingly on the front lines of extreme weather
Air conditioning remains a rarity; more worrying is the city’s flood risk as freak downpours leave a growing number of properties more difficult to insure
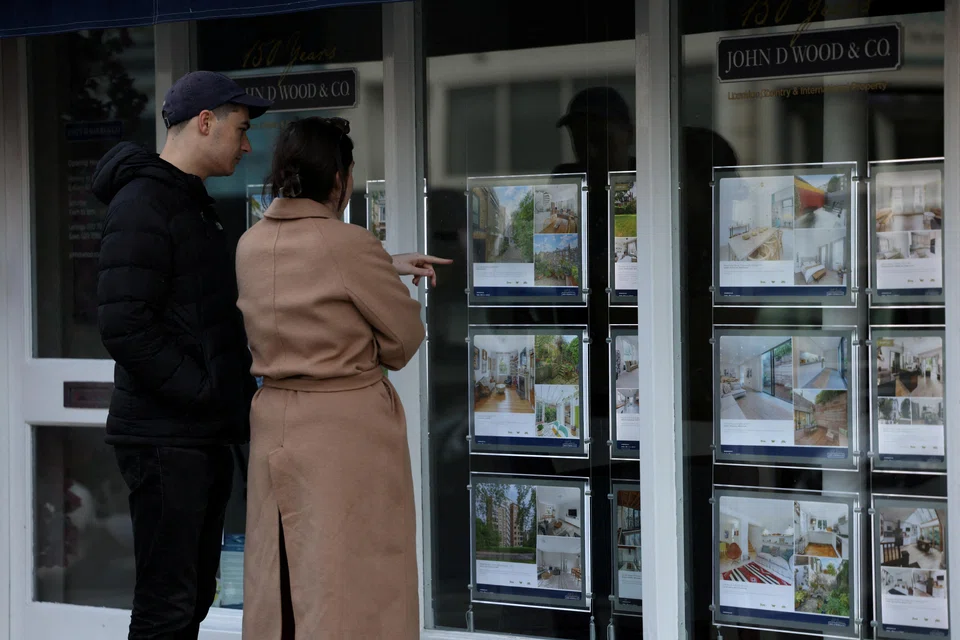
[LONDON] More than a decade into a downturn caused by tax hikes, economic and political shocks, London’s high-end housing market has a new villain to contend with – intractable heat and flood risks.
The assessment comes from Prime Purchase, the branch of Savills UK that represents property buyers in the top end of the real estate market. Guy Meacock, a director at Prime Purchase, said that too many premium homes in the UK capital are ill-equipped to deal with the fallout of increasingly frequent extreme-weather shocks.
“If London gets a reputation for having architecture that’s fundamentally not fit for purpose, then it’s not ludicrous to think that it will have as far-reaching an impact on property values as anything else,” Meacock added in an interview.
The development follows a summer during which London’s vulnerability to extreme heat was laid bare. Air conditioning remains a rarity, existing in less than 10 per cent of properties countrywide. Even basic cooling features such as shutters and awnings have proved hard to get for some of London’s priciest real estate.
More worrying still, perhaps, is the city’s flood risk as freak downpours fuelled by climate change leave a growing number of properties – including those with luxury mega-basements – more difficult to insure.
The concerns add to the list of headwinds facing the UK property market, which is already under pressure from high borrowing costs. Nationwide, house prices fell in August on an annual basis for the first time since 2023, according to the latest figures from Lloyds Banking Group. Savills’ Prime London index is down about 27 per cent since its peak in 2014, amid a cocktail of taxes, political turbulence and economic setbacks.
Heat in particular is growing more relevant for some of London’s priciest boroughs, according to Meacock.
He pointed out that international buyers are deterred not only by the lack of features to protect properties from weather-related risks, but also by what they perceive as fiendishly complex planning rules that would complicate any efforts to upgrade homes.
“We are dealing with a lot of American buyers at the moment and the subject of air conditioning for them comes up every single time,” he said. Buyers are “staggered” to learn how unusual air conditioning is in high-end London homes, so “your pool of potential properties suddenly shrinks”.
Climate change is leaving a significant footprint on the UK capital. The government’s Environment Agency estimated in July that close to 320,000 London-based homes and businesses are now at “high risk” of surface-water flooding.
In August, the office of the Mayor of London warned that extreme heat has become a “major and growing public health threat” in the city, with 86 per cent of Londoners surveyed complaining of overheating in their homes.
“The impact of climate change is having a profound effect on people’s mindset,” Meacock said. “And although it’s not yet having a really material impact on values, that is going to be the likely pathway.”
He noted that London’s so-called golden postcodes, which are in the borough of Kensington and Chelsea, as well as parts of Westminster and its surrounding areas, are particularly vulnerable to shifts in sentiment from international buyers.
With roughly half the buyers investing in such properties coming from outside the UK, sellers “can’t rely purely on domestic wealth, especially not with the current tax climate”, Meacock said.
A major concern is the receding availability of insurance, which is tied to how likely the UK’s insurer of last resort – Flood Re – is to provide a backstop. The state-backed programme applies only to homes built before 2009.
In July, Flood Re unveiled a plan to ensure the programme doesn’t disproportionately favour wealthy home owners, which means commercial insurers with multimillion-pound properties on their books won’t enjoy the same public support they used to. That change is expected to come into force from 2028.
Flats in buildings with more than three properties also don’t qualify for Flood Re. Tracey Garrett, chief executive of the National Flood Forum, a nonprofit that advises homeowners, said that the group’s helpline “often” hears from London residents who can’t get affordable coverage.
“They just manage without flood insurance,” she added. That means they end up covering the cost of flood damage themselves. And even though “they may well be asset rich”, they’re not necessarily “day-to-day wealthy,” Garrett pointed out.
At insurance broker Howden Group, staff are already fielding calls from clients worried they won’t be able to sell high-end properties due to a lack of coverage.
George Seatter, client director at Howden Private Clients, shared that he was called earlier this year by an agent representing the sellers of a £2 million (US$2.6 million) property built in 2019 in Buckinghamshire, west of London. The property’s location close to the river Thames, combined with the fact that it’s not covered by Flood Re, initially left the buyers unable to find insurance.
Commercial insurers “would have mapped the property, they’d have seen that it was in a perceived high-risk area for flood”, Seatter said. “They’d have looked at the fact that it was going to be a second home and built after 2009. They’d have known that they couldn’t cede it to Flood Re, and that would’ve been the end of the conversation.”
In the event, Seatter said that Howden was able to arrange a policy backed by a US insurer. Howden’s analysis of the site found that its precise location in relation to the river wasn’t a disqualifying risk. Seatter added that insurers who invest in more detailed analyses are picking up business from competitors spooked by the broader trend.
“From a flood risk perspective, we’re doing this all the time,” he said. “There are more and more properties that are in flood-affected areas,” and as an insurer, if “you can then remove it from your books, so to speak, and you can pass on the cost to the client, almost, why wouldn’t you?” BLOOMBERG
Decoding Asia newsletter: your guide to navigating Asia in a new global order. Sign up here to get Decoding Asia newsletter. Delivered to your inbox. Free.
Share with us your feedback on BT's products and services
TRENDING NOW

8 public officers referred to police over property buys near unannounced MRT stations: Chan Chun Sing

Grab CEO’s wife Chloe Tong on life with Anthony Tan and finding her purpose
Retrenched PMETs who return on lower pay see median 25% wage cut
Hao Mart owner resisting OG’s mortgage foreclosure on his Tanglin GCB

