

Tough restrictions aside, HDB Plus and Prime BTO flats are good buys
Such homes are attractive for living and investing, and they keep the system fair for all
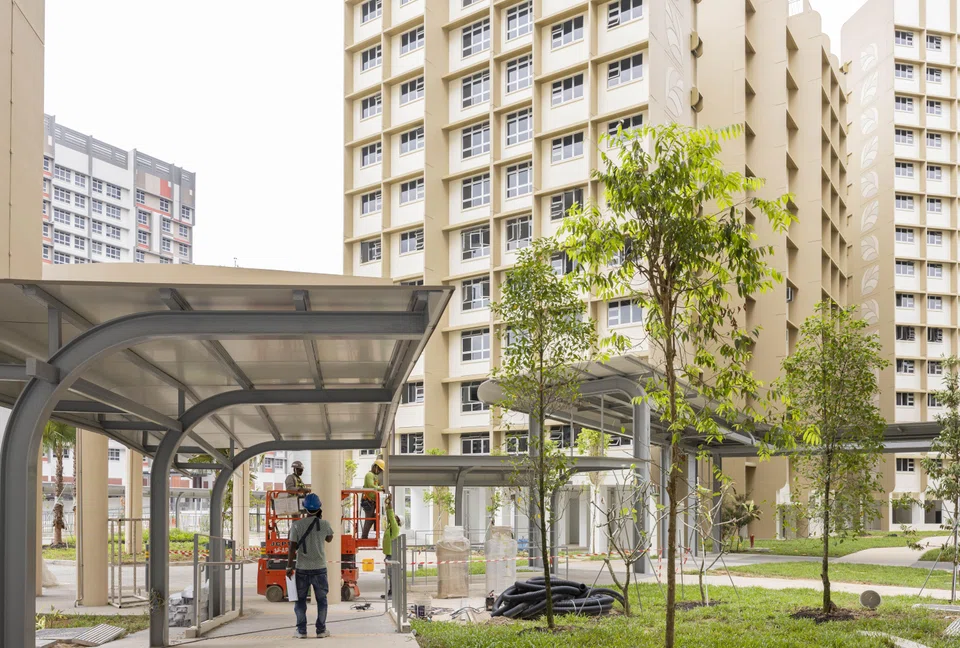
MANY Singaporeans have built wealth from buying new Housing and Development Board (HDB) flats at subsidised prices. Will this proven wealth creation method still work if one purchases a flat with tighter restrictions under the new HDB framework?
New HDB Build-To-Order (BTO) projects starting with the October BTO exercise – where HDB will offer 8,573 flats across 15 projects – sees flats classified as Prime, Plus or Standard. In this exercise, there are 4,988 Standard flats in seven projects, 3,273 Plus flats in seven projects and 312 Prime flats in one project.
Prime flats will be in the choicest locations. Plus flats will be in choicer locations such as being near good transport connectivity and amenities.
BTO buyers of various flat types enjoy significant market discounts. In addition, buyers of Plus flats will receive more subsidies and buyers of Prime flats will get the most subsidies.
In turn, buyers of Plus flats will be subject to tighter conditions while those of Prime flats face the tightest conditions.
BTO buyers of Plus and Prime flats will pay part of the resale price of the flat to the HDB if they sell their flats. The clawback will be smaller for Plus flats versus Prime flats.
Buyers of Plus and Prime flats will be subject to a minimum occupation period (MOP) of 10 years versus five years for Standard flats. Reselling the HDB home and buying a private home are allowed after the MOP.
Owners of Plus and Prime flats cannot rent out their entire flat at any time. And at least one buyer of a resale Plus or Prime flat has to be Singaporean. Also, a couple buying a resale Plus or Prime flat must meet the BTO monthly household income ceiling, which is currently S$14,000.
This new HDB framework aims to keep flats affordable to all income groups, maintain a good social mix in every town and region, and keep the system fair for all.
Despite tough restrictions that apply to buyers of BTO Plus and Prime flats, BTO applicants should embrace such flats.
Sound financial returns
One, applying an income ceiling to resale buyers of Plus and Prime flats may not constrain the prices that resale Plus and Prime flats can fetch.
A young couple earning S$168,000 annually or S$14,000 a month may struggle to pay over S$1 million for a choice resale HDB home, which is six times or more of their annual income. However, the said couple’s affordability rises if they receive parental help to purchase a home.
Moreover, the BTO household income ceiling has been raised periodically. Possible increases in the income ceiling might grow the pool and buying power of resale Plus and Prime flat buyers.
Crucially, resale Plus and Prime flats may draw local retirees, who could be funding their purchases from selling say a private home or a highly sought-after HDB home. A wait-out period applies to private homeowners looking to buy resale Plus and Prime flats.
As at end-June, close to half a million Singapore citizens were aged 45-54, accounting for over 13 per cent of the citizen population. Many people within this cohort may start retiring in about 15 years time when initial batches of Plus and Prime flats could hit the resale market post MOP.
Two, while a BTO buyer of a Plus or Prime flat has to forgo part of the resale proceeds upon selling the said home, such flats are bought with higher subsidies and in good locations. Thus, one should still achieve robust financial returns from buying a BTO Plus or Prime flat.
Take a buyer of a 99-year leasehold four-room BTO Plus flat. Assume purchase price is S$550,000 and the mark-to-market price is 45 per cent higher. Apply annual price escalation of 3.5 per cent over 15 years.
After 15 years, the said flat can be sold for a profit on purchase price excluding transaction costs of about S$719,000, after accounting for clawback of say 5 per cent of sales proceeds. This translates to a simple average annual gain of about 8.7 per cent.
In perspective, based on the Q3 flash estimate, the HDB resale price index rose 7.9 per year on year and the compound annual growth rate was 3.3 per cent between Q3 2014 and Q3 2024.
Additionally, resale Plus and Prime flats will be competitive versus resale units at coveted HDB developments with much lighter restrictions such as Pinnacle@Duxton in Tanjong Pagar and SkyVille@Dawson in Queenstown as the former will be much newer and have far longer remaining land leases.
Three, many buyers greatly value buying a home that is good for living. An owner of a Plus or Prime flat gets to live in a desirable location, where one can commute to the city for work or bring kids around for various activities easily using public transport.
The restriction on renting out an entire flat might hardly matter to a homeowner. An owner-occupier of a four-room or five-room flat may be happy with being able to rent out a room post-MOP.
As many local households occupy their HDB homes for over 10 years, a lengthy MOP should be manageable. In addition, there can be flexibility for owners who, due to certain circumstances, may need to sell their homes ahead of MOP.
Upgrading path
Four, young couples buying BTO Plus and Prime flats can still upgrade to a private home. Take a couple who move into an owned BTO Plus or Prime flat in their early 30s. They can sell their HDB unit and buy a condo when they are in their early to mid 40s. They could be switching from public to private housing when they have built up substantial savings through career progression and are entering their peak earning years.
A lower loan-to-value limit for a housing loan that extends beyond the borrower’s age of 65 years may be inconsequential. Moreover, the 40-plus-year-old couple might splurge on a condo because they expect to be economically active for many more years amid rising labour force participation among those over 60 years old.
Building wealth through homeownership can be slightly harder under the new HDB framework. Still, successful applicants for BTO Plus and Prime flats will secure a good home to live in and a sound investment.
TRENDING NOW

Once staunchly pro-China, Malaysian Chinese businesses are now distancing themselves from Beijing
Britain’s mansion tax shows the difficulty of targeting wealth
Three hats, one goal: How Ng Kian Swan runs sustainability at NUHS
COE review: The gap between luxury and mass-market cars isn’t the only one worth bridging

