

Singapore private home prices up 0.9% in Q3, less than earlier estimated
Overall sales volume surges 44%, with 7,404 units transacted
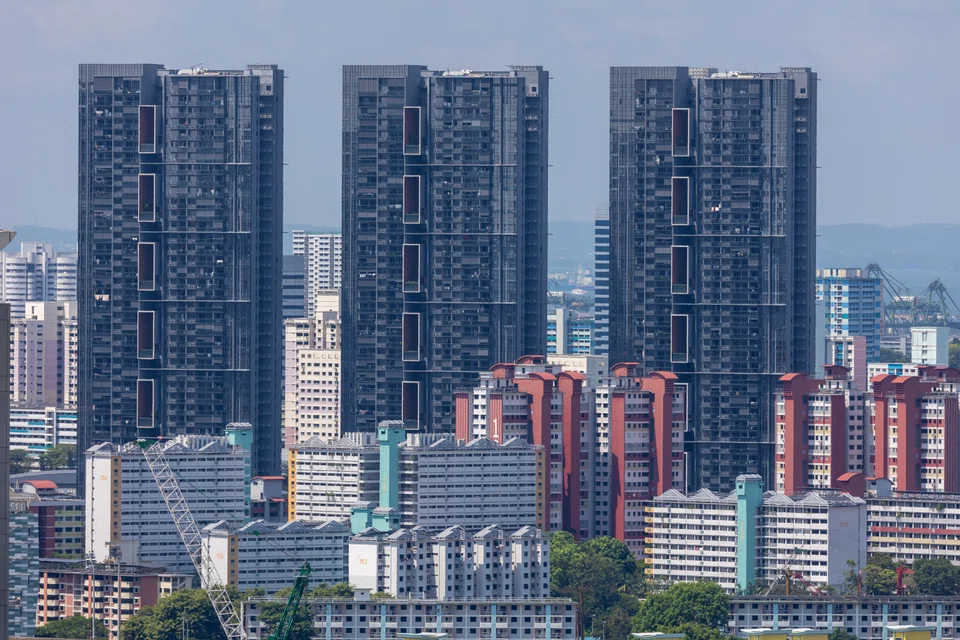
[SINGAPORE] Prices of private residential properties rose 0.9 per cent in the third quarter of 2025, slowing slightly from a 1 per cent gain in the previous quarter, even as transaction volume surged on robust sales at new launches.
The 0.9 per cent gain in the private residential property price index for Q3 was also lower than the government’s earlier flash estimate issued on Oct 1, which had put the overall price gain at 1.2 per cent.
Overall sales volume grew 44 per cent with 7,404 units transacted in Q3, up from 5,128 in Q2.
Gains in the price index during the quarter were led by landed homes, where prices rose 1.4 per cent, less than their 2.2 per cent growth in Q2. Strong sales at new condo launches in Q3, including several projects in the city centre, also steered price movements.
In the non-landed segment, prices rose the most in the Core Central Region (CCR), rising 1.7 per cent in Q3 but slowing from their 3 per cent gain in the previous quarter. Over three quarters, CCR home prices have climbed a cumulative 5.6 per cent, outpacing prices in other regions, PropNex noted.
In the city fringe Rest of Central Region (RCR), home prices crept up 0.3 per cent, reversing from a 1.1 per cent decline in Q2. In the suburban Outside Central Region (OCR), prices were up 0.8 per cent, compared with a 1.1 per cent increase in Q2.
Prices at some new launches may be plateauing, said Alan Cheong, executive director for research and consultancy at Savills Singapore.
For instance, Faber Residence in Clementi sold 86 per cent of its units at an average launch price of S$2,160 per square foot (psf) last weekend, which is “in line with recent OCR launches”, Cheong said.
He added: “The significant revision downwards of the property price index, from 1.2 per cent during flash estimates to 0.9 per cent at the end of Q3, could be hinting that the price increase is beginning to decelerate further. While buying momentum remains strong, this could be a lagging indicator.”
In the first three quarters of 2025, overall prices have risen 2.7 per cent. In 2024, prices rose 3.9 per cent, slowing from the 6.8 per cent increase in 2023.
While a steep 60 per cent additional buyer’s stamp duty continues to deter non-resident foreign buying, new citizens and permanent residents have been acquiring homes in a stable Singapore against a destabilising global environment, observed Knight Frank Singapore head of research Leonard Tay.
According to latest available population data from the Department of Statistics, there were 22,766 new citizens and 35,264 new PRs in Singapore in 2024, he noted.
The CCR saw the strongest rebound in demand, with 903 new homes sold, the highest in volume since Q4 2010 when 994 units transacted, said Marcus Chu, ERA Singapore’s chief executive officer.
In Q3, River Green sold 89 per cent of its 524 units at an average of S$3,111 psf, while Upperhouse at Orchard Boulevard moved 67 per cent of its 301 units at a median price of S$3,277 psf, based on data from CBRE.
While the CCR has led growth in prices in 2025, it is still playing catch-up, CBRE’s head of research for South-east Asia, Tricia Song, said.
Prices in the region are up 26 per cent from the Covid-19 trough, while prices in the RCR have risen 50 per cent since then, she said. In the OCR, prices are up 48 per cent since bottoming out during Covid-19.
Developers launched 4,191 units for sale in Q3, almost three times the 1,520 units put up for sale in the preceding quarter. They sold 3,288 units, up from the 1,212 units sold in Q2.
As a result, unsold inventory of uncompleted private homes, excluding executive condominiums (ECs), fell 7.9 per cent to 17,029 units in Q3. Including completed units, unsold inventory was down to 17,209 units.
“This is the lowest unsold stock in seven quarters,” noted Kelvin Fong, CEO of PropNex, adding that it was manageable and could be absorbed by the market in about two years.
In the EC market, one project, the 600-unit Otto Place, was launched for sale in Q3. For the quarter, developers sold 571 EC units, compared with 149 ECs in Q2.
Compared to Q2, resale transactions accounted for a lower proportion of all sales in Q3. There were 3,881 secondary market sales in the quarter, down slightly from the 3,647 units changing hands in Q2. These deals accounted for 52.4 per cent of all sales in Q3, a smaller proportion than the 71.1 per cent in Q2.
Sub-sale volume also fell. There were 235 such transactions recorded in Q3, fewer than the 269 units in Q2. Sub-sales were also down as a proportion of sales at 3.2 per cent, compared with 5.2 per cent in the previous quarter.
In the rental market, URA data showed that rents of private homes rose 1.2 per cent in Q3, after increasing 0.8 per cent in Q2. The vacancy rate inched down to 6.9 per cent as at end-Q3, from 7.1 per cent in Q2.
With a cumulative 2.4 per cent increase in rents in the first nine months of 2025, rents have reversed from the 1.9 per cent correction in 2024, CBRE’s Song said.
“However, (rental) growth in Q3 continues to be rather mixed, largely supported by the landed segment and higher non-landed OCR and RCR rents, while CCR rents posted a decline,” she added.
Christine Sun, chief researcher and strategist of Realion (OrangeTee & ETC) Group, said: “The private rental market may continue to face headwinds, as companies maintain prudent business expansion plans and cautious hiring outlook amid the ongoing global economic uncertainty...
“Although (the) unemployment rate remains low in Singapore, hiring trends are uneven across sectors, with the health and social services experiencing growth, while job cuts (are) occurring in specific professional services and information and communications.”
Knight Frank’s Tay said: “Despite the low vacancy rates, landlords are growing wary and defensive, and are increasingly focused on keeping their units occupied in the near future.”
In the last quarter of the year, 1,144 private homes, including ECs, are expected to be completed.
Another 7,878 units are expected to be completed in 2026, 10,219 units in 2027 and 10,795 units in 2028. Beyond that, some 24,038 units are expected to be completed.
With recent new project launches racking up firm sales, market watchers expect new sales volume for 2025 to exceed 10,000 units, which would be the highest developers’ sales recorded since 13,027 new homes were sold in 2021.
Market sentiment could also be buoyed by easing borrowing costs. Realion’s Sun said: “With mortgage rates falling further, housing affordability and investor confidence are likely to improve, supporting continued buying activity.”
PropNex’s Fong said: “We believe sensitive pricing and a focus on keeping price quantum affordable continues to be a driving force of demand.”
TRENDING NOW

Three ex-employees of Envy group join Ng Yu Zhi in bankruptcy

He built the Vingroup empire. Now South-east Asia’s richest man is handing some key roles to his sons

Grab CEO’s wife Chloe Tong on life with Anthony Tan and finding her purpose

Incidence of civil servants buying property near unannounced MRT stations ‘a concern’, but may not establish misconduct: PSD

