

Singapore private home prices flatten further, up 0.5% in Q2
This follows a 0.8% increase in Q1 and a 40% drop in transaction volumes in Q2
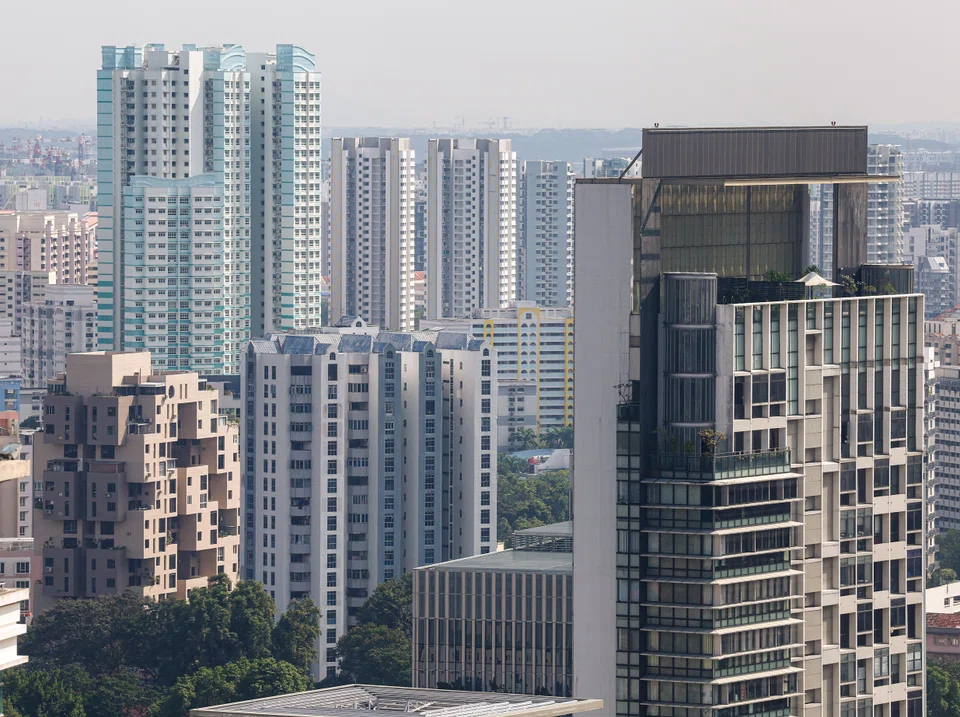
[SINGAPORE] The price growth of private homes in Singapore eased in the second quarter of 2025, up 0.5 per cent over the previous three months, flash estimates released by the Urban Redevelopment Authority (URA) showed on Tuesday (Jul 1).
This follows a 0.8 per cent increase in Q1, and a 2.3 per cent rise in the fourth quarter of last year.
For the first half of 2025, private home prices grew 1.3 per cent, slowing from the 2.3 per cent increase recorded in the same period last year. This reflects a broader marketwide stabilisation of prices, said Leonard Tay, Knight Frank’s head of research.
Sales volume, on the other hand, fell 40 per cent in Q2 to 4,340, from 7,261 in the previous quarter. Year on year, transaction volume fell some 12 per cent.
Q2 prices were likely weighed down by weaker sales and a limited number of new launches in the period, said PropNex chief executive officer Ismail Gafoor. There were just three launches in April, none in May, and two in June.
The five projects yielded 1,526 units in total, compared with the 3,251 units from six projects marketed in Q1, he noted. “Furthermore, some of the projects launched in Q1 2025 have set new benchmark prices at their respective locales, which had helped to prop up prices in the previous quarter.”
Tricia Song, CBRE research head for South-east Asia, added that buying sentiment had turned cautious in the quarter, despite lower interest rates. This was due primarily to trade frictions and geopolitical tensions, which dampened Singapore’s economic outlook and could have led to developers holding back their launches, she said.
The nation was also preoccupied with the general election in May, and local buyers were likely abroad during the June holidays, said Christine Sun, chief researcher and strategist at Realion Group.
Based on flash estimates, prices of non-landed private residential properties rose by a marginal 0.5 per cent quarter on quarter, after rising 1 per cent in the prior quarter.
By region, the price change of non-landed homes was mixed in Q2, with the prime Core Central Region (CCR) registering the biggest increase of 2.3 per cent, compared with the 0.8 per cent growth previously.
In the suburbs or Outside Central Region (OCR), prices inched up 0.9 per cent, from a 0.3 per cent increase in the preceding three months. Meanwhile, prices in the city fringe or Rest of Central Region (RCR) fell 1.1 per cent, swinging from a 1.7 per cent increase in Q1.
Wong Xian Yang, Cushman & Wakefield research head for South-east Asia, views the decline in RCR prices as a temporary fluctuation – stemming from the specific mix of units sold during the quarter – rather than “an indication of waning demand for RCR properties”.
He added that the CCR’s strong performance in Q2 followed years of lagging prices, and could signal even further growth ahead. On a year-to-date basis, prices of non-landed CCR homes were up 3.1 per cent, against the 0.6 per cent increase in the RCR and 1.2 per cent in the OCR.
“Nonetheless, current cooling measures would likely cap any sharp increase in price growth,” he said.
Mohan Sandrasegeran, head of research and data analytics at SRI, noted that even with the easing of price growth for non-landed private homes, demand for luxury homes remained resilient.
At least nine new non-landed private homes were sold for more than S$10 million, compared with six of such transactions in Q1, he said. “(This) reflects the appeal of newly launched premium projects and the scarcity of luxury homes in the prime district, which helped to anchor values at the top end of the market.”
Meanwhile, prices of landed homes rose 0.7 per cent quarter on quarter in Q2, up from a 0.4 per cent increase previously.
Knight Frank’s Tay expects activity in the landed and Good Class Bungalow markets to remain selective in the remaining months of the year. “Nevertheless, as buyers’ expectations recalibrate to more realistic levels, from more expensive locations to neighbourhoods where prices are within budgets, there could be more activity in the second half of 2025.”
In the non-landed segment, ERA chief executive officer Marcus Chu said there may be up to 4,154 homes launched across nine developments in Q3.
Four of these projects are located in the CCR, following a quiet pipeline in recent years, he noted. “That said, new home sales in the CCR are still likely to progress at a more measured pace given their higher price point. Therefore, we expect the bulk of new home sales in Q3 to still come from upcoming RCR and OCR launches.”
Gafoor from PropNex added that buyers’ “fear of missing out” may not be as strong in the rest of this year, but he believes that they will still enter the market if upcoming projects offer a strong value proposition with potential upside in the future.
“To this end, we anticipate developers will be more sensitive with their pricing at the initial stages of a project launch, if they wish to get sales off to a good start,” he said.
Wong of Cushman & Wakefield said that overall, sales volume could come in between 19,000 and 23,000 units, with prices growing by around 2 to 3 per cent for the entire year. Developers will continue to be selective and focus “on sites in areas with established market demand”, he added.
TRENDING NOW

Who is Leo KoGuan, the Singapore-based billionaire backing Nvidia’s Jensen Huang?

Demand, tech capabilities position Apac and AI as Skyscanner’s next growth frontiers: CEO Bryan Batista

Higher rates, weaker spending: Is the Philippines entering stagflation?

South-east Asia has lost Nvidia’s best salesman

