

Is Singapore’s co-living market still a good investment?
The sector continues to attract investor interest, but analysts say demand is easing in the highly saturated space
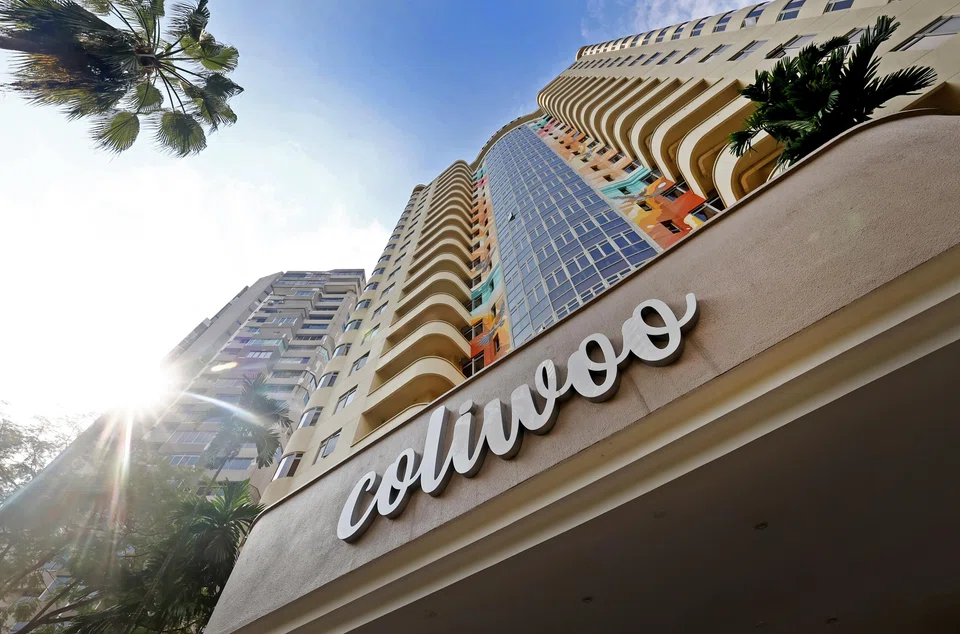
[SINGAPORE] Once a niche alternative to traditional rentals, co-living in Singapore has drawn serious attention since the pandemic – from local operators, developers and hospitality players, and private equity investors.
While the market has evolved – demand is moderating in an increasingly crowded landscape – analysts reckon that its investment potential remains generally strong.
The outlook bodes well for major co-living market players like LHN Group, which aggressively expanded its footprint over the last few years, sweeping up assets in a growing market.
Most recently in April, it announced plans to take its co-living business, Coliwoo Group, public on the Singapore Exchange (SGX). The group said it has submitted applications to SGX and the Hong Kong Stock Exchange for the proposed spinoff, and to separate the listing of Coliwoo shares on the mainboard of SGX.
LHN added that the proposal was at an early stage, and there is no assurance that the plan would materialise. If the spinoff is successful, it expects to continue holding a majority shareholding in Coliwoo, which will be consolidated within LHN.
The group declined further comment on the proposed initial public offering and its future business plans. While it has opened new properties, it also put three of its freehold co-living properties up for sale last year at S$120 million. The Business Times understands the sale received interest and parties are in preliminary confidential discussions.
Paul Chew, head of research at Phillip Securities Research, believes that the move to spin off the Coliwoo business is an effort to narrow LHN’s current 23 per cent discount to its book value of around 61 Singapore cents.
On the other hand, Coliwoo could trade at a premium to its book value, given its faster growth and the scarcity of pure-play co-living operators in the market, he said.
“LHN shareholders can benefit from the listing, either from special dividends or distribution in specie of the Coliwoo shares,” said Chew.
Lim & Tan Securities analyst Chan En Jie expects LHN’s other business segments to remain resilient, especially with the group’s growing focus on the property development and energy segments.
Chan added that LHN made a similar move back in 2022, with the spin off and listing of its logistics arm LHN Logistics.
This enabled the group to unlock value, said Chan, and subsequently led to a privatisation offer for LHN Logistics a year later by an external party at S$0.2266 a share – up from its initial public offering of S$0.20 a share.
A market report by property consultancy CBRE, published last September, pointed to strong investment potential for Singapore’s co-living market.
This comes from the city-state drawing an influx of foreign expatriates and students, with some 30 per cent of the country’s population being classified as “non-residents”. This group – particularly working professionals with S Passes or Employment Passes – has historically driven demand for rental housing, said CBRE.
“While many still rent private or public apartments, more are turning to co-living options following a 50 per cent growth in rents from 2021 to 2023. Co-living also offers flexibility and community elements,” it said. The high prices of private residential properties make co-living an affordable option as well.
Overall, co-living occupancy rates remain healthy, exceeding 90 per cent, said Cushman & Wakefield head of research Wong Xian Yang.
These factors have made the co-living market an investor magnet. They are targets for mergers and acquisitions among key players seeking to expand their share, and private equity players are entering the fray.
A 2023 report by JLL noted around 20 active co-living players and more than 9,000 units across Singapore. But three companies – Coliwoo, The Assembly Place and Bespoke Habitat – accounted for nearly half the supply of co-living units.
Warburg Pincus-backed Weave Living partnered with BlackRock in February 2024 to purchase serviced-apartment complex Citadines Mount Sophia. It has since been redeveloped into the 175-unit Weave Suites-Hillside, which opened in March.
Knight Frank capital markets senior director Melvin Chay noted that such operators with established platforms and investor support are better positioned to grow through acquisitions, and to move quickly when new opportunities arise.
Still, analysts noted that demand for co-living has moderated since the pandemic boom.
Tricia Song, CBRE head of research for South-east Asia, said that the trend among young singles moving out and renting units may have slowed from the peak pandemic period, now that return-to-office work arrangements are being normalised.
The completion of Build-To-Order projects, delayed during the pandemic, has also enabled couples who were renting in the interim to move into their new homes, she noted.
She added that a weaker and more uncertain global economic outlook has slowed down hiring and demand for expats, and raised retrenchments in certain sectors. “The correction in private home rents in 2024 could have also prompted some co-living tenants who were deterred by the high rents previously to switch to conventional leases.”
Catherine He, research head at Colliers Singapore, pointed out that the market may have reached saturation, given the general slowdown in the opening of new co-living locations.
Nonetheless, CBRE’s Song said that the market’s supply dynamics are still conducive to operators, with demand “structurally higher” than during the pre-pandemic days.
In the near term, just 5,847 private homes are expected to be completed this year – 31 per cent lower than 2024’s 8,460 units. “In the longer term, lower investment demand for new homes from the multiple rounds of cooling measures since 2018 has resulted in a structurally tighter supply of private rental units, which would support the co-living market,” said Song.
Co-living operators with a proven track record could attract investors with their ability to maintain rents and occupancy, even as more targeted offerings can provide a more stable and resilient operating income, said He of Colliers.
Moreover, the co-living is space more attractive than traditional residential rentals, in that it offers higher yields and flexibility to adjust rents because of the shorter leases, she added.






