

Wee Hur looks beyond construction and real estate to drive future growth
WEE Hur Holdings’ roots may lie in the construction industry, but the mainboard-listed company has quickly made a name for itself in other sectors, from property development and student housing to fund management.
This diversification has proven successful, with income growing steadily year on year.
In its latest financial year ended December 2023, revenue was up 4.1 per cent year on year to S$224.8 million. Net profit grew 45.1 per cent year on year to S$98.6 million.
Compared with the pre-pandemic 2019 financial year, revenue rose 17.2 per cent from S$191.8 million and net profit nearly trebled from S$34.6 million.
In 2022, Wee Hur Holdings also sold a 49.9 per cent stake in its Australian-focused purpose-built student accommodation (PBSA) fund for A$567.9 million (S$573.6 million). The buyer, Reco Weather, was a Singapore-based investment holding company linked to state investment firm GIC.
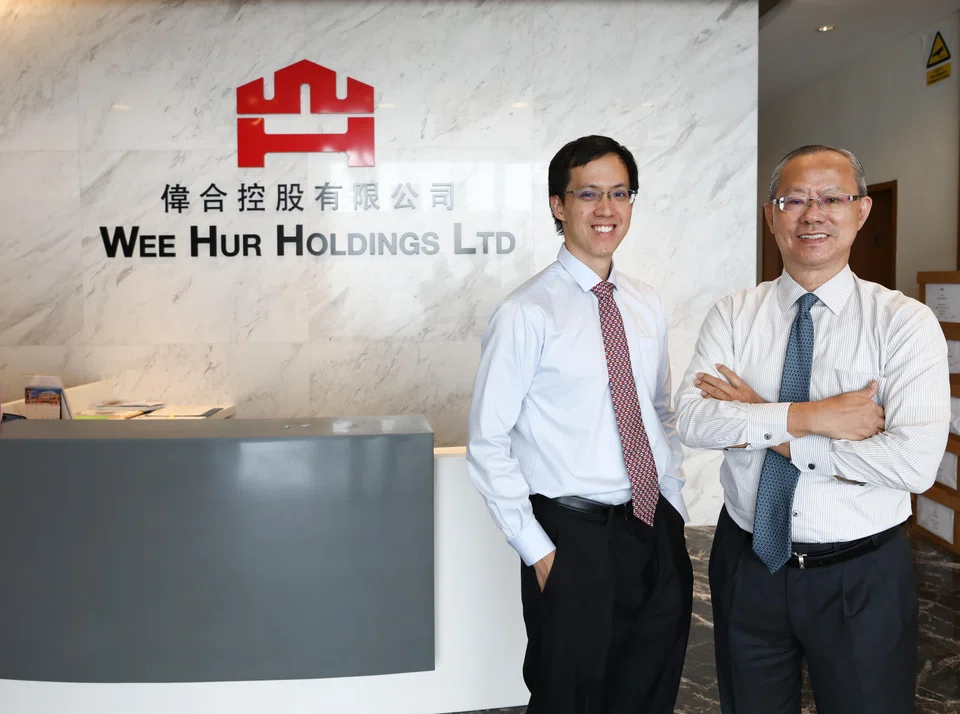
Goh Wee Ping, chief executive officer of Wee Hur Capital, the group’s fund management arm, said that sealing that deal was his biggest milestone yet. “It was the (feat) that crystallised my achievement in the family business,” he told The Business Times.
Goh, who is also chief investment officer at Wee Hur Holdings, is one of the second-generation leaders running the company. It was founded as a construction company in 1980 by his father – executive chairman and managing director Goh Yeow Lian – together with three brothers and two brothers-in-law.
Since then, Wee Hur Holdings has evolved significantly from its construction roots.
The two segments that now hold the most value for the group are probably its PBSA and workers’ dormitory businesses, said Goh Wee Ping.
In FY2023, the PBSA segment accounted for S$124.3 million of the group’s profit before tax, while S$73.7 million came from the workers’ dormitory segment. The group’s property development segment in Singapore raked in significantly less at S$13 million, while its building construction segment made a loss of S$21.1 million.
Goh highlighted that there is also great growth potential in the group’s fund management and investment businesses.
Wee Hur still holds a 50.1 per cent stake in the PBSA fund, which was first established in December 2016. The aim then was to develop a portfolio of up to 5,000 beds in Australia’s major cities. The portfolio now consists of over 5,600 beds across seven student housing properties in Sydney, Melbourne, Brisbane, Adelaide and Canberra.
At the same time, Wee Hur has invested in around 10 venture capital funds and made direct investments into 14 startups across the globe. This includes startups such as Zookal, which operates in the education technology space; Queensland-based Jet Zero Australia, which focuses on sustainable aviation; and local smart-sensor-systems startup WaveScan.
Unlike starting an entirely new operating business – which requires considerable time and work in developing an effective business strategy – Goh noted that investing is more passive, leaving the execution to others.
“If it grows into something quite substantial, we may then (consider) a merger or acquisition, and it becomes another operating business,” he explained. “If not, it stays as it is, as just another investment we put money into then exit after a few years.”
Branching out
The group’s diversification is also helpful given that it has not been the easiest of times for construction companies or property developers, said Goh.
For one, he pointed out that construction costs remain high post-pandemic, eating into profit margins.
Sentiment in Singapore’s residential market continues to be weak amid the current high-rate environment, he added. In 2023, for instance, new private home sales fell to their lowest level in 15 years with just 6,452 units sold. This trend seems to have dragged on in 2024, with monthly sales in February dropping to 149 units – 47 per cent lower than the 281 units moved in January, and about a third of the 433 units sold in February 2023.
“This is really not the time to be aggressive (as a property developer),” said Goh. “Once you commit to a development, and if you get caught in the wrong part of the market cycle, it can be very painful.”
While the PBSA and workers’ dormitory segments remain “good businesses”, Goh highlighted that opportunities are not always available. “A lot of institutional (investors) that I speak to all have approval to invest in Australia and student accommodation, but no one can find the opportunity to do so.”
Goh also sees the group’s diversification into fund management as a natural progression for the company as it climbs the value chain.
Although branching out can be challenging, Goh believes that this entrepreneurial spirit – of looking beyond their niche, and leading with curiosity and an open mind – is key to propelling and sustaining Wee Hur’s growth.
For instance, said Goh, had Wee Hur not expanded into property development in 2009 and the workers’ dormitory business in 2013, it would be in a very different position today. The pandemic was the nail in the coffin for many in the construction industry, and the group could well have been among the casualties.
“In the next 20 years, I think we will encounter another shift in…how we grow the platform,” said Goh. “It is about balancing between the operating business and a bunch of other investments. I think that’s the direction (we’re heading towards). I don’t think we will forever be so concentrated in real estate.”
He added: “We will make use of what we learned so it hopefully doesn’t take another 15 years to double or triple where we are.”






