

Ascott Residence Trust almost doubles H1 DPS to 2.05 S cents despite 11% revenue drop
CAPITALAND subsidiary Ascott Residence Trust (ART) HMN on Tuesday reported a 95 per cent increase in its distribution per stapled security (DPS) to 2.05 Singapore cents for the first-half ended June 30, from 1.05 cents for the year-ago period.
However, the increase was mainly due to one-off gains in distributable income.
Revenue fell 11 per cent to S$185 million, on the back of a S$13.1 million decline in revenue from the divestment of six properties. Further, a S$14 million drop in revenue was recorded from its existing portfolio from the impact of the ongoing Covid-19 pandemic.
These losses were offset partially by a S$3.6 million contribution from the acquisition of Paloma West Midtown in February this year, three rental housing properties in Japan in June this year, and a full half-year contribution from Quest Macquarie Park Sydney, acquired in February last year.
Gross profit shrank by 7 per cent to S$82.1 million, as lower operating costs mitigated the softer revenue.
In a results briefing on Tuesday morning, chief executive officer of the managers Beh Siew Kim noted that the year-on-year decline in H1 2021 results was mainly due to the absence of significant impact from Covid-19 in Q1 last year.
She highlighted that, on a same-store basis excluding acquisitions and divestments in 2020 and 2021, revenue and gross profit were 45 per cent and 56 per cent higher respectively in Q2 2021, compared with the year-ago period.
"We're seeing more enquiries on corporate bookings in Q2," Ms Beh said. "Compared to pre-Covid, we're not there yet. But there's definitely an improvement."
"As governments around the world step up their vaccination programmes amid emerging variants of Covid-19 and start to ease restrictions on international travel, we are cautiously optimistic of the varied pace of recovery across global markets," she added. "Things are slowly coming back."
ART's distributable income jumped 96 per cent to S$63.8 million in H1 2021, largely attributable to a distribution top-up of S$20 million. The managers of the stapled hospitality group said the top-up was to share divestment gains with stapled securityholders, replace income loss from divested assets, and mitigate the impact of Covid-19 on distributions.
DPS was also boosted by income received from the termination of the sale of two Citadines assets ART holds in Xinghai Suzhou and Zhuankou Wuha as well as realised exchange gains from the divestment proceeds and repayment of foreign currency bank loans.
For the first half of the year, the managers of ART said it will be paying out 2.045 cents per stapled security on Aug 27, 2021.
Looking ahead, the managers said another top-up in distribution income is "likely" in H2 amid a protracted recovery from the Covid-19 pandemic.
"We're not really out of the woods yet in terms of international travel," Ms Beh said. "[But] we're on the road to recovery ... (and) we're getting there."
For now, ART is looking to shore up segments that are more resilient against pandemic-led headwinds.
For example, the managers aim to expand ART's asset allocation in rental housing and student accommodation properties, from about 9 per cent currently to around 15 to 20 per cent of its portfolio value.
"The three Japan rental housing properties we acquired in June 2021 will immediately contribute stable income, given their long leases of about two years and high occupancy rates. The average EBITDA yield of the three rental housing properties is approximately 4 per cent," Ms Beh said.
Meanwhile, the purpose-built student accommodation (PBSA) segment has also "proven to be a very resilient asset class", she added.
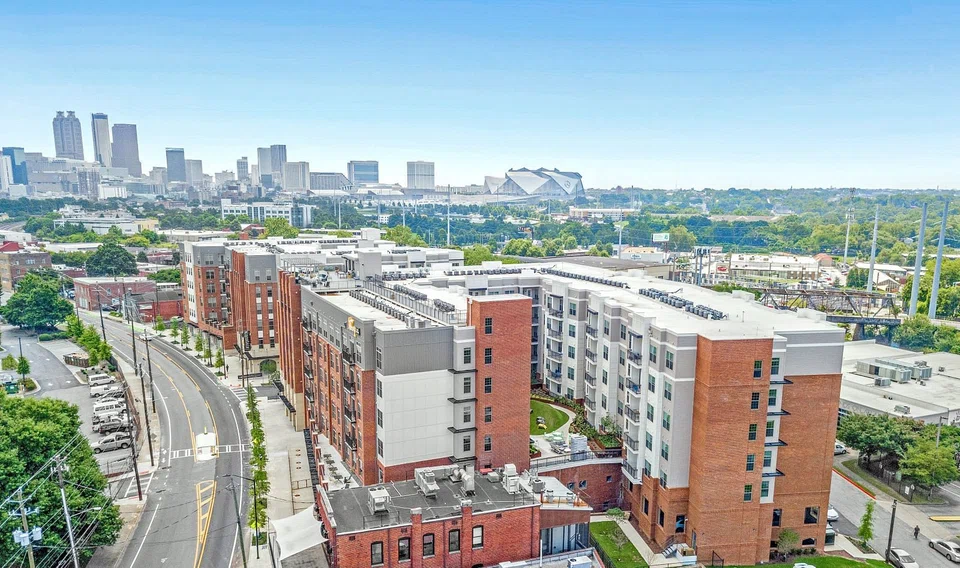
ART in June announced it will jointly invest and develop a 678-bed freehold student accommodation asset in South Carolina for US$109.9 million with its sponsor, The Ascott. The student housing asset - ART's second in the US after its acquisition of Paloma West Midtown in Georgia in February - has a net rentable area of 232,748 square feet and will be completed in Q2 2023.
The managers on Tuesday said it is currently focusing on PBSA assets in the US, but does not rule out exploring student accommodation assets in the UK and Australia "when the time is right".
According to the managers, ART's "stable income sources" - which include master leases, management contracts with minimum guaranteed income, and rental housing and student accommodation properties - contributed approximately 74 per cent of its gross profit in H1 2021. There are no master leases expiring in 2021.
"With about S$140 million remaining in divestment proceeds and a debt headroom of S$1.9 billion, ART has a strong financial capacity to seek investment opportunities in more long-stay lodging assets to deliver sustainable, long-term value to our stapled securityholders," said Bob Tan, chairman of the managers.
ART's stapled securities closed 1.98 per cent or S$0.02 higher at S$1.03 on Tuesday.
Amendment note: An earlier version of this story said the stapled group is retaining some of its income for H1 2021. In fact, this retention of income was for H1 2020.
READ MORE:
TRENDING NOW
US Fed hikes rates amid stubborn inflation; signals further tightening in coming months
Quarter of Singtel special discounted shares sold ahead of CPF Board transfer
AirAsia’s funding woes test how far Malaysia will go to protect its budget champion
Singapore’s wealth boom is raising the bar for aspiring private bankers

