

MBS seeks deadline extension to deliver details on expansion plan
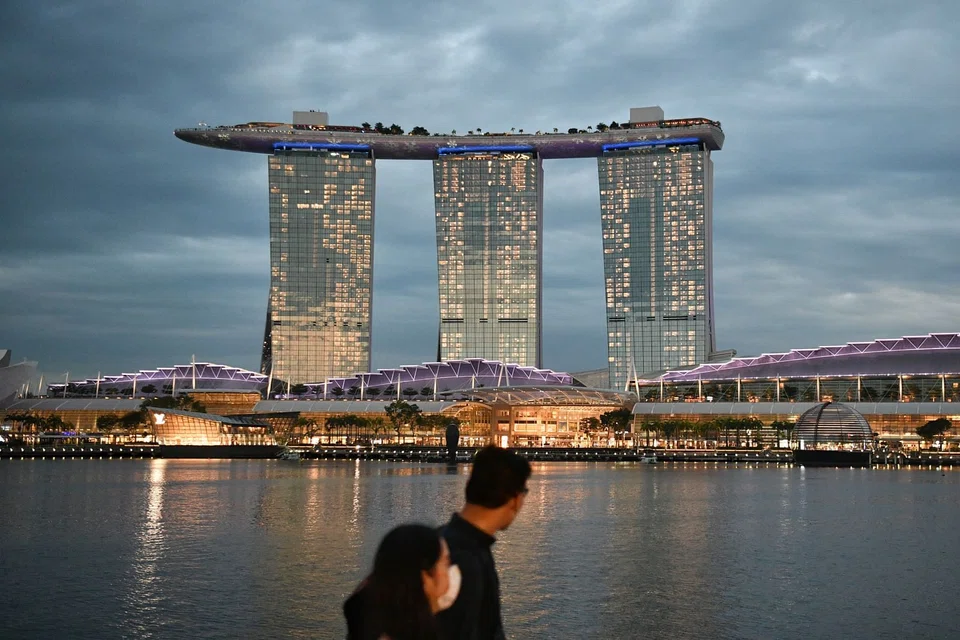
MARINA Bay Sands (MBS) has extended the deadline for it to deliver to its lenders certain details of the expansion of its integrated resort to March 31, 2022.
Information on the quantity surveyor's costs estimate and construction schedule for the expansion of its integrated resort was meant to be delivered on June 30 this year, a filing to the United States Securities and Exchange Commission last week showed.
In July last year, a spokesperson for Singapore's Ministry of Trade and Industry had told The Business Times that a new casino tax regime will take effect in March 2022.
This system imposes higher flat tax rates for integrated resorts that fail to meet their investment commitments.
Details behind this deadline extension were part of a second amendment letter entered on Sept 7 with MBS' lenders - with the letter entered with DBS as the agent bank.
The letter addresses an S$8.67 billion facility agreement, with MBS seeking to waive its requirements to comply with financial covenant provisions for another year, to Dec 31, 2022.
Such waivers would allow MBS breathing room from having to comply with leverage or interest coverage covenants initially tied to the lending facility. The letter also specifies how much dividends it can pay out during the waiver period, which is conditional on certain debt-to-income limits.
MBS announced its S$4.5 billion expansion in April 2019, which will see the development of a new 1,000-room hotel tower and a live entertainment arena with a seating capacity of at least 15,000, among other facilities.
This was part of an agreement with the government, whereby MBS and Resorts World Sentosa (RWS) pledged to plough a combined S$9 billion into new non-gaming attractions. In return, the government would provide them with "business certainty" by ensuring that no casinos will be built here until end-2030.
Both MBS and RWS had said last year that they remain committed to their investment plans, despite the knock-out blow that the novel coronavirus pandemic has landed on the industry.
Based on results posted by Las Vegas Sands, which owns MBS, net revenues of MBS rose 19 per cent year-on-year to US$753 million in the first half of 2021. But this figure is just around half that of US$1.46 billion and US$1.58 billion for H1 2019 and H1 2018, respectively.
MBS's parent company Las Vegas Sands has also been in the red, posting US$192 million in net losses in the three months ended June this year. Losses for the same period last year stood at US$820 million. The company had agreed in March to sell its Las Vegas properties for US$6.25 billion, concentrating its operations in Asia.
Under the latest amendment to its facility agreement, MBS will be allowed to make unlimited dividend payments if the ratio of its debt to consolidated adjusted EBITDA (earnings before interest, taxes, depreciation, and amortisation) is lower than or equal to 4.25 to 1, or up to S$500 million per fiscal year if the ratio of its debt to consolidated adjusted EBITDA is higher than 4.25 to 1, subject to additional requirements.
Speaking to analysts after the announcement of its second quarter results this year, Las Vegas Sands president and chief operating officer Patrick Dumont had expressed uncertainty as to whether it can meet its current 2025 deadline for completion of the MBS expansion project. Mr Dumont said the company was facing lengthy delays as a result of the Covid-19 pandemic, which had prevented the progress of certain works on the site through most of this year.
READ MORE:
TRENDING NOW

Genting Singapore trails MBS, but helps anchor Malaysian parent group’s finances

Siti Hasmah Mohamad Ali, wife of former Malaysian PM Mahathir Mohamad, dies aged 100

He built the Vingroup empire. Now South-east Asia’s richest man is handing some key roles to his sons

Why US midterm elections could power the next stock market rally

