

S-Reit investors need not fear rising rates
Reits still offer decent spread to 10-year government bond yield; reflation signals growth for quality names
THE rise in the US 10-year Treasury yield is giving equity investors in the high growth US technology stocks the jitters. The technology-heavy Nasdaq fell over 10 per cent in early March from a year's high in mid-February.
The rise in the bond yield stems from fears over inflation escalating as the economy recovers amid huge fiscal stimulus and ultra loose monetary policy.
In Singapore, the 10-year government bond yield has also been rising. Today, it is at about 1.6 per cent compared with 0.9 per cent at the start of the year and 0.7 per cent in mid-May 2020.
Consequently, investors in the safe haven defensive real estate investment trust (Reit) sector in Singapore have been rattled by the rise in long-dated bond yields.
And it shows. Unit prices of high-flying large cap S-Reits such as Keppel DC Reit, Mapletree Industrial Trust, and Mapletree Logistics Trust fell by double digits between early February and early March.
But meanwhile, the one month and three-month Sibor rates (Singapore Interbank Offered Rate), while up marginally, have remained relatively flat since mid-2020 and are at below 0.5 per cent and 0.3 per cent respectively. Borrowers using floating rate mortgages tied to Sibor to fund residential property purchases continue to enjoy cheap funding.
Unit prices of S-Reits have since recovered somewhat from the lows in early March as investors get slightly more comfortable with where long-term bond yields are heading.
Given this, should investors favour residential property in Singapore buoyed by low mortgage rates and be more cautious with Reits given the spectre of higher long-dated bond yields?
S-Reits generally still trade at a decent spread to the 10-year government bond yield, typically in excess of 250 basis points.
Based on annualised reported distribution per unit (DPU) for the latest quarter or half year, the largest Reits, CapitaLand Integrated Commercial Trust and Ascendas Reit, trade at yields of around 5 per cent.
This return exceeds that of the recently oversubscribed Astrea VI Class A-1 bonds, issued by an entity of Temasek Holdings Azalea Asset Management. These bonds offer a yield of 3 per cent per annum assuming they are called after five years.
Savings in CPF accounts pay interest rates of 2.5 per cent per annum or more while the April issue of the Singapore Savings Bonds provides a yield of 1.15 per cent per annum over a 10-year period.
If the rise in the yield of long-dated government bonds arises from economic growth creating inflationary pressures, this need not be bad for S-Reits.
Prices of S-Reits, like those of many listed equities, plunged in March last year when the world realised that it was facing a major pandemic and could not see light at the end of the tunnel. Investors in S-Reits feared that occupiers of space, whether retail, office or industrial, would go bust. This would lead to a sharp drop in revenue.
Against that backdrop, rising economic confidence and pace of economic growth, even if that comes with inflationary pressures, can be positive for Reits.
Incremental demand for real estate stems from businesses growing and consumer spending increasing. When the income of businesses and households rise, tenants of Reits can afford higher rents.
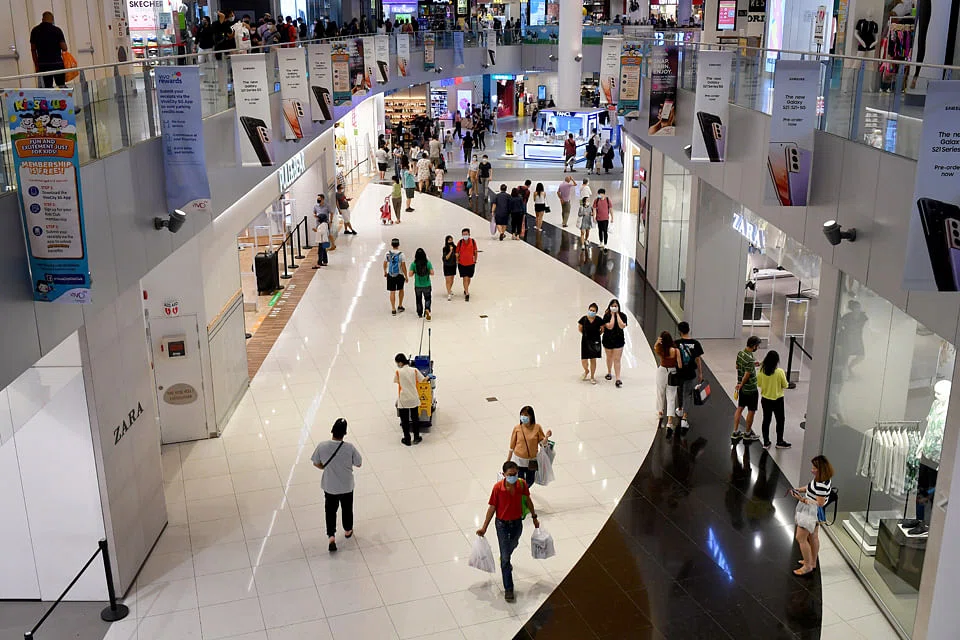
Retail and hospitality Reits stand to gain most from the further opening of economies and borders.
More shoppers could patronise Mapletree Commercial Trust's destination mall VivoCity while international travellers could occupy rooms at hotels owned by trusts such as CDL Hospitality Trusts and Far East Hospitality Trust.
Industrial Reits should benefit too as business prospects improve in the manufacturing sector.
Recently, Ascendas Reit has seen major take-up of space coming from growth areas such as biomedical and agri/aquaculture, and logistics and supply chain management.
The capitalisation rate used to value the properties held by Reits could rise in line with higher longer dated bond yields. Assuming no change in net property income, a higher capitalisation rate causes valuation to drop.
Declines in the valuation of investment properties will affect the ability of Reits to borrow as they have to adhere to limits on total borrowings relative to total deposited property value.
Higher capitalisation rates can, however, be mitigated by rises in revenue and net property income such that property valuations are not adversely impacted.
Many Reits rely on making yield accretive acquisitions of properties to grow DPU. More realistic pricing from asset vendors can help Reits in executing on acquisitions.
As it is, the story of making yield accretive acquisitions continues with Ascendas Reit buying 11 data centres in Europe for S$904.6 million in mid-March.
How much more the 10-year government bond yield will rise is beyond the control of Reit managers.
Can the yield reach 3 per cent or more seen in 2008 and earlier? Or will it generally stay below 2.5 per cent as has typically been the case over the last five years?
Reit managers may be hopeful that the 10-year government bond yield stabilises at around no more than 2.5 per cent, which means a Reit trading at 4.5 per cent yield still gives positive spread of 200 basis points.
Nonetheless, all Reit managers can do is to focus on growing net property income and DPU; be active in managing the leases, costs and balance sheet; make prudent acquisitions and execute well on developments and asset enhancements.
Over time, many Reits have grown in size. This enables them to undertake developments and asset enhancements without significantly hurting income near term.
Reits today have established track records and enjoy good access to funding. Some are included in major indices, well covered by analysts and widely held by institutions and high net worth individuals. Quality names in the Reit space should be able to overcome the challenge posed by higher long-term interest rates.
- The Level Ground is a column looking at the ins and outs of property investments and asset plays.
TRENDING NOW

8 public officers referred to police over property buys near unannounced MRT stations: Chan Chun Sing
DBS tops trades in smaller board lots on debut of revised SGX framework

Grab CEO’s wife Chloe Tong on life with Anthony Tan and finding her purpose
Retrenched PMETs who return on lower pay see median 25% wage cut

