

The next wave of customer engagement
Through AI, Digital and Data, OCBC is transforming banking from transactions to predictive, proactive engagement, with seamless digital experiences reinforced by trust, security and customer centricity
BANKING used to be judged largely on efficiency – how quickly a transaction could be completed, a query answered or a service issue resolved.
Today, digital convenience is the baseline. Customers expect their bank to understand their needs, anticipate potential issues and provide relevant support whenever and wherever it is needed.
The next frontier lies in making every interaction feel continuous, personalised and effortless.
For OCBC, this shift is not simply just another phase of digital transformation.
Sunny Quek, head of global consumer financial services at OCBC, says the industry’s next phase will depend on how well banks connect fragmented touchpoints into one coherent experience.
“Getting there requires real integration of AI, digital and data and a willingness to redesign customer engagement processes and touchpoints,” Quek says.
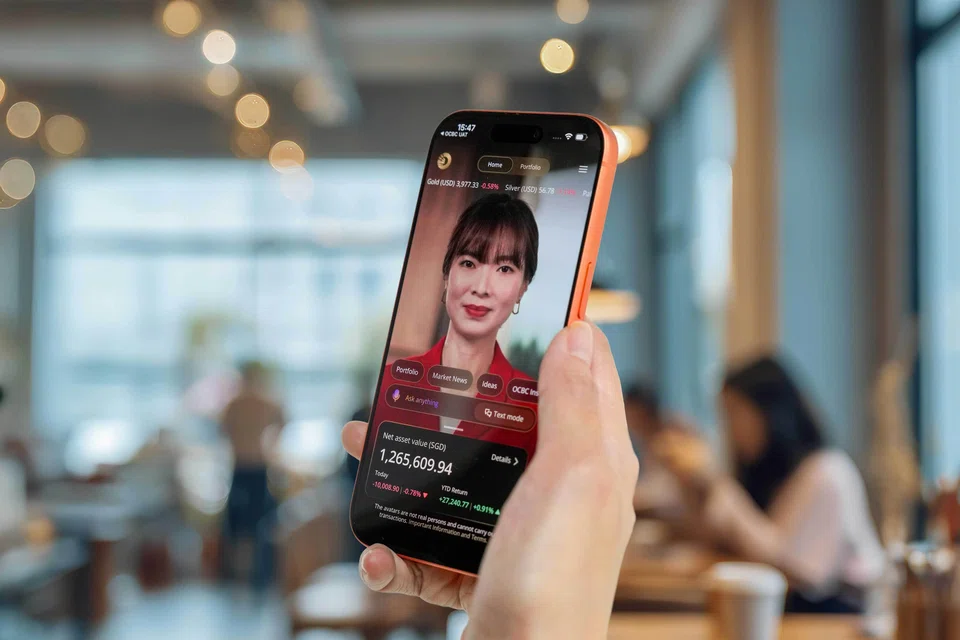
The bank was the first to set up a dedicated AI unit in 2018. This year, it is changing the game again with Avatar Banking by OCBC WoW (Whole-of-Wealth), the bank’s AI-native wealth app.
Featuring avatars Wendy and Wayne as digital financial assistants, OCBC WoW gives affluent customers access to realtime hyper-personalised market intelligence, portfolio insights and investment ideas through natural voice or text conversations.
The significance lies not merely in creating another digital channel but in changing how customers engage with the Bank for wealth management.
Instead of relying only on scheduled meetings with relationship managers, customers can now explore investment opportunities, better understand their portfolios, and make more informed decisions for better investment outcomes.
AI, Digital and Data
Through its investments in AI, Digital and Data (ADD), OCBC sees technology not as an end in itself but as a way to remove friction, personalise engagement and make banking more seamless.
According to Quek, the starting point is still the customer.
“Ultimately, we see ADD as an enabler,” Quek says, “What grounds our approach is customer centricity and ensuring we can use technology to make banking simpler for customers.”
AI, Digital and Data are now at the heart of how OCBC operates. The bank has already committed to investing over S$1 billion annually in technology in the next three years.
For consumer banking customers, the ambition is to move beyond digitalising processes to build contextual relationships that evolve with customers throughout their financial journeys.
A key change is the move from solving problems after they arise to spotting friction earlier, using AI, digital tools and data analytics to prevent issues from escalating.
OCBC established a Customer Centric Experience Design process specifically to ensure customer’s needs are considered from the start of any new initiative. Through early stakeholder engagement and data-driven decision-making, the team addresses potential issues early, reducing downstream impact. Working with business leaders, the team continually refines each initiative, ensuring changes are effectively designed and adapted to better meet customer needs.
“Today, AI, digital and data are helping us make that move, from ‘reactive resolution’ to ‘proactive prevention’, essentially, predictive solutioning,” Quek says.
This allows OCBC to look beyond individual incidents and analyse behavioural patterns across customer journeys, setting up a broader rethink of how experience itself should be measured and improved.
Transforming customer experience
“Leveraging ADD, we’re levelling up engagement around a paradigm shift: from seamless banking transactions to a contextual banking relationship,” Quek says.
That shift is changing how OCBC evaluates experience, looking not only at satisfaction after an interaction but at how easy the journey was in the first place.
“Traditionally, we have focused on customer satisfaction scores which is derived from feedback that a customer provides after an interaction,” Quek says, “While satisfaction remains important, we are also increasingly examining ‘customer effort’.”
Customer effort provides a different lens on service quality. It looks beyond whether a problem was eventually resolved to examine friction along the way, such as repeating information, switching between channels or spending unnecessary time completing a task.
By removing these obstacles, OCBC is redesigning journeys to become more intuitive, seamless and convenient.
“Customer effort is a hidden cost,” Quek says. “Lowering effort is a stronger predictor of loyalty and advocacy than satisfaction alone, and it forces process redesign rather than surface-level service recovery.”
Behind the scenes, OCBC is applying Gen AI across millions of customer interactions to identify opportunities for continual improvement at a scale that would otherwise be impossible.
Quek says, “We can do all these at scale with Gen AI. By identifying recurring issues and emerging pain points across large volumes of customer conversations, we can prioritise intervention more effectively and address issues before they escalate.”
Customer complaints are no longer treated as isolated incidents. The bank studies recurring and emerging patterns to uncover root causes, whether they sit in product design, customer communications or operational processes.
Fixing the underlying issue, rather than only addressing the symptom, enables improvements that benefit many more customers.
This learning is amplified through service dashboards customised for each region that give OCBC a consistent view of service performance across its regional markets.
Best practices that work well in one location can be shared quickly across the region, while emerging issues can be detected and addressed earlier.
AI is also used to recognise examples of exceptional customer service that can be replicated across teams, creating a feedback loop that raises standards across the organisation.
The same disciplined use of insight has translated into practical innovations that solve real pain points.
One initiative is the Online Call feature within the OCBC app, which has been progressively introduced to make it easier for customers abroad to seek assistance. The bank’s data showed that more than nine in 10 customers who faced card transaction issues overseas did not reach out for support because of International Direct Dialling (IDD) charges.
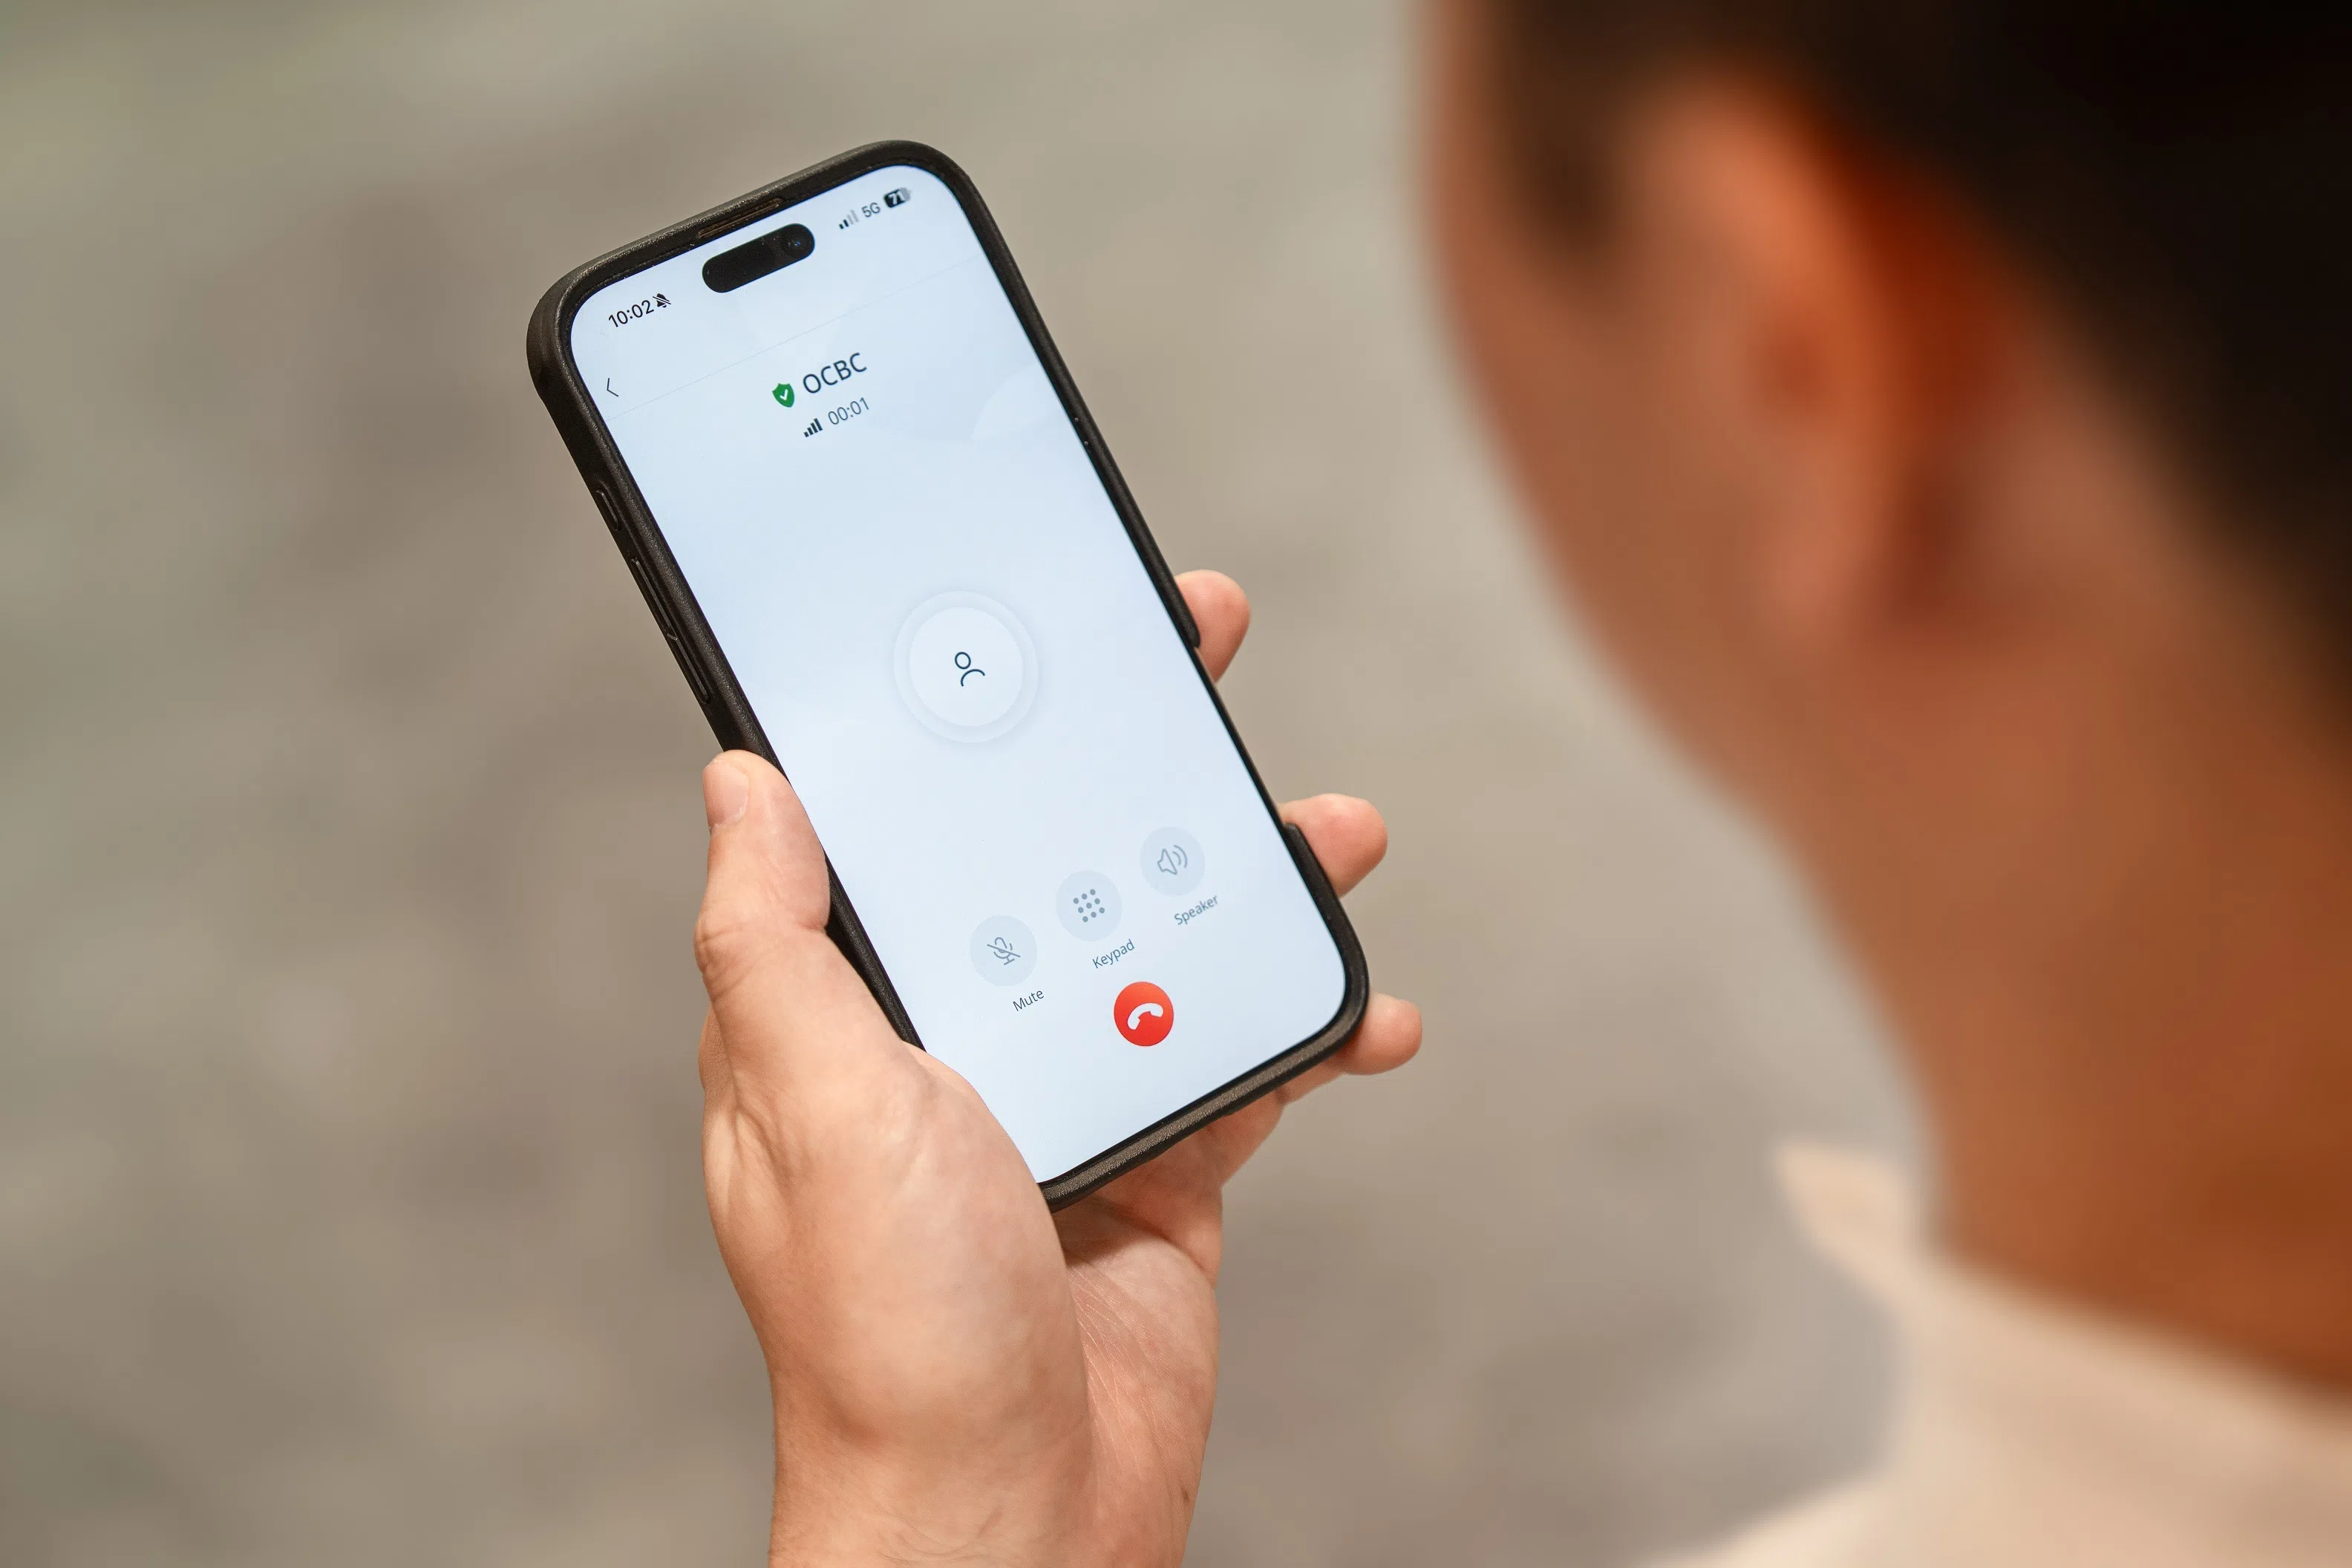
By allowing customers to contact the bank securely through the app, the feature eliminates the need for costly international call charges.
As customers are already authenticated when they log in, the process is more seamless and allows issues to be resolved more quickly when they are away from home.
Humans still rule
Even with embracing ADD, OCBC is striking a balance between digital scale and human service across its customer touchpoints.
The bank’s aim is not to replace relationship managers but to give them better context for the conversations where human judgement matters most.
“Empathy, judgment, and trust in complex, emotionally weighted conversations remain distinctly human,” Quek says.
The technology is designed to enhance advisory relationships by giving customers timely insights while enabling advisers to focus on higher-value conversations that require judgement, trust and personalised advice.
That commitment is reflected in OCBC’s continued investment in its people. Today, three in five employees across the bank have been trained in AI, digital and data capabilities.
One such example is the use of generative AI to coach wealth advisers by identifying capability gaps and enabling supervisors to provide more targeted guidance. This has led to an increase in productivity with wealth advisers who had been trained with Gen AI, resulting in stronger sales performance and 50 per cent higher revenues compared to the three months before they were trained.
The bank also plans to hire 600 additional relationship managers over the next three years to support increasingly sophisticated wealth management needs and build deeper customer relationships.
The next frontier
Taken together, these initiatives reinforce OCBC’s broader Next Frontier strategy.
“It is not a separate innovation function, but a conscious effort across the group’s businesses and markets,” Quek says. Innovations developed in one market or business can be scaled across the organisation, helping customers benefit from continual innovation regardless of where they bank with OCBC.
While AI, digital and data can make personalised engagement possible at scale, enduring customer relationships are still built on trust.
By redesigning journeys around customer effort, anticipating needs before problems arise and empowering employees with better insights, OCBC is shaping a future where banking feels less like a transaction and more like a lasting relationship.
Reimagining customer engagement
- Strong test-and-learn culture with nimble scalable execution
- AI, Digital and Data at our core, with continued leadership in innovation
- Hyper-personalisation at scale for our customers
- Seamless human-AI collaboration for our employees through a future-ready workforce
- Transform the way we measure customer engagement and satisfaction
Share with us your feedback on BT's products and services
TRENDING NOW

Grab CEO’s wife Chloe Tong on life with Anthony Tan and finding her purpose

He built the Vingroup empire. Now South-east Asia’s richest man is handing some key roles to his sons

Singapore’s S$80 million vertical farm must pass the 50-cent test to succeed
Data centre energy demand from Asean telcos not a ‘big risk’, says industry group

