

Dirty heavy goods vehicles drive roughshod over emission policies
Current rebates and surcharges apply only to light goods vehicles, but not heavier, more polluting ones
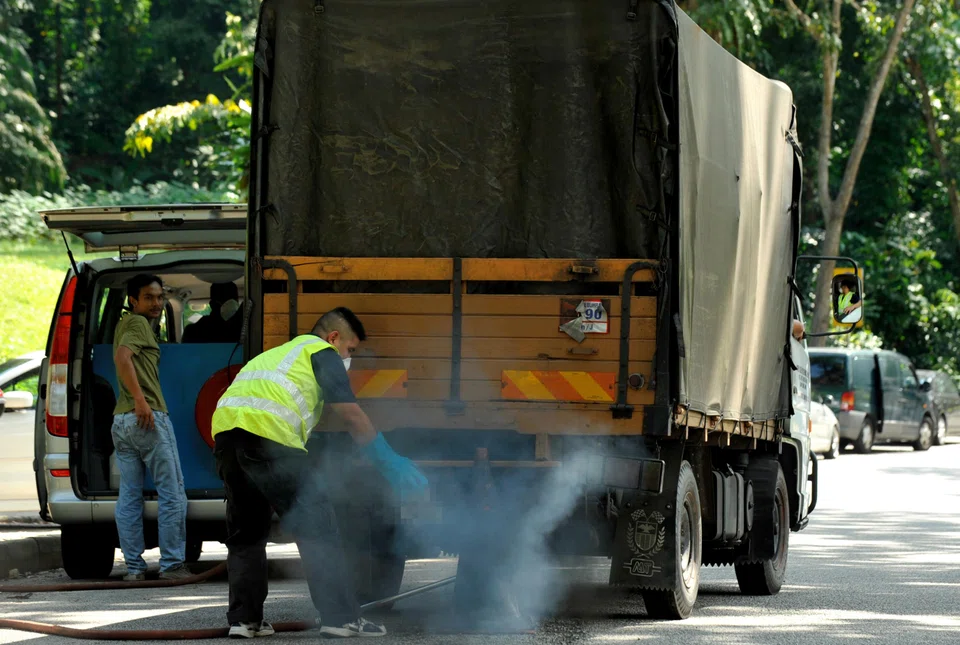
SINGAPORE is among the world leaders in adopting electric light goods vehicles (LGVs) – thanks to effective emissions incentives. But the absence of such initiatives for diesel-powered heavy goods vehicles (HGVs) seems to encourage growth of the latter.
Passing the buck
Introduced in 2021, the Commercial Vehicle Emissions Scheme (CVES) encourages the adoption of less-polluting light goods vehicles by categorising vehicles into bands according to their level of pollution. These bands come with different tiers of rebates and surcharges.
Since April 2023, cleaner vehicles are categorised into Band A (S$15,000 rebate), B (S$5,000 rebate) and less clean vehicles, in Band C, face a S$15,000 surcharge.
The effect was immediate.
That year, electrified goods vehicles formed 53.1 per cent of new LGV registrations, up from just 0.4 per cent in 2020. The global equivalent in 2022 was just 3.6 per cent, according to the International Energy Agency.
The Republic’s share of petrol goods vehicles as opposed to more polluting diesel vehicles rose to 34.4 per cent, from 18 per cent before. Diesel vehicles plummeted to 12.4 per cent from 81.6 per cent.
The combination of rebates and incentives were enough to push the needle wildly in favour of electric and petrol LGVs.
As reported by The Business Times recently, CVES applies only to LGVs.
While cleaner LGVs make up a larger proportion of new registrations, their population on the roads has fallen, while that of HGVs has increased.
In 2023, diesel vehicles made up 93.1 per cent of HGV registrations.
The Land Transport Authority categorises LGVs as having a maximum laden weight (MLW) of 3,500 kg or less, while HGVs have an MLW of 3,501 kg to 16,000 kg.
Some diesel-powered models, mostly 10-foot lorries, on the borderline between the two categories, were reintroduced by manufacturers as HGVs to avoid surcharges.
It has been enough to reverse a seven-year trend of LGV increase and HGV decrease and vice versa. Additionally, because of the Certificate of Entitlement (COE) lifespan of 10 years, it is likely that we will be saddled with these diesel vehicles for at least another decade.
An increase in heavier and more polluting vehicles is at odds with the aim of CVES, which is to cut carbon emissions and pollution.
Diesel commercial vehicles and buses are key local emission sources of particulate matter and nitrogen oxides.
Spectrum analysis
The solution is to progressively extend CVES to HGVs and also heavier types of commercial vehicles.
In response to BT queries the National Environment Agency (NEA) said: “Some models of HGV goods vehicles sold in Singapore today are variants of LGV models which are available overseas for some time, before the CVES was introduced.
“HGVs are not covered by the CVES as cleaner and market-ready alternatives are still limited, unlike cleaner LGVs which are more widely available and market-ready.”
But market-readiness is often determined by rebates and incentives, so it could be a chicken-and-egg situation.
As the passenger car and LGV sectors have shown, electrification is very much incentive dependent since EV prices have not reached parity with petrol or diesel offerings.
Upon the introduction of the EV Early Adoption Initiative (EEAI) in 2021, passenger EV adoption has skyrocketed to 21,796 as at September 2024, from 1,217 at the end of 2020.
As previously mentioned, the uptake of electric LGVs has been even more dramatic since the advent of CVES.
The lack of suitable HGV models seems like a weak argument.
Car manufacturers, for example, have introduced several car models tailored to Singapore’s COE categories.
Even without incentives, there are already at least seven electric HGVs on the market now from manufacturers DFSK, Farizon, Foton, Golden Dragon, JAC, Mercedes-Benz, and Volvo, among others.
Dealers say the price gap between an electric and diesel HGV now starts from 25 per cent, or around S$25,000, but scales upward according to vehicle size and weight.
Chinese manufacturers, who make most of the electric HGVs available, have also shown to be more willing than others to create tailored products for Singapore.
According to Zeti, a global commercial vehicle database, the number of medium duty, heavy duty electric trucks and vans available as at 2024 is 454.
Heavy fuel
From the technical point of view, NEA’s concerns are not without merit.
Electrification becomes more difficult the heavier the vehicle, because the energy density of batteries is lacking, and they cannot provide adequate range, compared to diesel.
But that is also exactly why nuanced emissions and pro-EV regulation are required. In their current state, and for the next five years at least, EVs cannot be a complete solution. That is where other technologies, such as hybrid or plug-in hybrids, could fill the gap.
The electrification journey will not be smooth. That is why progressive rebates or surcharges should be applied depending on the weight of the vehicle segment in question.
In addition, the application of a technology-based incentive – such as EEAI – could be considered instead of just a performance-based one, such as CVES, if one form of technology is seen to be the optimal solution for the time.
If the market is immature, then incentives could promote the first wave of adoptions whose numbers are not likely to be huge, but could provide valuable lessons to the rest of the industry.






