Economists trim inflation forecasts after Singapore’s October core, headline inflation reach lowest since 2021
Core inflation at 2.1%, headline at 1.4%
SEVERAL private-sector economists have cut their Singapore 2024 and 2025 inflation forecasts, after October’s readings decelerated more than expected to their lowest prints since 2021.
Year on year (yoy), October’s core inflation – which excludes accommodation and private transport – was 2.1 per cent, data from the Monetary Authority of Singapore (MAS) and Ministry of Trade and Industry (MTI) showed on Monday (Nov 25). This was a sharp fall from September’s 2.8 per cent, and was the lowest reading since December 2021, when it was also 2.1 per cent.
The slide was due to a moderation in services, electricity and gas, and in retail and other goods inflation. The reading was also lower than the 2.5 per cent median forecast in a Bloomberg poll of private-sector economists.
Core inflation last fell by a similar magnitude in January 2013, although the underlying factors differed, said DBS economist Chua Han Teng.
Then, lower contributions were recorded from all major components – “with particular mention of slower food inflation (due to base effects associated with Chinese New Year), and cooler services inflation (due to more moderate increases in the costs of public transport and medical treatment)”, he noted.
Headline inflation eased to 1.4 per cent from 2 per cent in September, and was below economists’ median estimate of 1.8 per cent. October’s print was the lowest since March 2021, when headline inflation was 1.3 per cent; it was also the first time headline inflation had fallen below 2 per cent since then.
MAS and MTI attributed the fall to slower accommodation inflation and a steeper decline in private-transport costs, in addition to lower core inflation. October’s data brought the year-to-date core and headline consumer price index (CPI) average to 2.9 per cent and 2.5 per cent yoy, respectively.
Month on month, both the core and overall CPI fell 0.3 per cent in October.
Outlook comparison
“MAS’ rhetoric remains similar,” said OCBC chief economist Selena Ling.
The authorities maintained their 2024 full-year core inflation forecast at 2.5 to 3 per cent, and their headline inflation forecast at around 2.5 per cent. MAS and MTI also maintained their 2025 projections, at 1.5 to 2.5 per cent for both core and headline inflation.
Bank of America (BOA) economists Ang Kai Wei and Rahul Bajoria noted that the authorities now expect core inflation to remain at around 2 per cent “through” end-2024, versus “by” end-2024 previously – implying Q4 2024 core inflation was even lower than the average of 2.2 to 2.3 per cent pencilled in the October macroeconomic review.
MAS and MTI also said that the downside risk from the global growth slowdown could cause domestic inflation to come in “lower than expected”, omitting “materially” compared to before. This could suggest that the downside risk may be capped by near-term inflationary pressures arising from US policy changes, the BOA team said.
OCBC’s Ling pointed out that incoming US president Donald Trump’s touted punitive trade tariffs on China and universal tariffs elsewhere “may usher in some retaliation if they materialise, and be inflationary in nature”. Still, OCBC’s projections broadly align with MAS forecasts.
DBS’ Chua said the significant easing of October’s core inflation “confirmed the ongoing underlying disinflation trend”, with the preceding two months’ increases being “temporary blips in the broader downtrend”.
UOB associate economist Jester Koh agreed that the month’s inflation data “imparts greater confidence over the durability of the disinflation process”.
Maybank analysts Chua Hak Bin and Brian Lee said inflation is easing faster than anticipated as the authorities step up measures to ease cost-of-living concerns.
Given October’s deceleration, they trimmed their 2024 full-year headline inflation forecast to 2.4 per cent, from 2.6 per cent previously; UOB lowered its headline inflation projection to 2.3 per cent, from 2.5 per cent previously.
For 2024, Barclays senior regional economist Brian Tan reduced his core inflation forecast to 2.7 per cent, from 2.8 per cent; for 2025, paring it back to 1.5 per cent from 1.8 per cent.
He now sees a “much greater likelihood” of policy easing in January 2025, rather than in April 2025. This is because core inflation may fall below 2 per cent earlier than previously anticipated. But he emphasised that this was “a close call”.
Other banks also maintained their call for easing in January.
But UOB’s Koh noted that demand-side inflationary risks persist, and that MAS may normalise only when core inflation is very close to “desired levels” – 1.8 per cent on year – and possibly when GST-effects have completely washed out – which may be in January or April.
Standard Chartered economist Jonathan Koh and HSBC Asean economist Yun Liu believe that January may be too early for a move. Both flagged the uncertainty surrounding Trump’s policies and noted that the MAS may want to wait for more clarity.
Liu also highlighted the MAS’ added flexibility afforded by its quarterly meetings, compared with twice-yearly before.
Key CPI categories
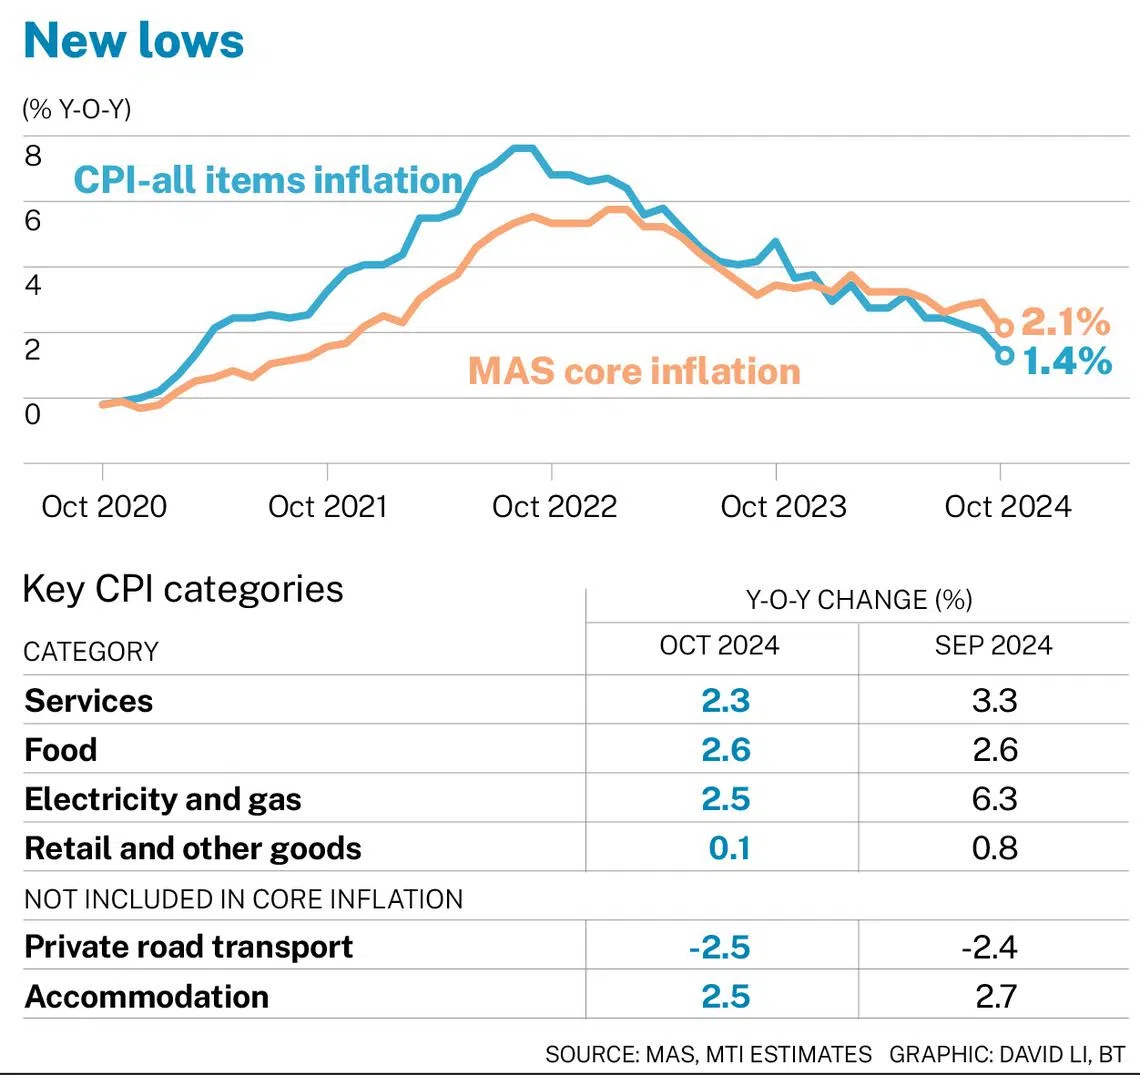
Lower inflation was recorded for most major categories in October.
Services inflation eased, mainly on account of smaller increases in the costs of holiday expenses and healthcare services.
The lower holiday expenses inflation was mainly driven by a slower increase in package tour costs, noted the Maybank duo. Meanwhile, higher thresholds for means-tested healthcare schemes and grants meant that more Singaporean households qualified for higher healthcare subsidies, helping to reduce healthcare inflation significantly, the team said.
Electricity and gas inflation moderated as the prices of both electricity and gas rose more slowly.
Retail and other goods inflation slowed, driven mainly by a steeper decline in clothing and footwear prices as well as a fall in the prices of medicines and health products.
Accommodation inflation slipped due to a smaller increase in housing rents.
Private transport costs fell at a slightly faster pace, on the back of a larger decline in car prices.
Food inflation was unchanged, as non-cooked food and food services prices rose at a similar pace in September and October.