

BT Explains: What is cost-push inflation and how can governments address it?
Tessa Oh
THE US Federal Reserve’s 75-basis-point hike last week – the largest interest rate increase since 1994 – aimed to curb soaring inflation, which has hit decade-highs in the US and the European Union.
Yet such hikes chiefly target demand-side inflationary pressures, while today’s rising prices are fuelled by supply-side constraints.
The Business Times (BT) looks at the difference between demand-pull and cost-push inflation and the tools policymakers can use to contain it.
Demand-pull vs cost-push inflation
When prices rise due to fast growth in demand for goods and services, that is demand-pull inflation. This usually happens in tandem with overall economic growth.
Cost-push inflation occurs when the supply of goods and services falls while demand remains the same, resulting in higher costs.
The fall in supply may arise from government regulations, unexpected shocks such as natural disasters, or shortages of raw materials.
Why are prices rising now?
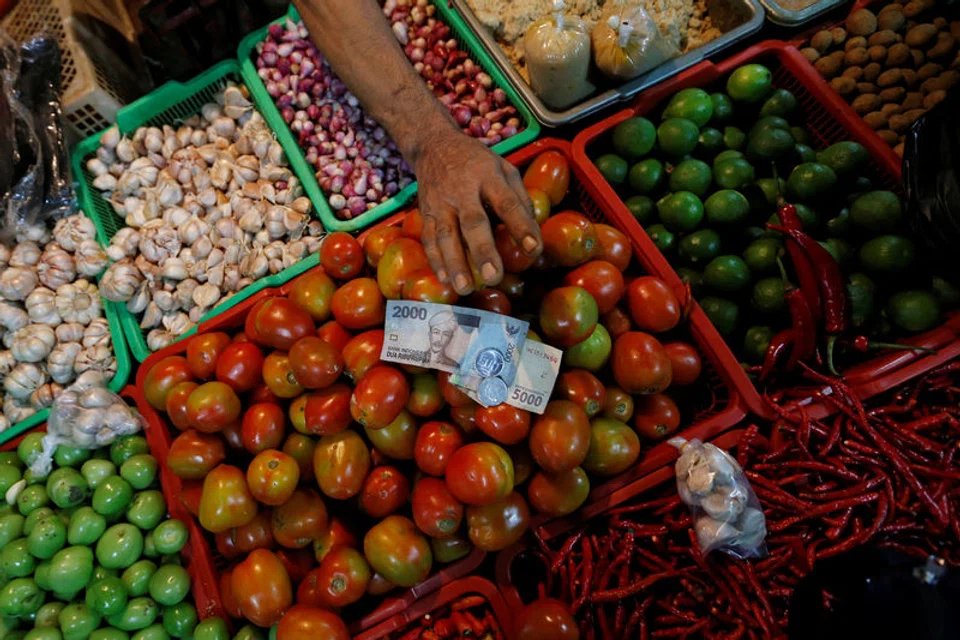
Today’s rising prices are mostly a result of cost-push inflation: Covid-19 resulted in unprecedented supply chain disruptions, and these bottlenecks have jacked up prices globally.
Russia’s war in Ukraine, which has contributed to huge price rises in commodities, has only exacerbated these challenges.
Demand-driven inflationary pressures are not as significant for now, especially with the slowdown in China’s economic activities having knock-on effects on global growth.
What can policymakers do?
Tightening monetary policy, as the Fed has done, makes borrowing more expensive. This curbs consumer spending and business investment, and therefore reduces demand-fuelled inflationary pressures.
But dampening demand means curbing growth. Raising interest rates at a time when inflation is not chiefly driven by growth – or indeed, when growth prospects are dimming – runs the risk of tipping the economy into a recession.
More to the point, demand-side measures do not address inflation arising from supply shortages.
Still, Moody’s Analytics economist Harry Murphy Cruise noted that central banks need to be seen to be addressing inflation.
“If expectations of inflation get out of control, we could see upward price spirals that are difficult to stop. A handful of strong rate rises can quell some of these fears,” he told BT.
Cost-push inflation is better addressed by supply-side measures – such as introducing subsidies or grants, deregulating industries, and spending on research and development.
Steve Cochrane, Moody’s Analytics chief economist for Asia-Pacific, said Asean may see an acceleration of investment in renewable energy in response to existing fuel shortages.
“Crude oil producers in the Middle East and in the US are expected to respond to higher costs with accelerated investment and production,” he added.
But supply-side policies usually take longer to make an impact, as they are aimed at increasing an economy’s long-term productive capacity.
In theory, countries could collaborate on solutions to alleviate some supply-side pressures. But CIMB Private Banking economist Song Seng Wun said history has shown that in times of crisis, governments have tended to prioritise national interests over multilateral cooperation.
“At the end of the day, if countries and governments choose to go down the protectionism route, there’s not much you can do,” he said, citing the Covid-19 Vaccines Global Access (Covax) initiative as an example, which failed to live up to its promise to provide low-income countries with access to Covid-19 vaccines.
That is why the simplest way is to deal with inflation on the demand side, said Song. “While you cannot force the supply, if central banks were to aggressively hike rates such that demand side cools down, then prices will fall.”
What has Singapore done in the past?
Singapore saw high and volatile inflation in the 1970s, due in large part to the global oil crisis. Headline inflation was driven to 20 per cent in 1973 and around 30 per cent in the first half of 1974.
At the time, the Monetary Authority of Singapore (MAS) implemented a mix of monetary tightening measures – including raising the bank’s statutory reserve requirement to 9 per cent; imposing a credit ceiling and guidelines; and hiking interest rates by 2 percentage points in October 1974. Domestic inflation was brought down swiftly to −1.9 per cent in 1976.
Since then, MAS has changed its approach to monetary policy: It now makes adjustments to the policy band of the exchange rate – the Singapore dollar nominal effective exchange rate (S$NEER) – to ensure prices remain stable.
In a small open economy such as Singapore, the exchange rate has a much greater effect on inflation than interest rates. Exchange rate policy can also help alleviate cost-push inflation.
The appreciation of the Singapore dollar (SGD) lowers the relative cost of imports – including raw materials.
Another inflationary period was the late 2000s, when Singapore’s headline inflation rose rapidly from 0.5 per cent in 2005 to a peak of 6.6 per cent in 2008.
This was due partly to external cost pressures, with strong global commodity prices – though those were, in turn, fuelled by demand from rapid economic growth in China and other emerging economies.
Responding to this, MAS slightly steepened the slope of the S$NEER policy band in October 2007, allowing the SGD to appreciate at a faster pace to offset the rising cost of imported goods. In April 2008, it re-centred the policy band higher, for a higher appreciation path.
By October 2008, cost pressures had receded enough – with the growth outlook also looking grim – that MAS lowered the slope to a neutral position. In the end, it was the Global Financial Crisis that ended the uptrend by 2009.






