Singapore’s full-year growth set to track near potential rate after resilient Q3 beats expectations
Economists lift 2025 forecasts after third-quarter GDP rises 2.9%, but caution over cooling momentum and external headwinds in 2026
[SINGAPORE] The Republic’s economy is on track to deliver full-year growth close to its potential path, after third-quarter gross domestic product showed unexpected resilience and surpassed market expectations.
Singapore’s economy grew 2.9 per cent year on year (yoy) in Q3, slowing from the previous quarter’s 4.5 per cent, advance estimates from the Ministry of Trade and Industry showed on Tuesday (Oct 14).
Nevertheless, the Q3 performance beat the median forecast of 2 per cent growth projected by private-sector economists polled by Bloomberg.
In its October macroeconomic review released on Tuesday, the Monetary Authority of Singapore (MAS) noted that the economy has expanded at an above-trend rate of 3.9 per cent yoy in the first nine months of this year. The central bank assesses that the output gap should remain positive for 2025 as a whole.
The stronger-than-expected performance prompted some economists to revise their full-year growth projections upwards.
UOB now expects the economy to expand 3.2 per cent for 2025, up from its previous forecast of 2.7 per cent. The bank has also raised its 2026 growth outlook to 1.8 per cent, from 1.5 per cent previously.
Maybank similarly upgraded its 2025 forecast to 3.5 per cent, from 3.2 per cent before. The revised projection implies Q4 GDP growth of 2.4 per cent, said economists Chua Hak Bin and Brian Lee.
DBS analysts Chua Han Teng and Philip Wee also revised their forecast up to 3.5 per cent, from 2 per cent previously, while RHB lifted its projection to 3 per cent, from 2.5 per cent.
All the forecasts now exceed the official full-year projection of between 1.5 and 2.5 per cent GDP growth – though this will likely be revised upwards in November when the actual Q3 GDP figure is released, the economists noted.
Separately, OCBC chief economist Selena Ling projected that full-year growth is likely to come in around the 3 per cent handle, even if Q4 growth moderates to below 1 per cent yoy.
“While full-year 2025 growth would still mark a moderation from the 4.4 per cent growth seen in 2024, this is not a bad outcome given the significant external and domestic economic challenges,” she said.
Tariff risks loom
Yet, growth momentum is expected to cool as activity in trade-related sectors normalises following earlier front-loading.
MAS said GDP growth is expected to moderate in 2026, with the output gap narrowing to around zero per cent.
While uncertainty around the economic outlook has receded somewhat following the conclusion of some trade deals between the United States and various countries, the overall outlook remains cautious, reflecting the lagged impact of ongoing tariff-related adjustments and spillovers to real economic activity, said the central bank.
Fresh trade frictions and a correction in the uplift from artificial intelligence demand also present downside risks to the growth outlook, it noted.
Private-sector economists similarly flagged significant downside risks, including the steep pharmaceutical tariffs already announced by the US, the prospect of additional sectoral tariffs on semiconductors, and further escalation in China-US trade tensions.
The central bank has not incorporated the recently announced 100 per cent tariffs on China and pharmaceuticals into its baseline forecasts, given uncertainty surrounding implementation.
MAS added, however, that the pharmaceutical tariffs may not immediately affect Singapore’s exports, as firms here already have plans to build production capacity in the US.
Similar to the rest of Asia, prices are bearing the brunt of adjustment in Singapore. The GDP deflator fell 2.7 per cent yoy in Q2, while real GDP growth remained firmly positive, MAS noted.
Such divergence between prices and output was uncommon in Singapore’s economy before the pandemic, as price erosions typically coincided with real output losses.
Barring a sudden increase in tariffs or sharp fall-off in demand, firms in the manufacturing sector should have adequate financial buffers to absorb price declines without significantly reducing production, at least for the rest of this year, the central bank said.
Overall, Singapore’s GDP growth is likely to ease to a near-trend pace in 2026, with the exception of a sudden increase in tariffs or sharp deterioration in demand conditions, said MAS.
Labour market “broadly resilient”
Labour market conditions are expected to remain broadly resilient even as wage growth moderates, MAS said. Total employment gains stepped up in Q2 amid stronger hiring in construction, travel-related services and modern services sectors such as finance and insurance.
However, other indicators pointed towards a softer labour market. The ratio of job vacancies to unemployed persons declined in Q2 as labour demand moderated across most sectors, while labour market turnover indicators such as resignation and recruitment rates fell further as more employees remained in their current jobs.
The central bank expects labour market adjustment to continue primarily through wage flexibility rather than headcount reduction. Resident wages are expected to grow at a slower pace in the quarters ahead, following the above-average rate of 5.3 per cent a year recorded in the past two years, while the resident unemployment rate should remain low.
Sectoral growth
On a seasonally adjusted quarterly basis, GDP rose 1.3 per cent, edging down slightly from the 1.5 per cent advance recorded in Q2.
The third quarter’s yoy moderation was driven primarily by a sharp deceleration in goods-producing industries, which expanded just 0.6 per cent yoy, down from 4.8 per cent growth in Q2.
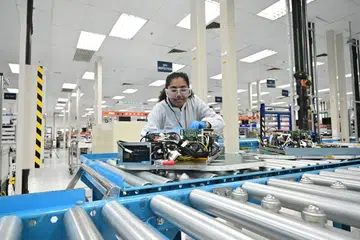
Manufacturing output remained unchanged yoy in Q3, a marked slowdown from the 5 per cent expansion in the preceding quarter.
The sector’s performance was weighed down by output declines in the biomedical manufacturing and general manufacturing clusters, even as other manufacturing segments posted gains.
HSBC analysts Yun Liu and Joey Chew noted that while front-loading activity has peaked, trade has seen moderation, rather than a significant downturn in the trade cycle.
The construction sector also lost momentum, advancing 3.1 per cent yoy compared with 6.2 per cent growth in the previous quarter. Both public- and private-sector construction activity supported the expansion during the period.
On the whole, the services-producing industries proved more resilient, expanding 3.5 per cent yoy, though this represented a deceleration from the 4.5 per cent growth registered in Q2.
Within services, the wholesale and retail trade, and transportation and storage sectors collectively grew 2.5 per cent yoy, easing from 4.9 per cent previously.
Growth in wholesale trade was driven by the machinery, equipment and supplies segment, while the transportation and storage sector benefited from strength in water and air transport.
The information and communications, finance and insurance, and professional services cluster maintained steady momentum, expanding 4.4 per cent yoy, up marginally from 4.3 per cent in Q2. All constituent sectors posted gains, with IT and information services, banking, and head offices driving the advance.
The group of sectors comprising accommodation and food services, real estate, administrative and support services, as well as other services grew 4.1 per cent yoy, up slightly from the 4 per cent expansion in Q2.
The accommodation sector benefited from rising international visitor arrivals, though food and beverage services contracted during the quarter.