

GCash’s rise fuelled by data, investors’ strengths
FOR a service that was launched back in 2005, GCash has survived the transition from an SMS money transfer service to dominating in the e-wallet market in the Philippines.
This dominance has been aided by a large unbanked population, as well as the strength of its investors - conglomerate Ayala, Globe Telecom and Ant Financial.
GCash currently holds court over the Philippine e-wallet market with a 49.4 per cent market share, with rival PayMaya a close second at 41.9 per cent, according to the Mobile Wallets Report 2021 by payments company Boku. GCash’s parent company is Mynt, which is backed by Globe, Ayala and Ant owning a stake in it.
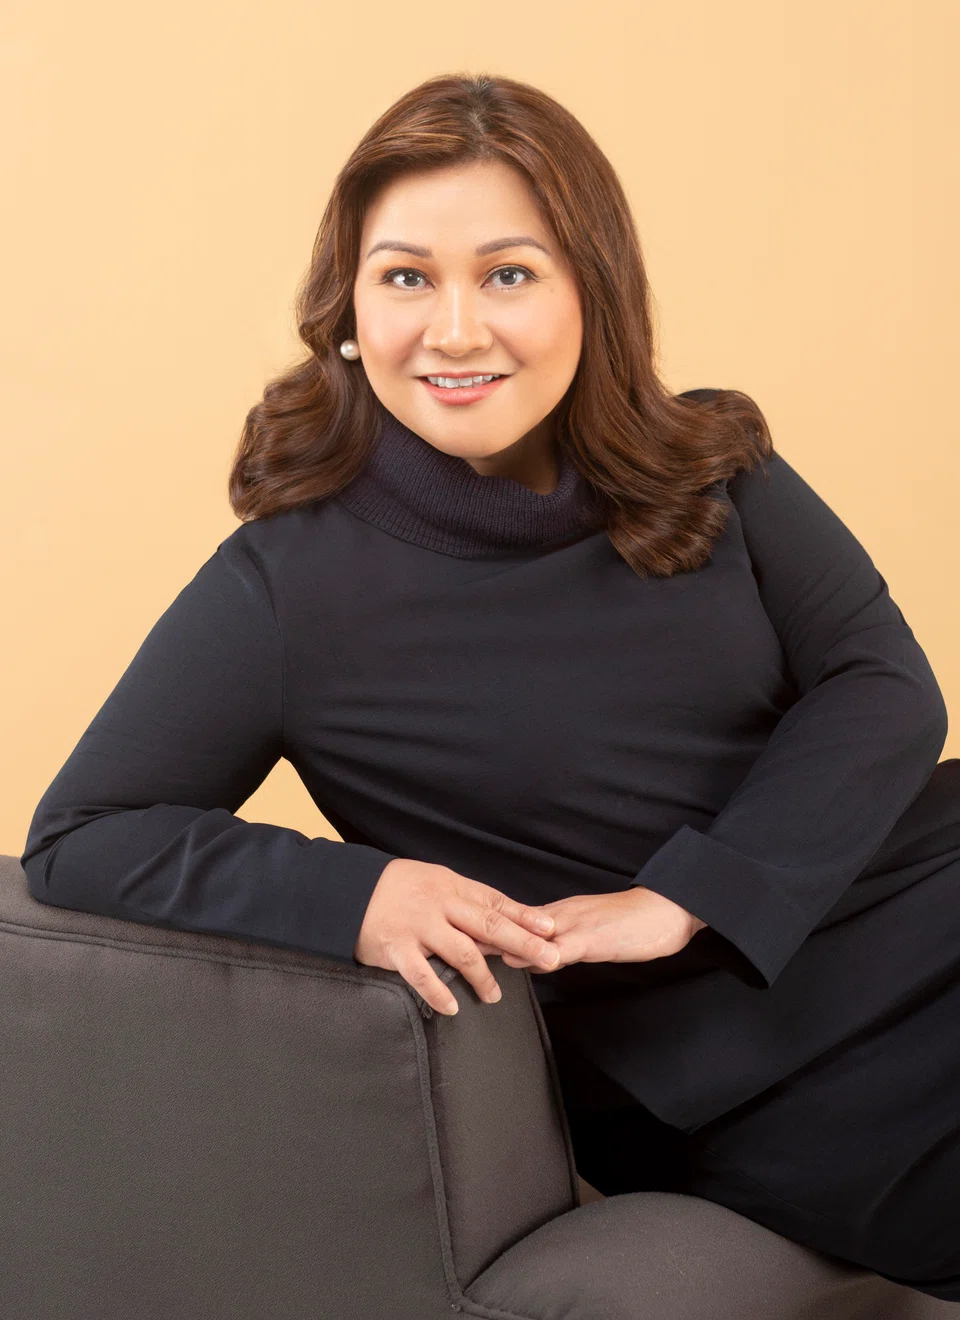
The e-wallet has about 69 million registered users and over 5.2 million merchants in its database, said Martha Sazon, chief executive officer, GCash. The adoption of GCash was also fuelled by the pandemic, as the Philippine government selected it as one of the avenues to disburse cash subsidies to the public.
“We distributed financial aid during the pandemic. What would have taken the government three years to distribute to the constituents, we took several days,” Sazon told The Business Times.
GCash is poised to ride on the growth of digital payments, which are set to rise from US$806 billion in 2022 to US$2.1 trillion by 2030, according to the e-Conomy report 2022. Similarly, lending books are expected to surge from US$50 billion in 2022 to US$325 billion in 2030. These trends are what GCash plans to tap on as the entry point to digital financial services in the Philippines.
GCash is also leaning on its investors’ strengths, from being an avenue to reload telco prepaid cards to tapping on Ayala’s networks, giving them an edge locally. Ant’s experience in running an e-wallet in China and its payment networks outside of the country have also been a resource for GCash to tap.
The Philippine economy is a sachet economy, where the volume is high but transactions are of low value. According to Sazon, about 95 per cent of the population is on prepaid Sim cards, and they frequently load their cards twice, a behaviour that GCash has capitalised on.
“We host the telco loading inside our platform, we offer lending as well in small amounts that people can pay with low interest rates,” said Sazon.
This has allowed GCash to start its own consumer lending products GLoan and GGives. The short-term loan product, GLoan, starts at a 1.59 per cent interest rate varying across users, while GGives is a buy-now-pay-later product with interest rates varying from 0 per cent to 5.49 per cent. Both products are powered by GCash subsidiary Fuse Lending.
The lending business has been on GCash’s radar for at least five years. Prior to their own lending products, GCash had GCredit, a credit line with CIMB Philippines.
Key to that is GCash’s credit-scoring model GScore, which uses transaction data within GCash to assess a customer’s credit score.
“We are able to have a rich data set because of the usage behaviour in GCash. The daily active transactions peak at 24 million, and our active users use the app two times a day at least, across the two to three use cases,” noted Sazon.
The e-wallet has also moved into remittance after launching the service in July 2021 to ride the expected surge in remittance flow. The e-Conomy report forecasts it to rise from US$20 billion in 2022 to US$60 billion in 2030. This remittance service allows the Filipino diaspora to send money directly to their loved ones’ GCash wallets back home. GCash also allows the diaspora to pay directly for expenses as well with a GCash wallet.
“They can load their wallets and send the money across for free. In Hong Kong, our tie-up with Alipay lets users send money to the Philippines for free,” explained Sazon.
With the unbanked and underbanked in the Philippines making up 75 per cent of the population, according to the e-Conomy report 2022, GCash has been tapping them for growth. According to the Philippine central bank, almost 56 per cent of Filipinos own a bank account, doubling after the pandemic. Sazon claims this doubling is due to e-wallet adoption.
This is owing to the partnerships between e-wallets and banks, as Sazon said that the former can partner any bank due to their clear ambition to not be a bank. GCash aids with the banks’ “Know Your Customer” (KYC) checks by verifying their customers’ identity, with fully verified customers able to open a bank account with Maybank Philippines and CIMB Philippines via the GCash app.
“We choose to cooperate rather than compete,” said Sazon.
Looking ahead, GCash will be focused on expanding its user base into rural areas as well as to the micro, small and medium enterprises in the country. There are also plans to further monetise its ad and data businesses.
Sazon said that with GCash’s first-party data, ads can be personalised to each user, with over 50 different customer groups for advertisers to do micro-targeting. As for the data business, GCash is able to do electronic-KYC checks for other businesses to verify the identity of the customer.
“We have customers with the data tech business, and even with GScore, but we are still developing it further,” she added.
TRENDING NOW
From AI financing to Indonesia outlook: 4 takeaways from Singapore banks’ Q3 results

VinFast, Mitsubishi weigh Philippine EV production as state incentives near

Analysts cut DBS target price on lower 2027 earnings, but see buying opportunity after share price slide

Could Japan trigger the next global financial crisis?

