

Green Link Digital Bank grows loan book to S$50 million; eyes IPO on SGX within five years
Benjamin Cher
GREEN Link Digital Bank (GLDB) has grown its loan book from S$20 million on Dec 31, 2022 to S$50 million today, as it targets micro, small and medium enterprises (MSMEs) as customers.
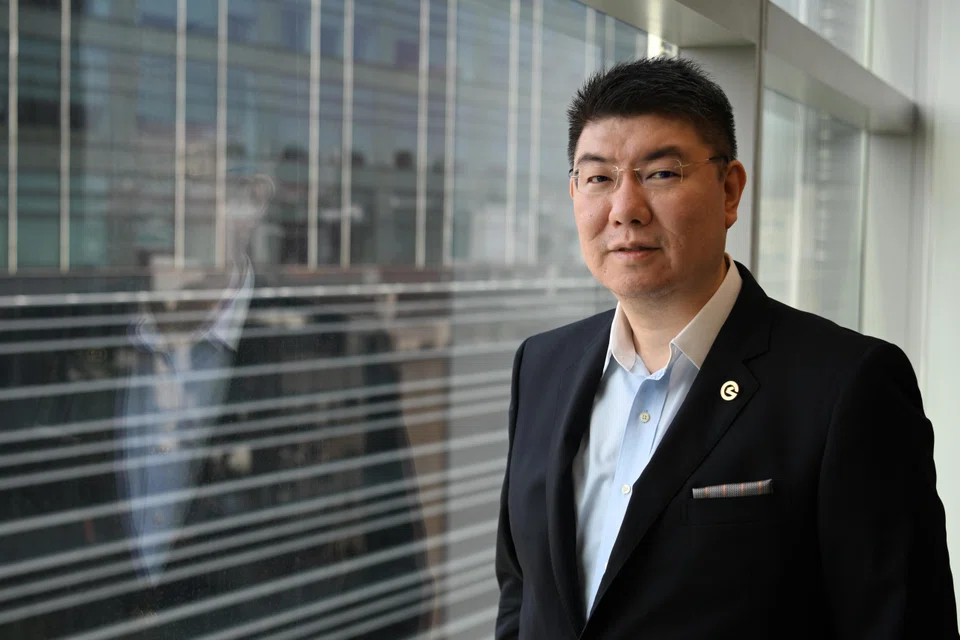
The Greenland Holdings-backed bank also has plans to break even by 2025, said Geng Jing, chairman of GLDB, on the sidelines of its first anniversary. GLDB is aiming for an initial public offering on the Singapore Exchange within five years. While listing in Shanghai may get the bank higher valuations, Geng believes that the bank should be listed in its home market.
“Listing on SGX could also help us, as the exchange and investors would understand the business more,” he said.
GLDB currently does not see a dip in loan applications, but Geng is cognisant that the bank is starting from a low base. There is continued growth in demand for capital by MSMEs, with a “robust” loan pipeline.
Competitor Ant-backed Anext Bank recently launched a business loan product for MSMEs that are not account holders. SMEs can get a loan of up to S$100,000 in a pay-per-use credit line, or a S$300,000 loan paid in monthly instalments.
GLDB said it will not be following suit, preferring to disburse loans to account holders so as to provide a better experience for the customer.
The bank is building up its liquidity and security, said Geng, with a view to ensure that things move smoothly for customers. When these two factors have been built up, the priorities for GLDB will shift.
“When we are more comfortable and stable, then we will shift our focus to profitability,” said Geng.
The wholesale digital bank is also looking to avoid relying on the 80/20 rule, where 80 per cent of revenue comes from 20 per cent of its customers. This would mean that large enterprises would be key to GLDB’s profitability.
But Geng does not rule out serving large enterprises, saying that the bank’s services for these companies would be differentiated compared to legacy banks.
The focus for GLDB is still in serving MSMEs, customers that traditional banks cannot or will not serve due to costs. For the bank, the proposition for its customers is clear.
“We will rely on our speciality of supply chain financing that larger banks might avoid, as well as looking to bank companies with new business models in today’s Web3 era,” said Geng.






