

As Sea awes investors with profits, its challenge is sustaining momentum
Expectations for FY2023 results are much higher, but the company also faces headwinds
WITH good results come greater expectations. New York-listed Sea last week wowed the market with its first-ever quarterly profit, and forecasts of its FY2023 performance have now ramped up significantly.
Keeping up the momentum will be the key challenge for the company going forward, especially as in the face of the dampened profitability of its gaming business Garena and potential costs as it expands its digital banking venture.
On Mar 7, the company reported US$422.8 million in net profit for the fourth quarter ended Dec 31. Excluding one-off items, its core earnings for the quarter stood at US$270.8 million, a sharp turnaround from the US$616.3 million loss in the year-ago period. Revenue grew 7.1 per cent to US$3.5 billion.
On a full-year basis, Sea narrowed its net loss by 18.9 per cent to US$1.7 billion. Revenue grew 25.1 per cent to US$12.4 billion.
The results stunned analysts, whose consensus expectation was a Q4 loss of US$433 million. At least three research houses have since raised their target prices on the stock, with “buy” or “add” calls, while investors sent Sea’s shares up 23.6 per cent to a six-month high of US$81.22 on Mar 7. They closed last Friday at US$73.45, up 38.6 per cent for the year.
A big surprise was that despite the slowing global economy, e-commerce arm Shopee saw strong Q4 revenue growth of 31.8 per cent to US$2.1 billion. The segment reported positive adjusted earnings before interest, taxes, depreciation and amortisation (Ebitda) of US$196.1 million, versus a US$877.7 million loss in the year-ago period.
The fintech business, SeaMoney, also delivered a positive adjusted Ebitda of US$75.6 million in Q4, while nearly doubling its revenue to US$380.2 million.
Behind these glowing numbers were cost cuts that were as ruthless as they were impressive. The company slashed its Q4 sales and marketing expenses by 61.2 per cent to US$473.6 million, while research and development expenses were down 14.8 per cent to US$244.2 million. It has undertaken multiple rounds of layoffs, the most recent one affecting under 500 staff in Indonesia.
Raising the bar
Expectations for Sea’s FY2023 bottomline are now much higher than before. UOB Kay Hian (UOBKH), for instance, thinks Sea could record as much as US$935 million in net profit in FY2023, a stark reversal of the US$1.6 billion loss the research house had previously forecasted. It upgraded its call on Sea to a “buy” on Mar 8, while raising its target price 60.5 per cent to US$94.34.
CGS-CIMB similarly forecasts a US$984 million net profit for Sea in FY2023, with the company now “on a much stronger footing” to capture growth. It raised its target price by 23.5 per cent to US$105, while reiterating its “add” call.
Maybank more conservatively expects an adjusted Ebitda breakeven for Sea in FY2023, with a core net loss of US$1.2 billion. It sees subsequent revenue growth producing a US$469 million core net profit in FY2025. Maybank raised its target price 30 per cent to US$105, while maintaining a “buy” call.
The analysts are optimistic about Sea’s e-commerce growth, as well as its ambitions in digital banking. Sea’s profitability would be driven by “strong cost efficiency and higher transaction fees in its e-commerce segment; higher contributions from its value-added service in logistics and higher contributions from its digital financial services segment”, the UOBKH report said.
Yet, Sea has to contend with significant headwinds.
One longstanding concern is the declining profitability of the gaming business. Garena’s Q4 revenue was down 32.9 per cent to US$948.9 million, while adjusted Ebitda fell 57.1 per cent to US$258.2 million. This is a far cry from the booming growth produced by Sea’s hit game Free Fire during pandemic times.
Sea’s 2020 acquisition of Phoenix Labs for US$150 million has not appeared to bear much fruit. Sea is mulling a sale of the Canadian indie game developer, according to January media reports. There are no signs yet that Sea has found its next gaming cash cow.
While Wang Yanjun, Sea’s chief corporate officer, flagged that Garena’s profit margin is still high compared with the industry average, its declining growth remains an overhang.
Another potential challenge will be on the digital banking front. Compared with peer GXS, Sea’s Singapore digital banking venture MariBank has been quiet. There are no hints as to what approach the company will take, but if it is to compete with GXS and Trust, it may need to be prepared to spend on promotional interest rates and other goodies to draw depositors.
On the e-commerce front, the impact of inflation on consumer spending is another potential downer. Shopee’s Q4 gross merchandise value dipped 1.1 per cent to US$18 billion and gross orders fell 15 per cent to 1.7 billion.
As Shopee reduces its spend on promotions, consumers could tighten their belts further. And, the growing footprint of e-commerce contender TikTok Shop and potential entry of Pinduoduo’s Temu into South-east Asia will be competitive risk factors to watch.
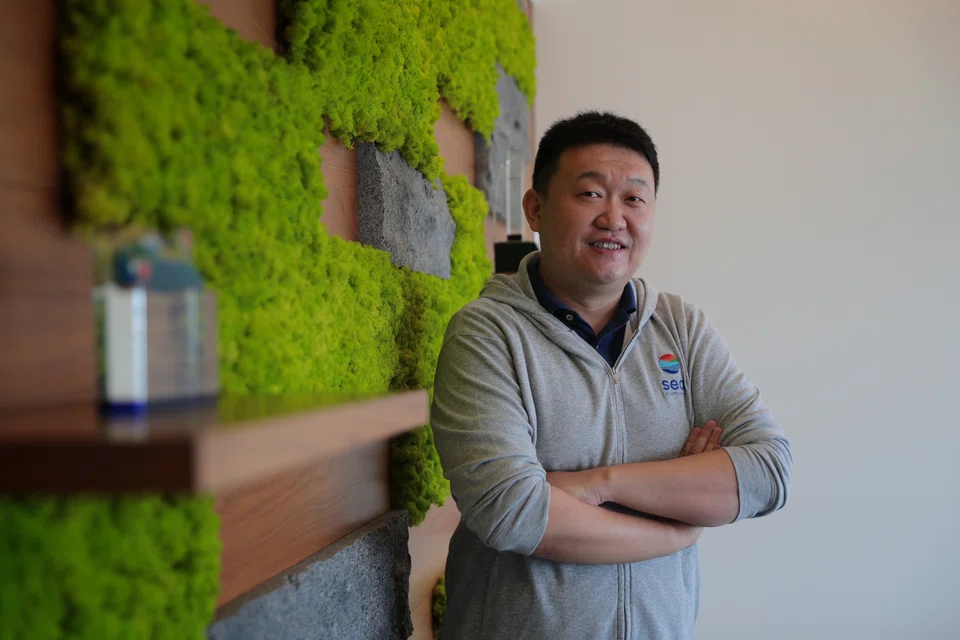
Sea recognises these headwinds. In its earnings call, CEO Forrest Li struck a note of caution on “near-term fluctuations” due to macro factors. That said, he is “highly confident in the long-term growth potential of our markets”.
Some bearish observers, such as Oshadhi Kumarasiri of LightStream Research, think the market may not stomach such fluctuations well – especially if Sea returns to losses.
“Turning unprofitable yet again could be a hard thing to swallow, even for those firmly believing in Shopee. Therefore, Sea could fall a lot more than the previous bottom next time it falls,” he wrote in a report on research portal Smartkarma.
Not all investors will be in Sea for the long haul.
TRENDING NOW

Government to bring forward raising of retirement age, give employers more financial support to create flexi-load jobs

Former minister Maliki Osman, Revolut chairman join Asia Gulf Holdings advisory board

Is Manila Asia’s new dining hot spot?
Simba at risk of losing operating licence over spectrum misuse

