

Beam Mobility’s ongoing fraud case a reminder that investors face reputational, fiduciary duty risks
Funds that had taken seats on the startup’s board will face more than just scrutiny from investors
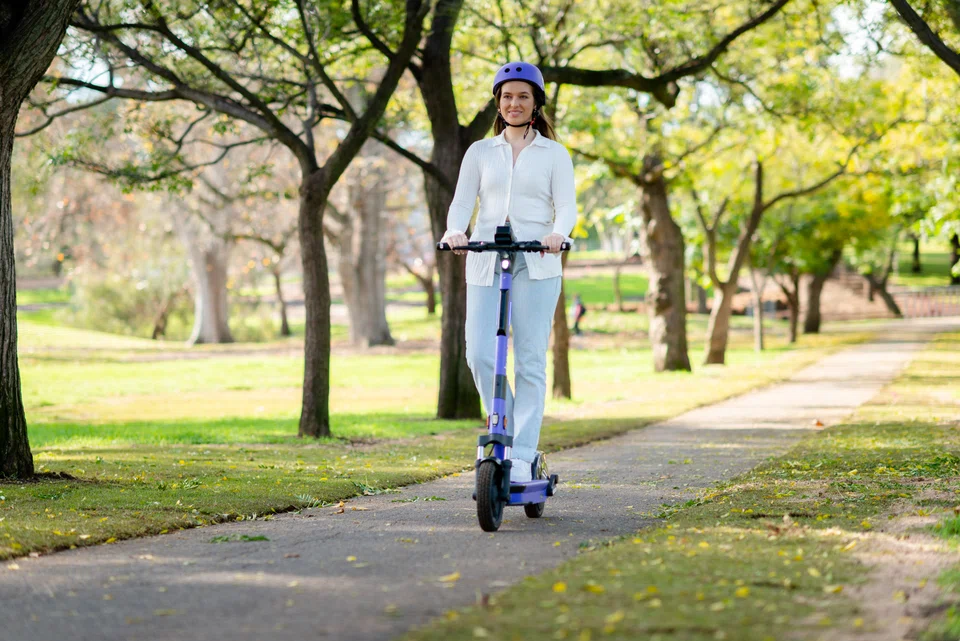
SINGAPORE-BASED startup Beam Mobility, an e-scooter-sharing service provider, has managed to attract a number of marquee investors since its launch in 2018.
On its capitalisation table – a spreadsheet that details who owns what percentage of a startup – are renowned names such as US venture capital (VC) firm 500 Global, SMRT’s Momentum Ventures Capital, and the Singapore Economic Development Board’s investment arm, EDBI.
But these investors’ reputations may be dragged down as Beam is accused of defrauding several town councils in Australia and New Zealand.
The company had secured contracts with these town councils to provide e-scooters for rent within their districts. These contracts came with a cap on the number of e-scooters, based on what the town councils deemed as an amount that would not impact safety in their districts. Each mobility device was also taxed by the councils.
Leaked whistleblower documents, however, alleged that Beam was circumventing a third-party tracking platform to count the number of devices operating in some districts.
The company is alleged to have put more than the allowed number of mobility devices in these districts. The excess devices were reported as inoperative to the third-party platform, but users were reportedly able to continue renting these “phantom” e-scooters.
Market watchers said that this could have been a quick way to raise supply and boost revenue.
“Our intention was to ensure there (was) an adequate number of usable vehicles available to the public within the limits of the agreed terms with councils,” Beam explained in a statement.
Termination of contracts
Action against the startup, though, has been swift.
The allegedly defrauded town councils have moved to terminate their contracts, and some have also referred Beam to the authorities.
Exceeding the cap on the allowed number of e-scooters on the streets is not just a matter of tax leakage, but also of safety, the town councils said.
While Beam will have to handle the fallout from its actions, its investors must also look at the potential reputational risks and issues regarding the discharge of their fiduciary duties.
Notably, investors such as 500 Global, Momentum Ventures Capital and EDBI had not taken up board seats at Beam. They could just write off this investment, and chalk it up to the failure rate that is part and parcel of being a VC fund.
But there will still be some investor scrutiny over whether the due diligence carried out was sufficient.
The due diligence in funding deals with startups, especially those in the early stage, is done on a much shorter time scale compared to that for an initial public offering.
It is also often limited to key issues for incoming investors, such as the share register, intellectual property rights and assets that the startup has.
Such due diligence reports typically take about two to four weeks, said Joel Shen, partner at law firm Withers KhattarWong.
The process for Beam would have ultimately touched on its assets, including the number of e-scooters it had. If the startup had lied to investors during the due diligence process, investors would have recourse to sue the company for a breach of warranty.
“The fund manager would be able to recoup any damages it suffers as a result of the warranty breach, including for reputational fallout,” said Shen.
While there are typically clauses to limit a company’s liability during a transaction, the limitations do not apply in the event of fraud. “If all the boxes are ticked, the fund manager can simply say, well, it’s tough luck, we were all the victims of fraud,” said Shen.
Fund managers would have to prove to investors that the due diligence done was adequate, especially if they were the ones leading the funding rounds and securing board seats.
Funds that have taken board seats at Beam include big names such as Peak XV Partners (formerly Sequoia Capital South-east Asia and India) and South Korea private equity firm Affirma Capital.
These funds in particular will face more than just scrutiny from investors, as their named directors would have to prove that they had discharged their fiduciary duties as well.
This is a key risk of taking on a directorship, which requires one to act in the best interest of the company. While VCs take board seats to participate in discussions and have certain rights or control in the company, they might not consider the implications of taking on such a role.
Extreme example
The big question for the directors would be whether they should have known what Beam was doing. The law in Singapore imposes an obligation on directors to act reasonably, noted Shen, with the directors needing to answer the question of whether they had done enough to discharge their duty under the law.
“It is no defence for a director to say, I didn’t know, or that I’m only looking out for the interest of the guy who appointed me,” said Shen.
For Peak XV, the Beam incident comes after its saga with Zilingo, where an accounting probe led investors to suspend co-founder and CEO Ankiti Bose, before her eventual resignation. The tech unicorn filed for liquidation in January 2023.
An extreme example of what investors could do is to force a fund to close down if they deem it too toxic or not worth the effort to save. However, this is unlikely to happen in Beam’s case. Instead, Peak XV will likely take another reputational hit.
The Business Times has reached out to Affirma Capital for comments, while Peak XV declined to comment on Beam.






