Enterprise demand drives WeWork growth in Singapore
Benjamin Cher
ENTERPRISE customers are driving demand for WeWork offices in Singapore and South-east Asia, making up 46 per cent of physical memberships in South-east Asia.
And this demand from larger corporations is showing no signs of slowing, said Balder Tol, general manager of WeWork Australia and South-east Asia.
“The interest and enquiries that we get have continued to outpace our initial forecast. As of today, we have 97 per cent of our Q2 FY2022 revenue forecast in the mid-range already committed. We have 70 per cent of our Q3 FY2022 and Q4 FY2022 forecasts already committed for this year,” he added.
Singapore has recorded a 13 per cent increase from Hong Kong-based organisations relocating to the Republic, according to Tol, and international enterprises are basing their regional headquarters in Singapore, and utilising WeWork in a hub-and-spoke model, in which Singapore serves as a hub from which to reach the rest of South-East Asia.
This demand has pushed WeWork into raising its revenue forecast for Q2 FY2022 to between US$800 million and US$825 million, up from US$775 million.
In Q1 FY2022 ended Mar 31, there was a 60 per cent year-on-year (y-o-y) increase in desk sales in Singapore, which pushed occupancy up 18 percentage points y-o-y. In South-east Asia, desk sales rose 70 per cent y-o-y, with occupancy rising 20 percentage points y-o-y. Revenue for Singapore rose 49 per cent y-o-y, while that for South-east Asia rose 39 per cent y-o-y.
Singapore is in a group of cities that are the top contributors to WeWork’s revenue, the other cities being London, Paris and Seoul. The group averages 83 per cent occupancy, and building margins for these cities are 28 per cent, said Tol on the earnings before interest, taxes, depreciation and amortisation. Singapore is therefore among WeWork’s top-performing markets.
Co-working space accounts for about 5.5 per cent of Grade-A office spaces in the Central Business District, said Cushman & Wakefield (C&W) last December. Major operators WeWork, JustCo and IWG dominate the arena in Singapore, jointly taking more than half the market share, C&W said.
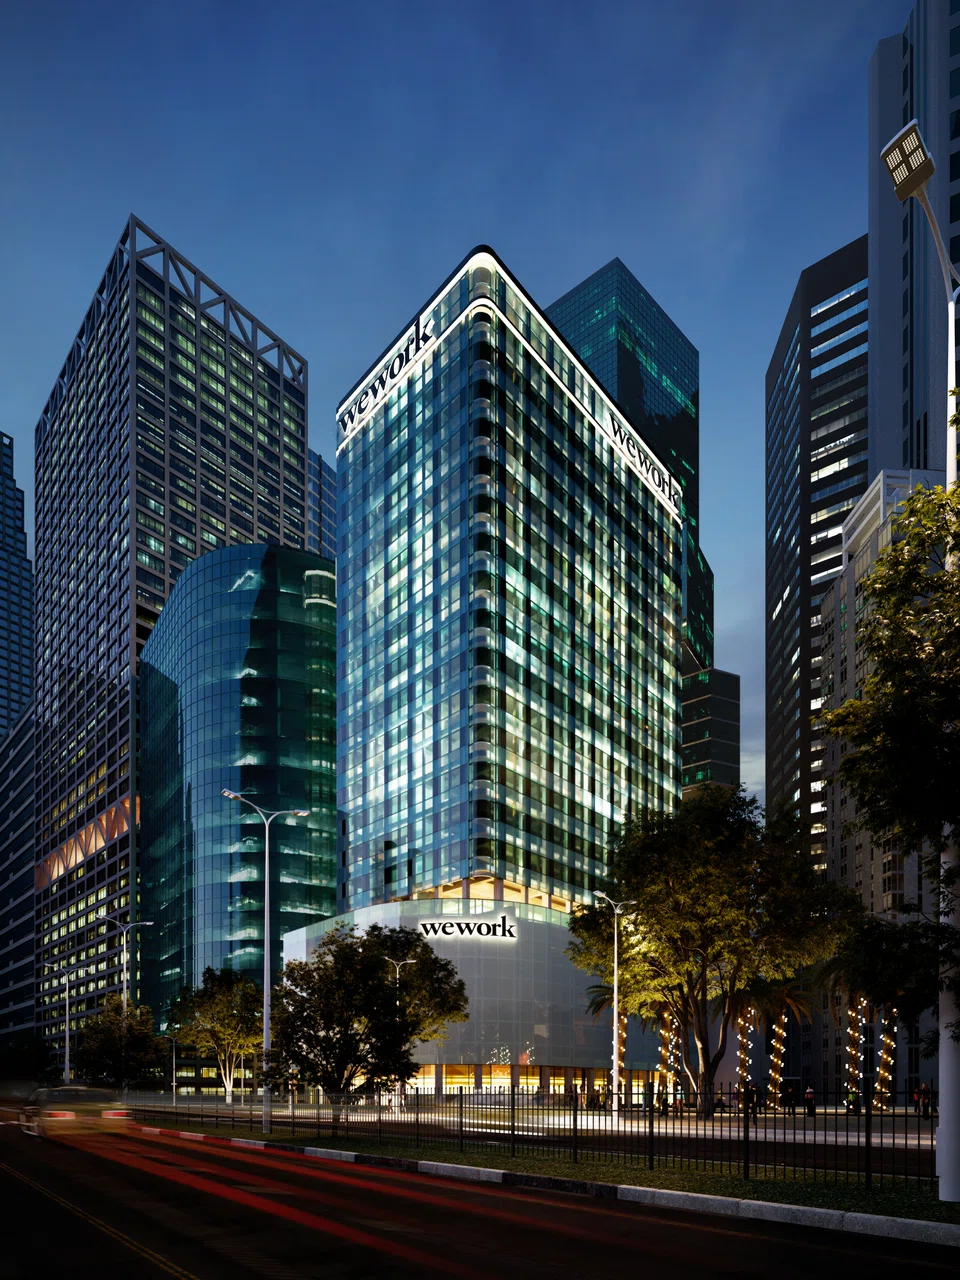
The flagship WeWork property for the region is 21 Collyer Quay, a 21-storey Grade A office building with over 220,000 sq ft of space. It is set to open in 3 phases, with the first phase in July; a third of the available space has already been committed. Risk management and advisory company Willis Tower Watson is a key tenant in this new location, where 80 per cent of the space has been designed for single tenancy on each floor. The remaining 20 per cent has been allocated for traditional co-working environments.
In the second phase, all the facilities will open, including a wellness centre run by an external wellness partner. The final phase opens in Q1 2023.
Tol said: “In Singapore, we see increased demand from enterprise organisations; we see at the moment across our entire portfolio we are out of enterprise space within our inventory. 21 Collyer Quay comes online at a timely moment because if we don’t have this inventory, I would have to say no to the growth of our enterprise opportunity.”
WeWork competitor Industrious recently made inroads into Singapore through an acquisition of local co-working operator The Great Room. Tol described such moves as a positive development for the market, but doesn’t see acquisitions as a growth strategy for WeWork.
The market has space for operators to slice the pie, he said, and added that there isn’t a one-size-fits-all solution for every organisation. WeWork’s edge would be in its global footprint, giving it different data points that help build experiences that its customers would like. Its edge also comes in the small things — like customers being recognised by WeWork staff or being addressed by their first names, and the speed at which customers can start using WeWork spaces.
“It is really the understanding of our customers and continuing to provide experiences that feel customised to their needs, (which) is unique to WeWork in the day-to-day operations. That speed-to-market and agility continues to be a great value proposition compared to some of the local players,” noted Tol.