

Exclusions in new protections for platform workers could lead to age discrimination, arbitrage
Rules mean better safeguards for on-demand employees, but also contain loopholes
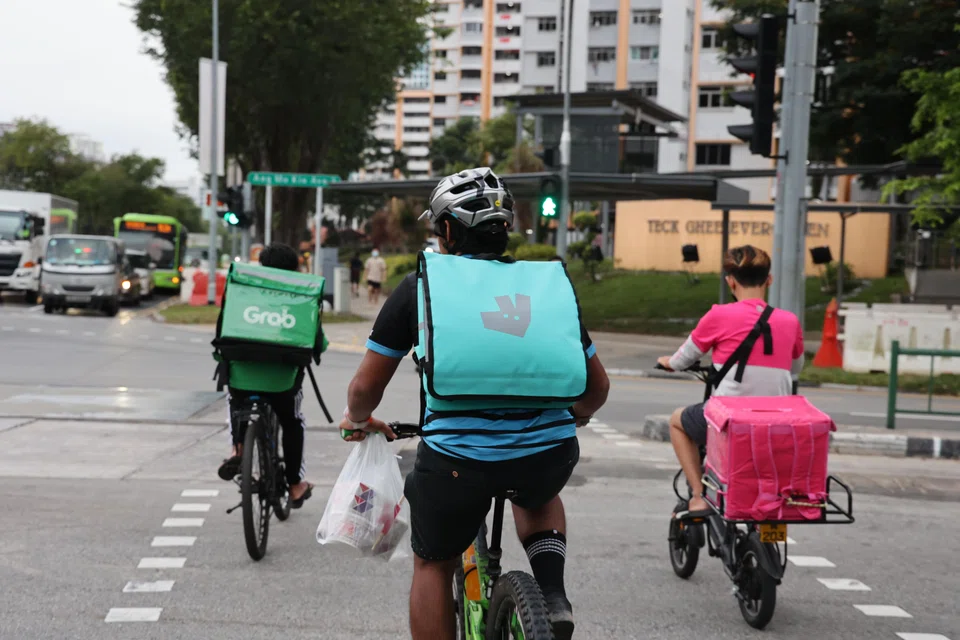
SINGAPORE’S extension of employee-like protections for platform workers was welcomed by industry watchers, who said this closes gaps in voluntary provisions by the likes of Grab and foodpanda.
Nevertheless, some also flagged the possibility that platforms might engage in regulatory arbitrage and age discrimination – given exclusions for street-hail taxi rides as well as the initial batch of older workers.
There were also calls for implementation to be sooner than the planned rollout in the later part of 2024, at the earliest.
The Republic last week announced that platform workers – comprising ride-hailing drivers and on-demand delivery persons – will be included in the Central Provident Fund (CPF) scheme, with an opt-in choice for those aged 30 and over as of the first year of implementation.
In addition, platforms will be required to provide work injury coverage aligned with that of employees under the Work Injury Compensation Act (Wica). Insurers will need to come up with new offerings under the Wica framework.
Regulatory arbitrage
Industry watchers generally saw the CPF and work injury measures as positives. While some platforms do provide some form of insurance for their workers, coverage is incomplete. Pegging worker protections to Wica will also ensure any disputes can be resolved by authorities under a legal framework with an established mechanism, as opposed to an insurer’s assessment.
Following the announcement of the new rules, the platform companies voiced some dissatisfaction over the exclusion of street-hail taxis as well as logistics companies that use self-employed delivery persons on an ad-hoc basis.
“I’m not sure if it’s a good idea to leave them out. While it’s true there are obvious differences in business models, doing so is dangerous as it creates the potential for arbitrage,” said Ian Lim, head of employment for TSMP Law.
Regulatory arbitrage is a practice that sees companies capitalise on differences between certain sets of laws, to choose the most favourable path. For instance, taxi companies could prioritise street-hail over ride-hailing – given that the former is not subject to the new rules.
“The market has spoken, there is definitely demand for ride-hailing services. If ride-hailing becomes less available as a result of this, it will be at the consumers’ cost,” Lim added. He believes there should still be a regime to cater to street-hail and logistics delivery workers, rather than leave them out entirely.
Under the principle of regulatory equality, the same kind of economic activity should be regulated the same way, said Walter Theseira, associate professor of economics at the Singapore University of Social Sciences (SUSS).
Singapore’s approach is to apply a test of whether the platforms have management control over the workers. Although street hailing and ride hailing have the same economic activity, the test results in only the latter being regulated as platform work.
Theseira said any resulting regulatory arbitrage moves could be “very costly and inefficient”.
“It’s (workers’ and platforms’) right to do what they think is best, but it will have consequences for market functioning,” he added.
Amerson Lin, co-founder and chief executive at Gigacover, an insurtech company focusing on freelancers, believes logistics workers and street-hail taxi drivers face similar risks and need just as much protection.
Including these segments will also make the insurance pool larger, which will mean lower premiums and even more stable portfolio performance.
While the Wica standard is a familiar foundation to build on, the regular Wica is built upon a much larger base covering all local and foreign employees in Singapore. In contrast, a Wica-like product for platform workers would cover a much smaller base of only 70,000 to 80,000 workers. As a result, similar payout amounts, such as the S$45,000 medical expense reimbursement, will likely cost more, Lin said.
Age discrimination
For older workers, fair treatment could also be a big concern. Those who choose not to opt in for CPF will not be entitled to their employer’s contribution, which is currently pegged at 17 per cent of wages.
“This could lead to workers receiving different total wages for the same work,” SUSS’ Theseira said, questioning if older workers will instead be given the employer’s contribution in cash.
“The other concern with fair treatment is that CPF contributions decline with age. This may make sense for traditional employment, where it is an implicit discount to wages to keep older workers more employable. But for platform work, it doesn’t make any sense that the total wage for the same job declines with age,” he added.
Any total wage differential could lead to discrimination by platforms as well, if they prefer to assign non-CPF contributing workers to the job. Theseira noted that this must be regulated as well.
The age threshold is another concern. While the opt-in option creates room for those 30 and above who have structured their financial affairs in a way that does not require CPF assistance, not all such workers may have sorted out their housing needs, TSMP’s Lim said. “Some may still be unmarried or staying with their parents past the age of 30, and may only need CPF assistance later. As such, it might be worth looking at raising the opt-in threshold to those aged 35, or even 40, and above,” he said.
Gigacover’s Lin also flagged that making the CPF scheme an opt-in choice for those above 30 may result in many choosing not to participate. Allowing them to contribute at a reduced rate might be a better option instead.
More to be ironed out
While the new protections have yet to deal with issues of paid time off, sickness and hospitalisation leave, and benefits, observers agreed that regulations need not be perfect to be implemented.
“Having taken care of long-term social protection through CPF and injury, perhaps the matter of sickness and hospitalisation leave and benefits can be looked at down the road,” said Theseira.
But some think the basic protections should start sooner. Instead of waiting for more consultations and consensus, Lin said the government should start the rollout earlier in 2023, with a lower tier of protection of, perhaps, half the protection payout amounts, to test market response. Subsidies or incentives could also be considered to ease the rollout or spur market adoption.
“The goal should be to pilot as soon as possible, learn quickly and adjust,” he added.
Wong Wai Meng, chair of industry body SGTech, recognises that the initial implementation and transition process would require significant resources and time to be expended by platforms.
“We believe it would be beneficial to establish a regular dialogue between the policymakers and the industry to ease the build-up of the co-contribution for CPF,” he said.
TRENDING NOW

South-east Asia has lost Nvidia’s best salesman

Higher rates, weaker spending: Is the Philippines entering stagflation?

Who is Leo KoGuan, the Singapore-based billionaire backing Nvidia’s Jensen Huang?

Demand, tech capabilities position Apac and AI as Skyscanner’s next growth frontiers: CEO Bryan Batista

