

Trust Bank’s deposits more than double to S$3 billion in H1 2024, customer base hits 806,000
The digital bank is confident of breaking even by end-2025; it targets unmet needs like the emerging affluent segment
CUSTOMER deposits at Trust Bank more than doubled to S$3 billion in the first half of 2024, from S$1.2 billion in the same period last year.
The number of customers at the Singapore digital bank also hit 806,000 in the same period, up from 577,000 a year earlier, said Dwaipayan Sadhu, chief executive of Trust Bank.
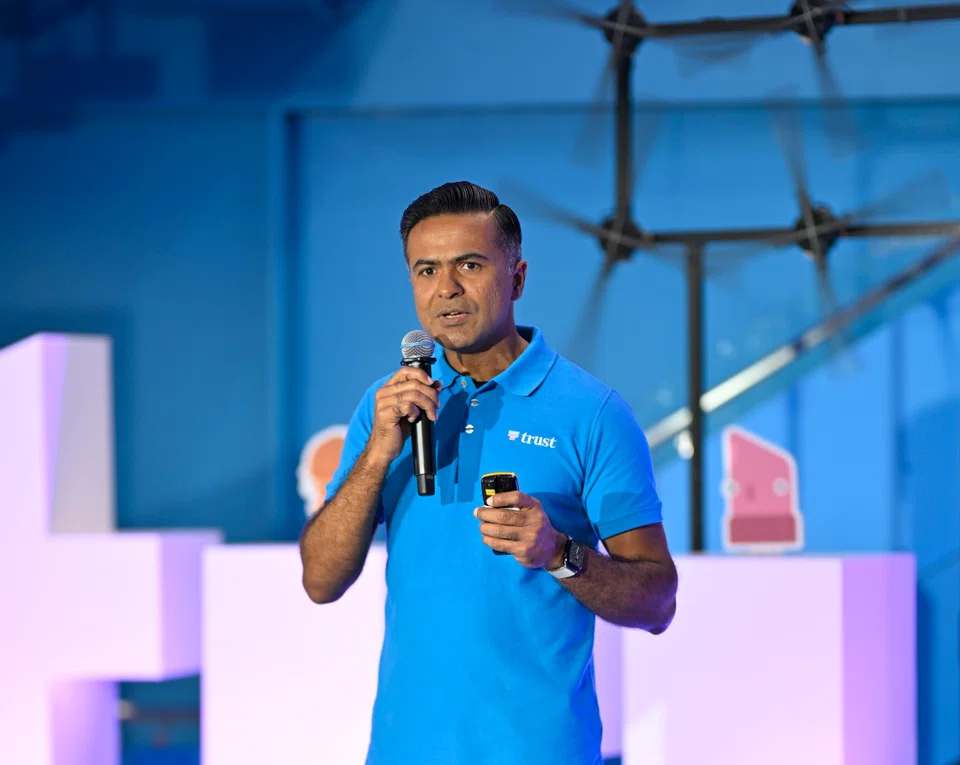
“We aim to be the fourth-largest retail bank by customer numbers by the end of this year, and we believe we are well on track to getting there,” he said at a media briefing and launch of a new cashback card on Thursday (Aug 29).
Speaking on the sidelines of the briefing, Sadhu said that the bank is still intending to break even some time towards the end of 2025.
“Our revenue growth is still three times of last year, and we are achieving it at almost flat cost growth, which really gives us a lot of confidence for our trajectory going forward,” he pointed out.
Sadhu did not provide the exact revenue figure, but noted that costs inched up 1 per cent on year in H1 2024.
He attributed the revenue growth to Trust’s scalability, where its technology lets the bank grow without adding more costs.
Meanwhile, Sadhu noted that the bank’s loan proposition also got off to a “really strong start”.
Total customer loans and advances reached S$486 million in 2024, from S$157 million a year earlier.
In July 2024, it also disbursed more than 12,000 loans.
Yet, Trust’s net loss widened to S$128.4 million for the full year ended Dec 31, 2023, from S$124.7 million a year earlier.
In FY2023, income before operating expenses rose to S$39.1 million from S$3 million.
But costs – including staff costs, finance costs for lease and operating and administrative expenses – were up 21.2 per cent on year.
Sadhu noted that as a digital bank, Trust would have had a period of set-up, then a period of investments, and subsequently a period where it can engage customers to grow and build products.
Its customers have been engaging with the bank actively. For example, customers on average use their credit cards 21 times each month.
Speaking on funding costs, Sadhu said the bank tries to maintain sustainable interest rates. “We do not want to be in a situation where we are offering unsustainable promotional rates, which we cannot sustain for a long time,” he explained.
Trust currently offers a base interest rate of 1.25 per cent for its deposit accounts up to S$500,000.
Customers can earn up to 1 per cent in additional bonus interest if they make at least five eligible card transactions per month; another 0.5 per cent bonus interest if they maintain an average daily balance of S$100,000; and another 0.75 per cent if they credit their salary.
Trust has a “healthy margin”, where its total cost of deposit is lower than the returns it gets from deploying them, Sadhu said. “We believe we have strong advantages in everything else – proposition and experience – so we don’t necessarily need to be the highest in the market.”
Sadhu also noted Trust’s relatively low cost of acquisition.
Many of Trust’s early customers joined as it was integrated into NTUC’s ecosystem, while its value proposition meant that customers joined the bank “almost organically”, he said.
Some 70 per cent of its clients also joined via customer referrals, which Sadhu said is “far cheaper than advertising or marketing”.
Sadhu said that Singapore’s “fairly deep and attractive banking market” has created different opportunities for Trust, which aims to grow its products and services to cater to unmet needs.
This includes targeting the underserved emerging affluent segment, which led to the launch of Trust+ – the bank’s segmented offering for emerging affluent customers.
“Banks offer a lot of attractive products and services at the high end, but the emerging affluent segment is underserved, and clients essentially feel they’re stuck in between. They are not getting the attention that they feel they deserve,” he pointed out.
Trust – a 60-40 joint venture between Standard Chartered and NTUC – is present more in the mass and mass affluent space, which complements StanChart’s strength in the affluent space, Sadhu said.
The take-up of Trust+ has gotten off to a “very good start”, Sadhu noted. He added that a lot of the growth to hit the S$3 billion in customer deposits had come from Trust+ customers.
Meanwhile, he also highlighted Trust’s strength in the travel payments space, given that its cards carry no foreign exchange fees.






