Wising up to hidden fees
Transferwise disrupted the traditional money transfer business with transparent fees and zero markup on the exchange rate. But to be viable, chief executive and co-founder Kristo Kaarmann makes clear, "everything we do must break even".
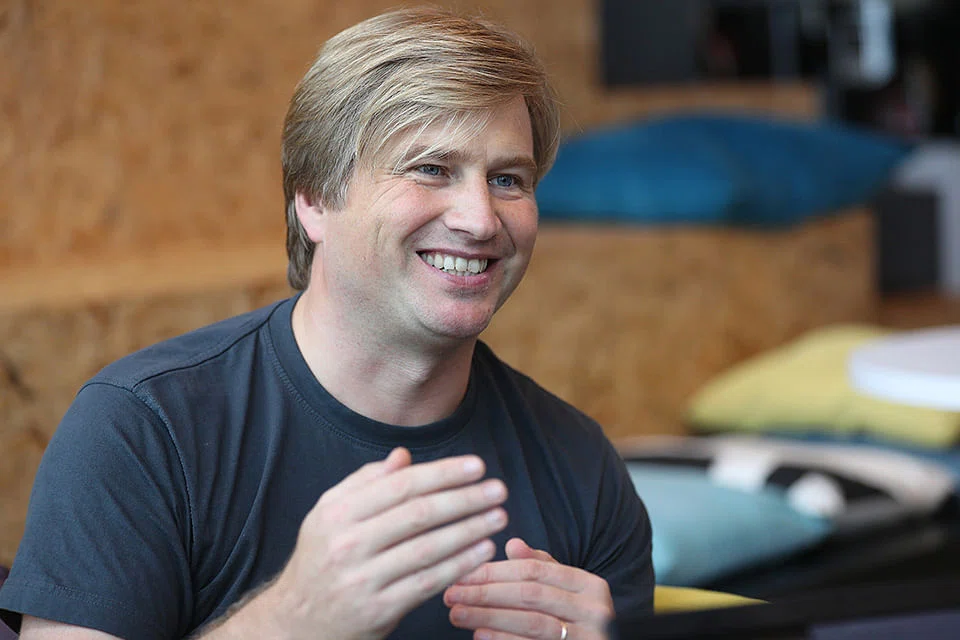
KRISTO Kaarmann, chief executive of payments fintech Transferwise, celebrates Christmas a little differently from most Europeans.
Every December, the 40-year-old Estonian embarks on a month-long road trip around Africa on "Kotilda" - his 15-year-old motorcycle. This year, he rode Kotilda from Morocco in the North towards the Sahara desert, down through the jungles to South Africa, before heading east to Tanzania, Kenya and finally Ethiopia, he tells The Business Times.
At the end of his trip, Mr Kaarmann parks Kotilda at the nearest garage he can find, "stars" her location on Google Maps, and leaves with some hope of a reunion next December. The odds of this yearly gamble have played in his favour for five straight years.
"It always needs a bit of work to get the motorcycle started again, so I've become quite good at motorcycle repairs over the years," he jokes.
Mr Kaarmann's live-and-let-live nature carries through to his professional life. He tells BT he had no inkling of Transferwise's feasibility when he founded the business in 2011.
Transferwise had started as a "little experiment using spreadsheets" with co-founder and fellow Estonian Taavet Hinrikus, born out of an attempt to dodge hefty fees that big banks typically charge for international money transfers, he says.
"If it didn't work out, we'd simply go back to our day jobs.
"We never dreamed of running a company, we were just two guys who faced problems moving money and thought we found a cheaper and faster solution," adds Mr Kaarmann, who was then a consultant at Deloitte.
The duo's little experiment ballooned into a US$3.5 billion digital remittance business over the past decade, claiming over seven million users - individuals and small businesses - who collectively move some £4 billion pounds (S$7.17 billion) around the world every month.
Following Transferwise's expansion in Europe and the United States, the London-headquartered firm set up its Asia-Pacific headquarters in Singapore in 2017 to deepen its regional presence.
In 2019, the firm recorded a 63 per cent year-on-year jump in the volume of money sent to and from Asia.
"We started Transferwise from a personal problem and quickly realised that loads of other people around the world had the same problem," he says.
Entrepreneurial journey
Having worked with European banks during his consulting stint in London, Mr Kaarmann admits he is always a little embarrassed to share his entrepreneurial journey.
He tells BT: "I thought I was rather well-educated before (I founded) Transferwise. I had a master's degree, I had worked in finance, but I didn't know much about payments till I lost a fair bit of money."
Back in 2008, Mr Kaarmann had remitted his salary - in British pounds - to his euro bank account in Estonia via HSBC's services. He received 500 euros (S$796.90) less than expected when the funds were credited one week later - a "significant amount" of money at that time.
"I did some research and realised the 'Google' exchange rate I had used to convert pounds to euros was not the same rate my bank used. While my bank did tell me there was a £12 (S$20.87) upfront fee, I wasn't aware that their exchange rate included a 5 per cent markup," he says.
Major bank providers tend to impose a 4 to 6 per cent FX markup on top of a flat transaction fee.
Rerouting money
In the age of rapid digitalisation, there is "no reason" why money cannot be sent as cheaply - and as instantly - as an e-mail or a text, says Mr Kaarmann.
While his challenge then was to move money to Estonia more cheaply, Mr Hinrikus had the exact opposite problem - he needed to send money to London from Estonia.
Mr Kaarmann says: "Since I was getting paid in pounds in London, I transferred my pounds to (Mr Hinrikus') UK bank account, which costs nothing. And then we looked at the mid-market exchange rate and he transferred the equivalent amount of euros to my bank account in Estonia.
"This arrangement was instant and free. I didn't have to use the bank's services so they couldn't charge me in secretive ways, and I didn't have to wait a week to receive my money."
In January 2011, the founders released a blog post on TechCrunch to offer similar transfer services between the UK and the eurozone. They received £2,000 - to be remitted to France - some 15 minutes after news of their services went live.
"There were people who trusted us with their money on the day we launched, which was surprising to us because it was 2011 - PayPal was the only other fintech that existed then.
"I also received hundreds of e-mails from strangers telling me they did a similar re-routing (money transfer) method with their friends, but never turned it into a viable business or product," says Mr Kaarmann, noting that the "overwhelming" response was testament of broad demand for cheaper international transfers.
By its sixth month of operations, Transferwise was executing some 800 transactions a week. The momentum has continued to this day - the firm now moves billions of dollars across 59 countries every month. In 2019, Transferwise saw a 84 per cent year-on-year rise in volume of transactions globally.
Betting on transparency
Providing its users with a transparent fee breakdown and the mid-market exchange rate has been the crux of Transferwise's success over the years, says Mr Kaarmann, albeit a "very long shot" at the beginning.
Their decision to banish hidden fees came at a time where bank fees and FX markups were relatively opaque in the early 2010s.
Mr Kaarmann tells BT: "It may have looked like we were more expensive than the banks back then. But we believe that if we let people know how much they're paying with Transferwise, there will ultimately be (deeper) comparisons and banks will be forced to compete. The reason why international payments are so expensive in the first place is because our society was tolerant of hidden fees."
Transferwise claims its fees are, on average, 12 times cheaper than banks in Singapore. Globally, the firm saves over 1.5 billion euros (S$2.4 million) in hidden fees for its customers every year.
A quick calculation by BT on the Transferwise platform at 3pm on March 5 showed that a S$1,000 remittance to the UK amounted to £557.64, inclusive of S$4.88 in upfront transaction fees. In Singapore, bank fees and FX markups can cost between S$20 to S$40 per transfer.
Leveraging data for speed
Cheaper fees aside, about 20 per cent of Transferwise's cross-border transactions are instant - that is, under 20 seconds.
"This is only possible because we use a lot of data to optimise the process," says Mr Kaarmann, adding that the firm relies heavily on data analytics to generate key insights on the various currency routes and customer behaviour.
In the month of November 2019 alone, more than half of Transferwise's 2,000 employees globally had used the firm's analytical platform.
"We need data to find out which particular currency route is slow, and why it's slow. These are all questions that we can answer only by analysing data. Everyone in Transferwise has to be very efficient with data, otherwise it's hard to do our job because we serve millions of customers," he says.
Autonomous teams
He tells BT that the rate at which Transferwise has expanded globally - 14 offices and over 2,000 employees in less than 10 years - would not have been possible if his people had waited for him to call the shots.
Employees operate in "small, relatively independent" teams that are responsible for various operations within the firm, he says.
"For instance, if we're building a new feature, or solving a customer problem, we'll let the respective teams in charge hire the people they need and make their own business decisions. They don't depend on me, which is why they can move faster. Having autonomous teams has given us a lot more bandwidth to accomplish more without the need for forceful management structures."
He notes that it also introduces healthy competition within the firm.
Each team has to "prove" to other teams that it is making a tangible contribution to the business. This could be in terms of dollar-cost savings within a particular time frame, says Mr Kaarmann. "We might have some teams that are doing a great job (enabling) faster transfers, and some teams that have found new ways to further diminish costs."
Transferwise is currently working towards further price drops in more markets including Japan, Pakistan and Sri Lanka, he notes.
Growing its bottom line
With all that said, topline growth and global expansion means little if there are no profits to show.
"Everything we do has to at least break even. The financial mechanics have to work, otherwise it won't be a viable solution in the long term," says Mr Kaarmann.
TransferWise is one of the few profitable fintechs among its peers, having maintained a positive bottom line in the last three years. The firm's pre-tax profit rose 29 per cent to £10.1 million for the financial year ended March 31, 2019, while revenue jumped 53 per cent to £179.1 million.
Mr Kaarmann tells BT that Transferwise's fee structure and conservative marketing budget - coupled with rising demand from small businesses - has helped lift profits and keep expenses at bay.
"I think a big reason why some companies in this industry are not profitable is because they have built a product that their customers are not paying for, or not paying enough for," he says.
Transferwise for banks
The firm's growing dominance in the payments industry has drawn mixed reactions from incumbents and challenger banks - some have ramped up their existing offerings, while others have chosen to team up with Transferwise.
The firm avails its API (application programming interface) platforms to businesses to help streamline their workflows.
In 2018, BPCE Group, the second largest bank in France, integrated Transferwise's API into its mobile banking app to serve over 15 million customers. Other partnerships include Estonian financial services firm LHV as well as digital banks Monzo in the UK and Up! in Australia.
While traditional banks may charge hefty fees for international transfers, they may not necessarily reap profits due to the nature of their internal systems, says Mr Kaarmann.
As an example, when Transferwise expanded to Hungary five years ago, the team was met with "unprecedented" take-up in the early stages.
He later found out that bank tellers at AXA Bank Hungary - a small local bank that has since been sold - had recommended Transferwise to customers who needed international payments services, and further assisted them with their Transferwise account set-up.
Mr Kaarmann tells BT: "Back then, when the bank's customers needed to make international payments, they had to visit a branch, fill up a form and hand it over to the bank teller to manually key in their details into the system. The whole process was slow so the bank had to charge their customers quite a bit. At the end of the day, both the bank and their customers didn't like the system.
"That was when we started opening up our platform, through APIs, so that banks could offer our services to their own customers conveniently from within their own banking apps."
More to come
Even after a decade in the payments scene, Mr Kaarmann believes that Transferwise is still at the starting line. "We still have a lot to do. We're only moving maybe 1 per cent of global volumes," he says.
There are upcoming plans to enable cross-border remittances from Indonesia and launch the Transferwise multi-currency account and debit card in Japan.
Mr Kaarmann attributes part of his entrepreneurial spirit to his upbringing in Estonia, a northern European country bordering Russia. When Estonia broke away from the Soviet Union in 1991, there was no "real economy" left, so people had to build businesses from scratch, he recalls.
"Growing up, I saw lots of young people starting banks, restaurants, mechanic shops, factories and so on. There were no 'real' employers so everyone was kind of an entrepreneur. If you had two hands, you could start your own business."
KRISTO KAARMANN
CEO and co-founder TransferWise
1980: Born in Estonia
EDUCATION
Master's Degree (2006) in Mathematics and Computer Science from University of Tartu, Estonia
CAREER HIGHLIGHTS
Prior to launching TransferWise: Worked as a management consultant with Deloitte Consulting and PricewaterhouseCoopers. He worked with European banks and insurers to modernise their processes and systems.
2011: Launched Transferwise with co-founder and friend Taavet Hinrikus
2015: TransferWise iOS App is named Most Innovative App 2015 by Apple (UK, Germany and France)
2015: Selected as one of the World Economic Forum's Technology Pioneers 2015
2016: TransferWise receives investing from fundraising round led by IA Ventures (New York)
Since July 2017: Takes on CEO role at TransferWise from co-founder Taavet, who announces he is stepping down but staying on in a part-time role as chairman and board member.