

DBS’ AI-powered NAV Planner nudges customers towards financial and retirement planning
To date 2.8 million customers have begun to use it. This tool can stress-test portfolios and cash flows against inflation
Genevieve Cua
DBS Bank is making its most comprehensive effort yet to nudge its retail customers towards taking concrete action in their journey towards “financial freedom”, which Evy Wee, DBS’ head of financial planning, investments and insurance solutions, defines as financial independence and the freedom to pursue passion projects or pause work.
The linchpin of its efforts is a digital tool, DBS NAV Planner, which harnesses fintech and AI to enable clients to get started on a personalised financial planning road map. To date, an estimated 2.8 million customers have tapped the DBS NAV Planner for financial and retirement planning. Of these, about 35 per cent or nearly 1 million are active users.
Wee said that the goal is to get at least 1 million customers to take steps to address their needs, either through investments or insurance. “We saw a 4-fold increase in customers who were able to complete their investment journeys, in which AUM (assets under management) of digitally managed investments grew by 52 per cent last year.”
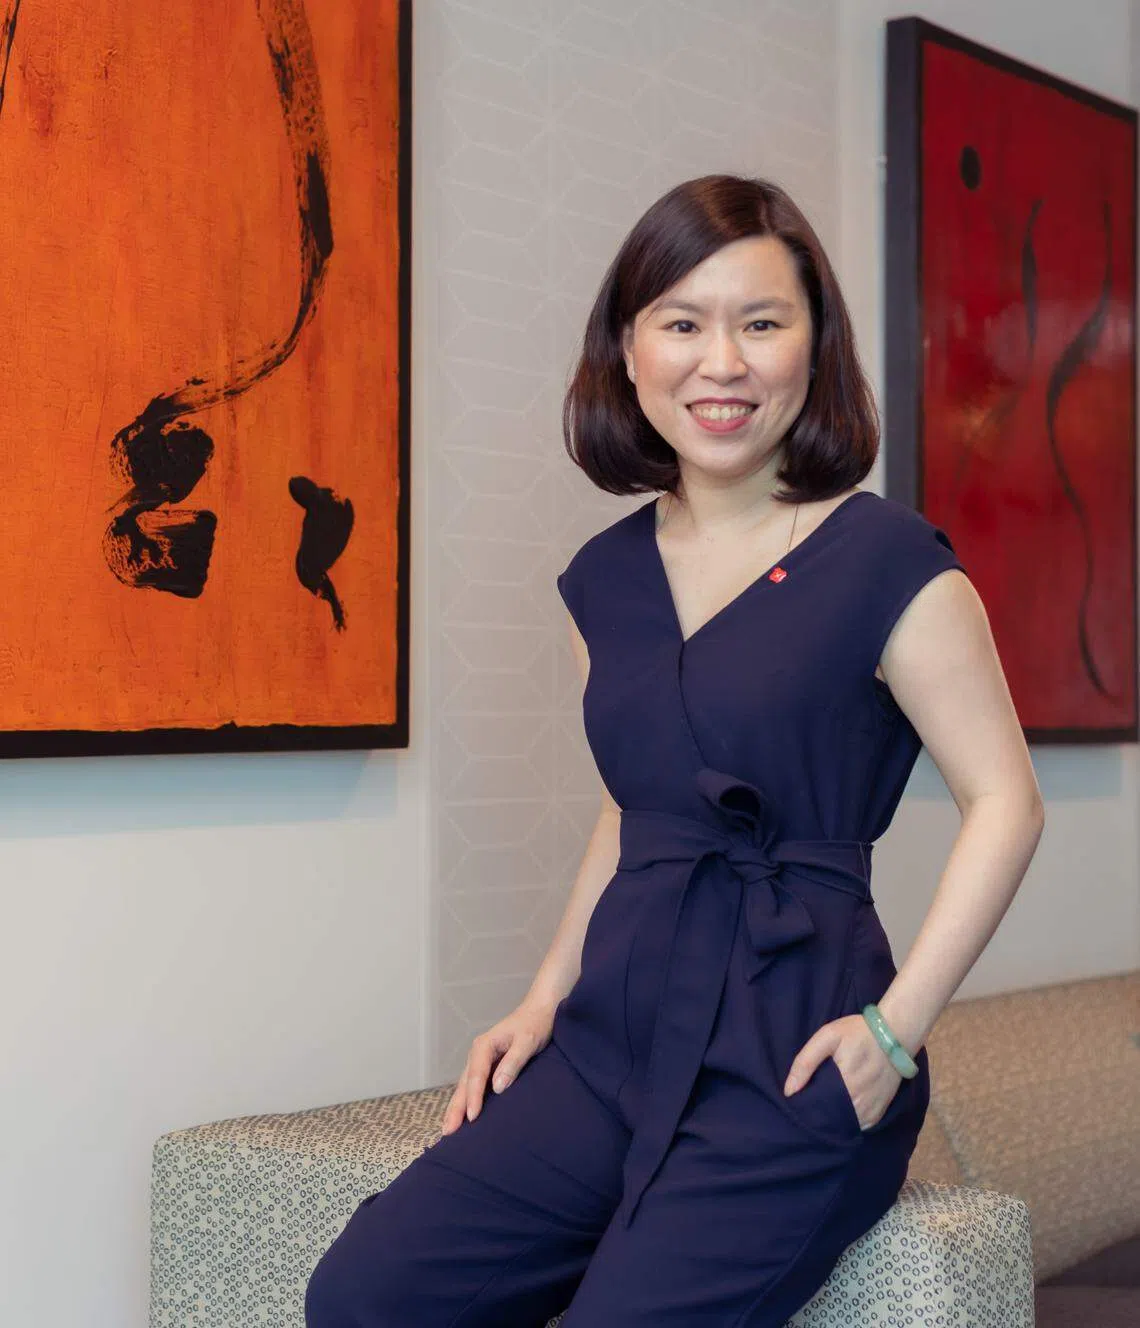
Wee says the tools embedded in NAV Planner – which includes a digital investment adviser – have become more resonant with market volatility and signs that inflation may prove sticky. “Rising inflation would very likely derail the plans of many to achieve financial freedom and, in the longer term, their plans for retirement. Now more than ever, we need to help our customers meet this acute need to properly plan their personal finances, invest suitably (according to their risk profile and appetite), and ensure they don’t over- or under-insure, so that they can still meet their financial goals and retire well.
“We are committed to helping everyone in Singapore – regardless of age and income level – achieve financial resilience and retire well.’’
The efforts include features to raise financial literacy and provide access to market research. NAV Planner’s digital investment adviser also incorporates the regulatory framework into its interface in terms of ascertaining customer knowledge prior to investments, for example. It also integrates financial planning principles, including determination of a client’s risk appetite and whether clients have an emergency cash cushion on hand.
Open banking via the SGFinDex (Singapore Financial Data Exchange) is a big enabler, giving users a comprehensive view of personal financial information – including deposits and loans with DBS and other banks; CPF and SRS (Supplementary Retirement Scheme) balances, as well as CDP accounts. Later this year, insurance data will also be included.
With this data, the “Map Your Money” tool within the NAV Planner is able to generate a personal balance sheet of assets and liabilities, assist in budgeting, and, more recently, also give a picture of clients’ total net worth. Clients are able to visualise future cash flows and potential savings gaps. Inflation impact, for instance, can also be modelled. The baseline inflation assumption within the system is 3.5 per cent a year, but clients can adjust this variable.
Wee says DBS, as Singapore’s largest bank, is in a unique position to help customers in their financial planning. “DBS has more than 80 per cent share of the total number of participants in SGFinDex. Our SGFinDex data shows that customers are willing to consolidate their financial information with a trusted financial planning institution or platform.
“We have designed and developed the NAV Planner to help customers plan their finances objectively and independently, based on rules pre-defined and aligned with the Financial Planning Association of Singapore... We’re not just aggregating data for the sake of it. We do it so that clients can extract value from our tool and understand their own financial situation and where they aim to be.”
Wee works with a team of 100, who collectively have a financial planning remit, including data scientists, customer experience and product managers and technology developers. “To achieve scale today, data and technology have been of tremendous help. We’re very passionate about using digital tools to get people started when they’re young. But we’re also seeing demand from older clients. Through the NAV Planner, people are asking us: ‘I need to retire, but how do I withdraw from my SRS?’”
Wee says clients who have used the NAV Planner continue to top up their digital portfolios, despite market volatility. They can choose from any of 200 retail funds on DBS’ shelf, or invest in DBS’ digiPortfolio, a robo offering comprising portfolios of exchange-traded funds.
The NAV Planner integrates a number of safeguards to ensure that those who are financially vulnerable do not invest beyond their risk appetite or resources. For instance, those with a “conservative” risk profile are redirected towards protection needs. Those with insufficient emergency savings will be prompted to set aside more. If clients have an insufficient emergency buffer and a negative cash flow, they will not receive product recommendations.
Portfolios need to be stress-tested by inflation, she said. “The amplification of what inflation today means for the generations tomorrow and their long-term planning is something that all of us need to focus on as well. It’s something that we take very seriously. Hence, our tools enable people to stress-test their finances and put their money to work… We want customers to be able to respond without fearing what it means to their financial plans.”
Meanwhile, the bank also has a number of other initiatives aimed at further assisting pre-retirees, retirees and younger investors in their planning. These include:
- DBS Insurance Cash Access. This is a service through which a client can sell an endowment policy to DBS, and receive a cash payout. The client retains the option to buy back the policy later. If he chooses not to buy back the policy, he will receive the balance of the maturity value, subject to a 3 per cent fee. This service applies only to fully-paid Manulife endowment policies, with 5 years to maturity.
- DBS Home Equity Loan. This is a reverse-mortgage scheme to enable seniors to unlock the equity from their fully paid private homes. The maximum loan is up to the amount needed to top up CPF accounts to the prevailing CPF Enhanced Retirement Sum. The Business Times understands that clients have asked whether amounts can be released and not tied to the CPF. “We’re looking into enhancing the current version to allow withdrawals to be put into potential investment or insurance solutions, to ensure customers use the cash for the right purposes as they live out their senior years,” said Wee.
- DBS Vickers Young Investor Account. Launched for those 18 to 25, it charges a flat commission rate and zero custody fee for foreign holdings. Wee says trading volume has remained stable this year.
- Income in retirement. Wee observes that clients want a vehicle that distributes income in retirement. DBS tied up with Schroder in 2020 to launch Schroder Asia More+, a multi-asset fund with the choice of a decumulation share class, which has a target annual payout of 6.88 per cent. The other traditional share classes of accumulation and distribution are also available. To date, the fund has assets under management (AUM) of over S$500 million.






