

After the Magnificent Seven, a broadening rally
Energy and healthcare are beneficiaries of the equities rally. Instead of staying in cash, opt for bonds
SPRING in Japan is synonymous with the sakura. Also known as the cherry blossom, it blooms first in Kyushu, before creeping northwards and eventually blanketing the whole country in a carpet of pink.
The market’s rip-roaring rally in 2023 was primarily driven by the Magnificent Seven, a bag of stocks comprising Alphabet, Amazon, Apple, Meta, Microsoft, Nvidia and Tesla.
Just as the cherry blossoms of Kyushu herald the islandwide sakura season in Japan, the DBS Chief Investment Office believes that 2023’s tech-led surge is an early indication of a broadening market rally this year, with the energy and healthcare sectors as particular beneficiaries.
Equities aside, we retain a preference for bonds over cash, and see tailwinds propelling gold forward.
Signs of spring
With the S&P 500’s 26.3 per cent surge in 2023, it is justifiable to think that US stocks are at risk of boiling over. However, our analysis shows that this is not necessarily the case.
When viewing the S&P 500 on an equal-weighted basis – that is, all companies are allocated a fixed, equal weight in the index – the index’s forward price-earnings ratio is 17.4 times, below the long-term average of 17.7 times.
In other words, from a historical standpoint, the valuation looks fair.
Furthermore, not only is there room for them to grow, but there are also three factors that can spur companies further.
First, US financial conditions are surprisingly loose, on the back of the strong equity market and compressed corporate yield spreads.
Second, companies’ interest expense ratio has remained low. The average interest expense ratio of US firms is 6.8 per cent, compared with a long-term average of 22.3 per cent.
Third, the US economy remains resilient. Even though first-quarter gross domestic product was lower than expected, the economy has been healthy the whole of 2023, supported by robust consumer spending.
In combination, these conditions will boost corporate earnings which, in turn, will drive up equities further.
Select winners
We believe the energy sector, in particular, will be the beneficiary of the broadening rally.
The sector’s fundamentals look healthy: the return on equity for energy has rebounded from minus 20.8 per cent in April 2021 to 19.3 per cent in February 2024.
Despite that, investors are still underweight the sector, with positioning hitting a low of minus 28.8 per cent among US portfolio allocators. As a result, the sector’s price-to-book ratio remains low at 2.2, making it an attractive buy.
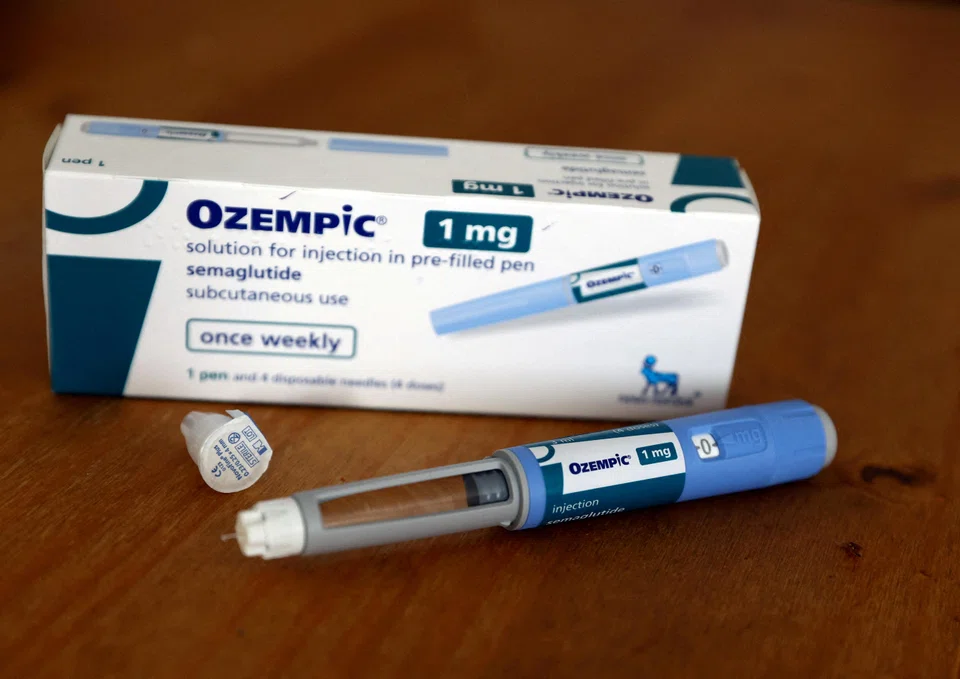
The healthcare equipment and services sector, on the other hand, is getting a shot in the arm, thanks to the blockbuster success of glucagon-like peptide-1 (GLP-1) drugs.
Bursting onto public consciousness in 2021 when Ozempic, a GLP-1 medication, was shown to reduce body weight by 15 per cent over 68 weeks, the drug has propelled the share prices of its makers – most particularly Novo Nordisk and Eli Lilly – higher, in an almost directly inverse relationship with the amount of weight patients lost.
As more pharmaceutical companies scramble for a piece of the GLP-1 pie, we see the healthcare sector as an attractive pick.
Bonds over cash
Keeping assets in cash has never been a good long-term strategy. Investors lose out on higher returns when they keep a chunk of their portfolio in cash.
This is why the DBS CIO Office recommends deploying cash into bonds.
Although the yield curve appears to be steepening, it is still inverted, which means short-term yields are higher than long-term ones. That makes the sweet spot for bonds around three to five years.
However, investors should remain cautious with junk-rated debt. Opportunities are aplenty with investment-grade credit, with the sweet spot landing in the A/BBB range.
In combination, A/BBB-rated bonds of a three to five-year tenor are investors’ best defence against yield volatility and curve steepening.
All that glitters
Another bright spot (quite literally) is gold. The bullion has been setting a series of new record highs recently. As at Apr 29, gold was trading at US$2,336/oz, approximately 13 per cent up, year to date.
Geopolitical risks play a part in this. As the Israel-Hamas war and Russia’s invasion of Ukraine remain protracted, the allure of gold as a hedge is burnished.
Central bank buying is another trend. Demand for gold has risen steadily because some central banks are attempting to shift away from US dollar dominance, manoeuvring instead towards real assets that are not at risk of sanctions.
Total demand in 2022 and 2023 exceeded 1,000 tonnes each year, significantly higher than the average annual demand of around 600 tonnes during the past decade. We believe this is a structural – not cyclical – shift, which means gold prices will likely be supported in the long run.
Final thoughts
While there is evidence that the current rally in equities will broaden and is not a symptom of irrational exuberance, no bullish trend runs in a straight line.
Think about how the sakura season is magical but short-lived, some blossoms surviving just four days.
Just as a year is spliced into seasons, markets run in cycles. Investors should seize this opportunity to put cash to work as we see signs of spring spreading.
The writer is chief investment officer, DBS Bank






