

Brace for a new normal: Higher cost of catastrophe cover
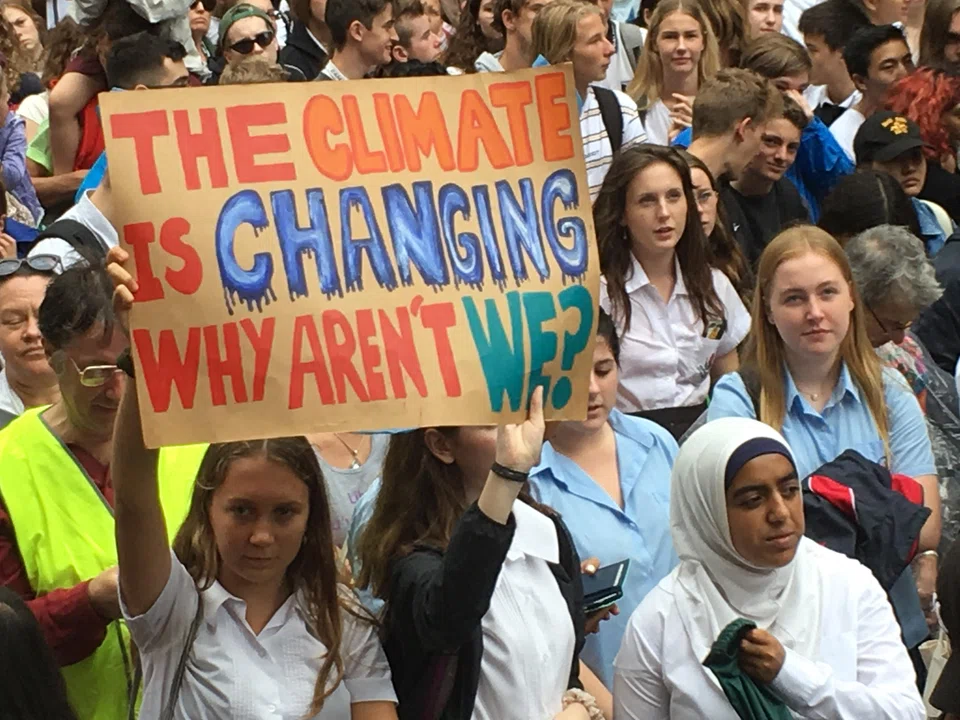
CLIMATE change has been on scientists’ radar for more than five decades, but it was only in the 1990s that the world woke up to the need for collective action. In 1994, the first international treaty to limit greenhouse gas emissions and prevent climate change went into force, ratified by roughly 200 countries. Fast-forward to 2023 and the stark impacts of global warming have intensified. Land and sea temperatures this year hit record highs, making it increasingly likely that the long-term target of keeping the global temperature rise within 1.5 deg C is out of reach.
Insurers are bracing for worse outcomes. In many quarters, serious thought is being given to the industry’s capacity to cover not just natural catastrophes, but also even ubiquitous property and casualty risks where protection is indispensable for companies. Insurance provider Swiss Re described 2022 as a “perfect storm” – with good reason. Global economic losses from natural disasters hit an estimated US$275 billion. Of this, the share of catastrophic insured loss was 45 per cent or US$125 billion, the fourth-highest total for a single year since 2005. The 10-year average insured loss between 2012 and 2021 was US$81 billion.
This year is expected to be worse. “We expect hard market conditions to persist in 2023, based on rising demand for coverage and inflation-driven higher values of insured assets,” said Swiss Re. The current higher-rate environment is also a challenge. Higher interest rates deal a double whammy. They raise insurers’ cost of capital and, at the same time, reduce the value of financial assets on insurers’ balance sheets.
Not surprisingly, premium rates are hardening. McKinsey noted that global property catastrophe reinsurance rates jumped by 37 per cent in 2023, the largest escalation since 1992. Already, in the US alone, some insurers have withdrawn coverage in parts of California where flood and wildfire risks have risen. In other US states, flood protection rates have quadrupled. Australia grapples with a similar predicament. A study finds that by 2030, more than half the properties in at least 17 Australian suburbs would become uninsurable.
For many corporates and households, insurance is almost the first and only avenue for risk mitigation. To be sure, demand is intact and growing. The global average protection gap for natural catastrophes has been estimated at 58 per cent. In the Asia-Pacific, the gap is even greater at 92 per cent, suggesting a vast untapped market. The industry has robust tools for risk assessment and pricing. But now, capital is a challenge, in stark contrast to the past decades when low rates made for abundant capital.
To some extent, the demand-supply imbalance may be cyclical, particularly if a US economic soft landing is achieved, inflation moderates, and rate hikes are unwound. But structural factors in the form of a significant upward repricing of climate risks, among others, cannot be ignored. Until the industry begins to demonstrate better returns or lower catastrophe losses, which would then persuade more capital providers to step up, the writing is clear for protection buyers. Higher premiums, tighter underwriting conditions, and more limitations on cover are likely par for the course. As climate change intensifies, these conditions may well become the new normal.
TRENDING NOW
DBS remains analysts’ pick ahead of Q3 earnings after Singapore banks’ share slump
Singapore identifies 7 firms responsible for haze fires, notices issued urging action: Grace Fu
Good Class Bungalow market activity picks up pace on ‘realistic’ pricing

High Court rules against Julius Baer’s Singapore trust arm in US$50 million family trust dispute

