

Don’t mistake the familiarity of Singapore equities for diversification
They often share the same underlying sensitivities such as local interest rates and property fundamentals
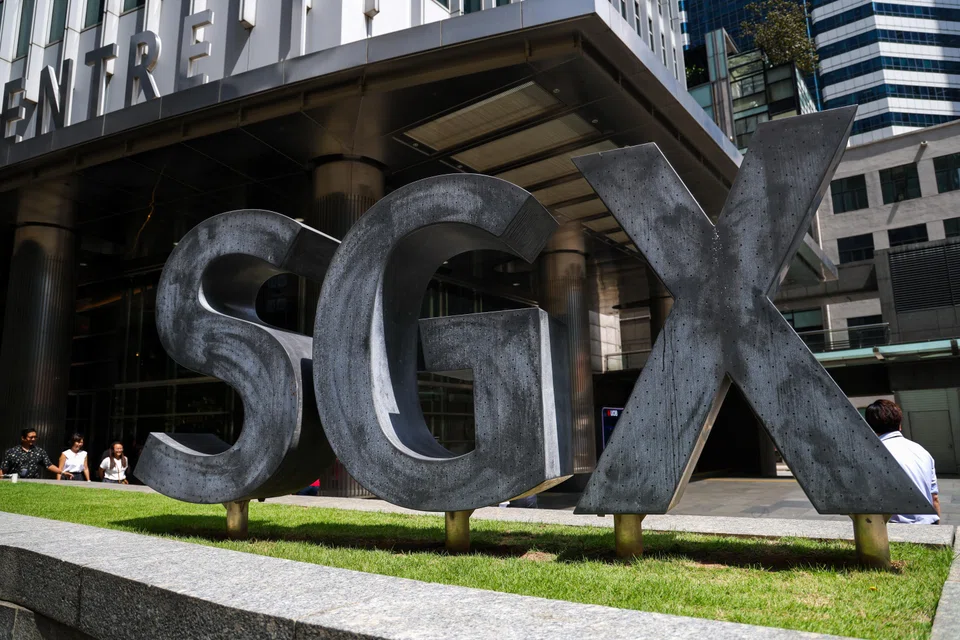
AFTER years of watching US technology stocks dominate the conversation, it is easy to see why Singapore investors are paying closer attention to their home market again.
The Straits Times Index rose more than 20 per cent in 2025 and has continued to attract interest this year with solid double-digit returns. The local market has earned its moment.
But the investor instinct that follows good performance, to feel reassured by what is working and to add more, deserves scrutiny.
Singapore equities can be a meaningful part of a well-constructed portfolio. The question worth asking right now is whether they are becoming too much of one.
The rally has been real and broad-based. Singapore’s market is structurally different from the US and much of global equities: less technology, more banks, real estate investment trusts (Reits), infrastructure-adjacent businesses and industrial conglomerates with international order books.
The banks have benefited from a higher-rate environment, though that tailwind is not permanent.
What has distinguished the large Singapore banks over time is their ability to grow fee income, wealth management, transaction banking and treasury alongside traditional lending. That diversification within the business model matters more to long-term earnings quality than simply where rates go next.
Reits remain useful for income-seeking investors, but they are not bond substitutes. In a higher-rate environment, they can behave more cyclically than their headline yields suggest. Valuations, refinancing conditions and balance sheet quality all matter, sometimes more than the distribution itself.
Beyond financials, parts of the market have genuinely benefited from global themes: aerospace recovery, defence spending, infrastructure and international order books for the larger industrial names. Singapore’s recent strength has not been a purely domestic story, and that breadth is worth acknowledging.
Whether these drivers continue at the same pace is a different question. Elevated rates eventually moderate. Order books need to become profitable earnings.
Policy efforts to deepen the local market and attract growth-oriented listings could broaden the opportunity set over time, but that is a gradual process, not an immediate re-rating catalyst.
When income becomes a trap
Singapore investors have always been drawn to income, and that inclination is not misplaced. Dividends provide visible cash flow, practical utility for those funding spending needs, and a discipline that growth-at-all-costs markets sometimes lack.
The problem arises when a high dividend yield is treated as sufficient justification on its own. In a market where banks, Reits and established blue chips dominate, yield can obscure as much as it illuminates.
A distribution looks attractive until earnings weaken, debt costs rise or the payout ratio turns out to have been stretched, and then investors find themselves facing both a cut and a capital loss simultaneously. That is the classic dividend trap.
The stronger version of dividend investing is income supported by earnings quality, balance sheet strength and disciplined capital allocation.
DBS is a useful illustration. Part of its appeal has clearly been income, but that income has not come at the expense of capital appreciation.
The stock has offered dividend yields in the mid-single digits in recent years while also delivering meaningful share price gains. The real question is not the yield itself, but whether the company can keep funding it through the cycle while still investing in areas with credible long-term returns.
Income and compounding are not in conflict. The strongest income portfolios are built on cash flows that can be sustained and ideally grow, through the cycle.
Familiarity is not diversification
Home bias is one of the most persistent tendencies in investing. Local companies appear in the news; their dividends are predictable; and for investors whose spending needs are in Singapore dollars, there is practical logic to holding local assets.
None of that is irrational. But familiarity and safety are not the same thing, and conflating them is where portfolios go wrong.
A Singapore-heavy equities portfolio can look diversified on the surface: banks, Reits, telecoms, industrials, with several names across each sector. In practice, those holdings often share the same underlying sensitivities: local interest rates, Singapore property fundamentals and regional credit conditions.
When those conditions turn, they tend to turn together. Sector labels provide less protection than investors assume when the underlying risks are correlated.
The concentration problem is compounded by the fact that a small number of companies account for a disproportionate share of the index, meaning investors building around familiar blue chips may have less breadth, and more single-name exposure, than their holding count suggests.
The more important gap, though, is what a local-heavy portfolio misses entirely.
Global technology, healthcare innovation, consumer platforms, energy transition and advanced manufacturing – these represent substantial and growing parts of the world economy. They are largely absent from the local listed market.
An investor who stays within Singapore will be underexposed to the sectors shaping long-term global growth, without having made any conscious decision to do so.
The practical test is straightforward: if Singapore’s property market weakened significantly, if local rates fell sharply, and if regional bank earnings came under pressure simultaneously, what would happen to your portfolio?
If the honest answer is “a great deal”, you have more concentration than diversification, regardless of how many names are on the statement.
The renewed attention on Singapore equities is well-founded. The local market offers quality franchises, income visibility and exposure to several durable regional themes.
What I would caution against is the mental shift from “Singapore is worth owning” to “Singapore is enough”. The first is a deliberate allocation decision. The second is concentration dressed up as familiarity.
The writer, CFA, is head of investment advisory Singapore, Arta Finance
TRENDING NOW
‘Not trying to solve world hunger’: GoTo takes pragmatic approach to AI

He built the Vingroup empire. Now South-east Asia’s richest man is handing some key roles to his sons

Malaysian developer Eco World tops bids for Sin Ming area housing plot with S$1,612 psf ppr bid

Singapore’s new data centres must use renewables. Can they overcome the hurdles?

