

Harnessing transition finance to plug Asia’s net-zero funding gap
Governments, investors and society realise that these industries not only need help to enable their transition, they are also critical enablers of the broader transition
UNTIL recently, efforts to marshal global capital in the pursuit of a cleaner, fairer world have focused primarily on companies that fall neatly inside the parameters of environmental, social, and governance (ESG) investment.
However, as ESG investing has moved more into the mainstream, it has excluded in the process, high-emitting industries such as steel, cement, chemicals, mining or shipping.
This is more than an academic distinction: Governments, investors and society are recognising that these industries not only need assistance – both financial and technological – to enable their transition, but in some cases, they are critical enablers of the broader transition themselves.
In Asia, the need for transition finance is particularly acute. Currently, the region is off course in delivering its 2030 climate targets.
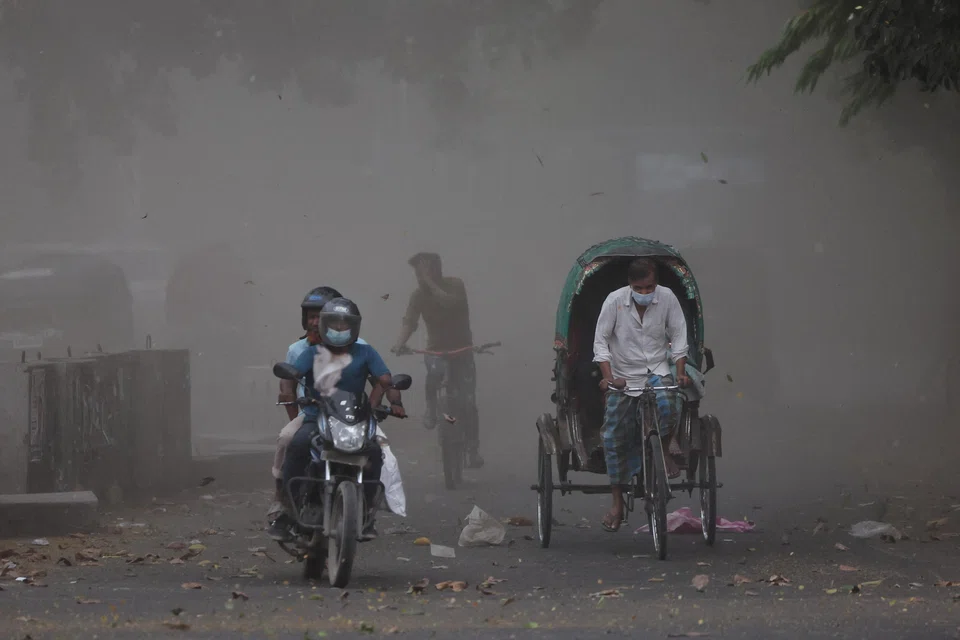
Asia still produces 85 per cent of its energy from fossil fuels, accounts for more than half of global carbon emissions, and produces 65 per cent of the world’s plastic waste.
At the same time, Asia is warming faster than the global average and is vulnerable to the physical implications of climate change, as demonstrated in 2022 where more than 80 natural disasters affected 50 million lives and led to overall economic damage exceeding US$36 billion. It is thus very much in Asia’s long-term interest to invest in a transition that contributes to a more sustainable business model for growth.
Asia is well placed to capitalise on the potential of the transition by leveraging its rich natural and human capital as well as technological innovation.
Transition aims, structural concerns
Broadly, transition finance refers to investment in economic activities that meet three essential criteria: They are emissions intensive; they may lack a low or zero-emission substitute that is economically and technologically viable; and they are essential for continued socio-economic development.
The aim of transition finance is to invest in sectors that require capital to decarbonise their current operations and support the next generation of low-carbon technologies. However, these sectors are often hard to abate due to insufficient technology or a lack of finance to change existing business models.
So far, transition bonds have not been successful in delivering this finance in developed markets. Investors building low-carbon portfolios often see “dirty” assets as an inherently challenging concept, and many asset managers are unsettled by the reputational risks associated with them.
There are also widespread concerns that in the absence of clear frameworks, some heavy emitters are using transition finance to “greenwash” their operations without driving any real change.
The fact is, transition planning involves significant uncertainties because you are forecasting future events, particularly technological innovations that may not exist.
Currently, the transition financing gap stands at almost US$4 trillion a year. To reach net-zero targets globally by 2050, a total of about US$5 trillion annually is required. To plug that gap, it is vital to have clear and transparent frameworks to give both issuers and investors confidence that capital is being channelled in a way that supports broader net-zero objectives.
Creating investing opportunities in Asia
Frameworks that will standardise the landscape are beginning to emerge. In Asia, regulators are taking the lead in defining transition finance principles, which will lead to greater transparency and, it is hoped, a surge of new investment.
The 2023 Singapore-Asia Taxonomy, for example, is one of the first in the world to include the “transition” category directly.
Elsewhere, frameworks such as the United Kingdom’s Sustainability Disclosure Requirements (SDR) explicitly consider investment in improvers as a distinct category of sustainability to encourage transition activities.
These positive moves are already driving fresh financial sector flows by creating new opportunities for investors to move into segments that are not necessarily “green” in the traditional sense, but play an important role in ensuring that the real economy transitions credibly to a net-zero future.
The most notable example is Japan, which now leads the world in transition bond issuance. Over the next 10 years, the Japanese government plans to issue about 20 trillion yen (S$17.9 billion) in sovereign transition bonds, which is expected to crowd-in a further 150 trillion yen of private sector transition investment.
Japan has been able to provide an overall framework for transition bonds which are now being used for a wide variety of purposes that fund emissions reduction. That, in turn, provides opportunities for Japan’s corporations to follow. Ultimately, governments do not have trillions of dollars to fund the financing gap, which is where the private sector can and should step in to do their part.
Aiding corporates in their journey
Investment managers can also play a key role in creating a credible landscape for transition finance. Transition often does not happen in a linear fashion and not all transitions look the same. It requires a strategy that is unique to the market, the industry and the company.
Our engagement with companies focuses on the local challenges and opportunities presented and highlights the importance of effective communication for investors to evaluate whether a transition strategy is credible.
Such communication is especially important in Asia because climate and ESG disclosure is relatively nascent, so companies are often tackling the dual challenge of building out disclosure capacity while setting targets.
Through this holistic approach, we have been supporting companies across Asia to transition in a credible and responsible manner. These include palm oil producers and nickel miners in Indonesia, a vehicle manufacturer in Japan, and a utility provider in South-east Asia.
As more businesses develop credible transition plans, it is important for asset managers to champion further developments in transition finance and engage with regulators and governments to close policy gaps and channel financing to the right transitional activities.
The power of finance should be harnessed to limit the impact of climate change and support a net-zero future. Transition finance is a critical tool in reaching that goal.
The writer is chief sustainability officer, Fidelity International
TRENDING NOW

Grab CEO’s wife Chloe Tong on life with Anthony Tan and finding her purpose
Income Insurance appoints former Manulife Singapore top man as new CEO

Incidence of civil servants buying property near unannounced MRT stations ‘a concern’, but may not establish misconduct: PSD

Three ex-employees of Envy group join Ng Yu Zhi in bankruptcy

