

Has ‘US exceptionalism’ peaked? Consider exposure via non-US companies with US businesses
Uncertainty over American policies threatens to spark a negative cycle that could materially dent business and consumer confidence
THE concept of US exceptionalism in finance – that the US market is distinctive and delivers higher returns than elsewhere – is not new. Data from the UBS Global Investment Returns Yearbook 2025 shows the US stock market has generated significantly higher returns than anywhere else over the past 125 years.
Historically, the opportunity cost of bypassing the US was painfully high.
Analysis by the Yearbook’s authors – London Business School academics Elroy Dimson, Paul Marsh and Mike Staunton (DMS) – found that US$1 invested in US stocks in 1900 would have grown to US$2,911 by end-2024, an annualised return of 6.6 per cent. In contrast, US$1 invested in the rest of the world (ex-US) would have grown to just US$194 or 4.3 per cent annualised.
The big question that now occupies markets is this: has US exceptionalism peaked? US President Donald Trump’s on-again, off-again stance on tariffs and potential retaliation from America’s trading partners have dented sentiment. Year to date, both the S&P 500 and Nasdaq are down; the worst decline has occurred in the past two to three weeks.
As at Mar 14, the S&P 500 had fallen by more than 8 per cent from its intraday high on Feb 19. A 2 per cent rebound on Friday pulled the index up from correction territory. The Nasdaq fell more steeply by about 11 per cent.
Uncertainty over US policies threatens to spark a negative cycle that could materially dent business and consumer confidence. In its most recent weekly note, the Institute of International Finance (IIF) said that concerns are mounting over US corporate earnings from overseas.
“Given that nearly 70 per cent of US economic activity is driven by consumer spending – largely fuelled by the wealthiest 20 per cent who hold the largest share of US stocks – a deteriorating stock market outlook could suppress consumption, slow growth, reduce tax revenues, and worsen government debt dynamics,” it noted.
Since Trump took office, consumer sentiment has sunk to its lowest level since 2022.
Two recent pieces of research – DMS’ analysis in the Yearbook and a paper by the Capital Group investment director Andy Budden – throw up insights on US exceptionalism, concentration risk and the merits of diversification. After two years of back-to-back double-digit gains by the S&P 500, handwringing has intensified over concentration risk.
As DMS pointed out, the 10 largest stocks’ weighting in the S&P 500 was 34 per cent, and they accounted for 63 per cent of returns in 2024.
There are reasons, however, that US exceptionalism could continue, said Andy Budden, Capital Group’s investment director, along with elevated valuations. In a recent media briefing, he noted: “Investors absolutely recognise that you have to pay for American exceptionalism, and that presents a challenge on how do you navigate this attractive opportunity, but with rather high valuations.”
Here are some insights from the two studies.
- Diversification works but not for US investors, says DMS. US pension funds heeded the call to diversify in the 1970s and raised their international exposure from zero to around 38 per cent today. But this strategy did not pay off. Regardless of time frame, for US investors, the portfolio Sharpe ratio for US domestic exposure was far higher than for a global exposure. However, for several other countries, a global exposure produced a higher Sharpe ratio than investing domestically. The Sharpe ratio is a measure of reward or return per unit of risk.
- Only 5 per cent of all stocks are winners. Stocks are the best performing asset class, but most stocks do poorly. Based on the average across all countries between 1990 and 2020, DMS found that 52 per cent of stocks lost money; 57 per cent underperformed Treasury bills or cash; and 71 per cent failed to beat the market. Marsh said: “Pretty much in every country except Switzerland, the best performing 5 per cent of stocks accounted for all the market performance. The moral is that investors should be well diversified, unless they’re very talented stock pickers. And the reason for that is that concentration of performance in a very small minority of best performers means that otherwise you’re likely to underperform the market.”
- Structural factors. There are arguably structural reasons for US exceptionalism to persist, despite today’s market turbulence. Capital Group’s Budden, author of “Can American exceptionalism continue?”, lists some reasons why the US provides the most rewarding backdrop for investors. One is a deep and rich capital base, “just vast pools of retirement savings and other wealth savings, most of which gets recycled into the US economy”. “Right now, we’re seeing the beginnings of what is going to be an incredible AI super cycle of capital investment”.
Two is the “secret sauce” of productivity growth, which has underpinned two-thirds of economic growth since World War II.
Three is the US’ status as the world’s innovation hub. “The US has an amazing ability to attract talent, to deploy capital with agility, and to get capital out of opportunities once they’ve worked.”
Four, the US regulatory backdrop is less constraining for companies and encourages long-term investment.
Five is the prevalence of management compensation in the form of stock options which align the interests of management with shareholders. “Company managements have also offset the impact of dilution not only by pursuing superior profit growth, but also by conducting stock buybacks so that the net dilution impact is negative – that is, buybacks exceed share issuance.”
This has greatly boosted company returns to the benefit of shareholders.
This has not been the case in China, where share prices have been volatile, earnings growth weak and there was little growth to accompany share dilution.
Late last year, the government issued guidelines to get A-share listed companies to take steps to boost investor confidence and value via employee stock ownership, mergers and acquisitions and share buybacks, among others. In terms of annualised total US-dollar return, MSCI China has generated just 2.9 per cent, compared to 13 per cent by MSCI USA Index. Earnings per share compound annual growth was minus 2.7 per cent for MSCI China vs 7 per cent for MSCI USA.
- The big challenge is valuations. Almost all valuation measures are signalling a correction. The S&P 500 PE (price earnings) multiple at end-January based on trailing 12-month earnings was 25.8 times, wrote Budden, substantially higher than the average PE of 18.8 times in periods when the 10-year Treasury bond yield was 4 to 5 per cent. “If we assume that the PE multiple reverts to this average over a 10-year period, this implies a cumulative decline of 27.9 per cent or 3.1 per cent a year… It is possible that the reversion to mean happens more quickly; at its most extreme (this could mean) a rapid market decline of 30 per cent or more.”
- Invest in non-US companies. Non-US companies with substantial US revenues enables participation in US exceptionalism, in a way that mitigates valuation risks. Around 40 per cent of the revenues of companies in the S&P 500 is generated outside the US. Among European companies, the exposure to revenues outside Europe is even higher at 60 to 70 per cent. “What that means is that you can buy great US businesses inside a European wrapper at a much lower valuation than their US competitor,” explained Budden.
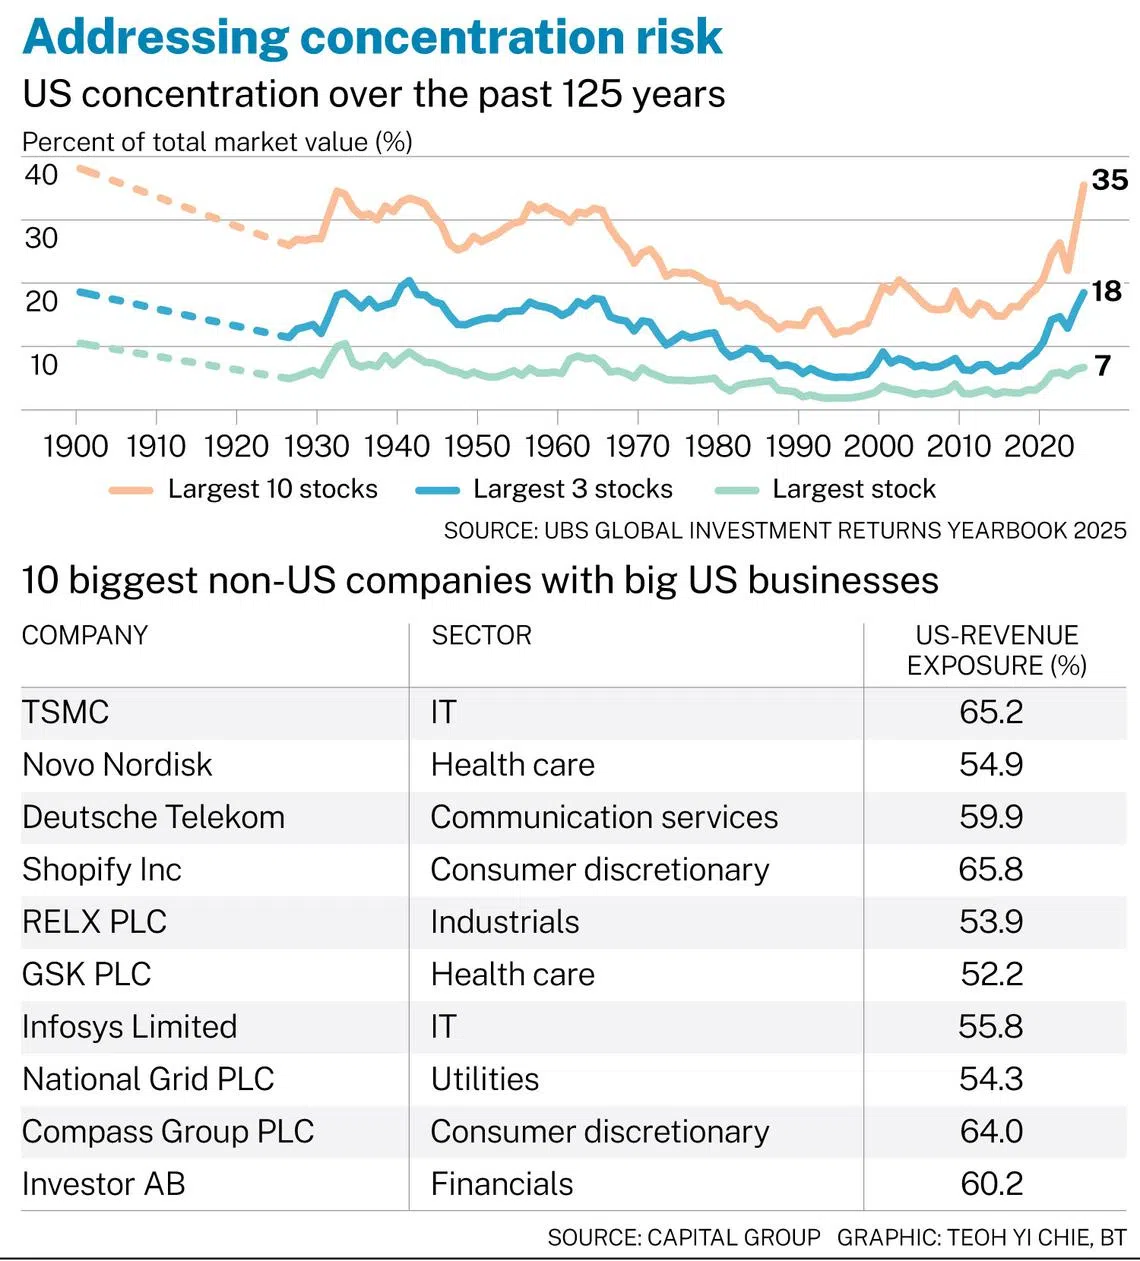
“US assets in global wrappers” – non-US companies with significant sales in the US – could benefit from continued strength of the American economy under a pro-growth administration, wrote Budden. The companies also have existing or growing manufacturing and research and development bases in the US, which helps to navigate around potential tariffs.
TRENDING NOW

Grab CEO’s wife Chloe Tong on life with Anthony Tan and finding her purpose

Three ex-employees of Envy group join Ng Yu Zhi in bankruptcy

He built the Vingroup empire. Now South-east Asia’s richest man is handing some key roles to his sons

If AI has a one-in-five chance of destroying us, what do we do with the remaining four?

