

‘Maturation’ of private credit asset class may cause shake-out: PGIM chief
But the underlying trend of institutions and high-net-worth investors having this asset in their portfolios will continue to grow
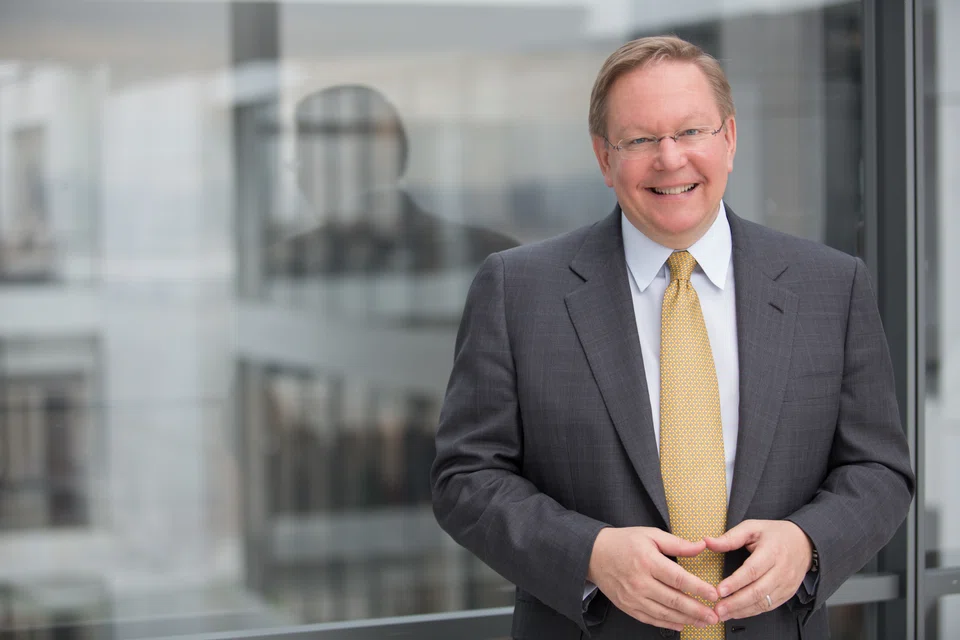
PRIVATE clients’ “voracious” demand for private or unlisted debt is likely to underpin demand for the asset class, said PGIM president and chief executive David Hunt. But the sector is undergoing a “maturation” process which may cause a shake-out.
“Private credit draws a lot of capital and new competitors. All that gets ahead of its skis and we do have a bit of a shake-out. But the underlying trend of institutions and, increasingly, high-net-worth investors (HNWI) having private credit in their portfolios will continue to grow...
“I do think there is a process of maturation. Many people who, two to three years ago, set up shop are actually having a hard time raising money now. If we have a credit cycle, it may cause a shake-out.”
He said many private debt managers were spun off from investment banks. “They just do agented transactions. They don’t have many covenants or protections if things go bad. If the economy stays good that may be all right, but they won’t survive trouble well,” said Hunt, who was recently in Singapore.
PGIM manages a total of around US$1.3 trillion in assets. Of this, traditional fixed income comprises about US$805 billion and private alternatives, US$319 billion. Of the latter, private debt accounts for US$103 billion and real estate, US$206 billion.
The firm is the global asset management business of Prudential Financial. It is the fourth-largest public bond manager globally, and the second-largest private debt manager.
Hunt said the Asia-Pacific has been a “remarkable growth story”, where PGIM’s assets under management (AUM) in the region have risen by more than 10 times over three decades, from less than US$20 billion to US$212 billion currently.
“Asia has been important as we build our international footprint. The core of that has been the institutional business in the early days. But in the last few years, growth has been driven by an increasing push into retail and high-net-worth markets, by bringing more of our private credit strategies to bear in the region, which seems all the rage.”
He said the firm has “high aspirations” for Asia-Pacific. “Growth will come from bringing private alternatives much more forcefully and fully into Asia... Wealth has been created effectively here, and I think we’re well positioned to help manage that and capture it.”
Distribution is through PGIM Investments, which has a presence in Hong Kong and Singapore. Last year, PGIM Investments partnered Bank of Singapore to launch PGIM’s core strategy in Asian real estate. In partnership with a global private bank, PGIM also launched a global data centre strategy, which is a private digital infrastructure fund for HNWI in Asia and Europe.
Preqin estimates a total of nearly US$2 trillion in global private credit at end-2023, and this is expected to grow to US$2.6 trillion by 2029. In a recent report, McKinsey said the size of the addressable market for private credit in the US alone could be US$30 trillion.
McKinsey said the growth to date in private credit has been largely concentrated in direct lending. But in an environment of higher lending rates and a slowdown in private equity deals, the asset class is expanding into asset-based financing structures. Private credit has seen significant inflows from retail and insurance capital pools.
Hunt believes PGIM’s edge in an increasingly competitive private debt market is its ability to source deals directly from corporates and its long history of underwriting.
“We’re not simply buying agented deals from an investment bank, although we do some of that. We get to know owners and founders of businesses, and our approach is to be their long-term financial partner. We have companies that we’ve invested in for several generations. Businesses sometimes get into trouble. Instead of pulling the rug out from under them, we help them restructure the business and put in more money to help them get through it...
“We’ve actually done very well from an investment perspective even when we’ve had credit issues, because we have strong covenants in place – which again, is because of the direct relationships we’ve had with the companies and because we take a long-term view of their business,” he said.
PGIM plays in the middle market segment of private credit, where companies have US$50 million to US$100 million in earnings.
The US Federal Reserve’s recent cut of 50 basis points in the federal funds rate is set to be “pretty positive” for private debt. “Many companies will decide to refinance some of the debt that they took on at higher rates, which they may well do through the private markets. I think we’d see origination volume in that scenario stay pretty robust,” he said
Hunt reckons the US economy will achieve a soft landing, and this suggests growth will remain robust. “Interest rates will slowly come down. Inflation may stay a little above 2 per cent, but it will be quite contained. A close second to that scenario is one we call ‘weakflation’, where growth does slow to around 1 per cent, and the Fed would need to further reduce interest rates.”
In the firm’s base case of resilient US economic growth, there is likely another 100 basis points of rate reduction, he said. “This is less than is priced into markets now, but we’ll continue to see money flowing out of cash and money market funds, and into duration. We’re already seeing this and we’ll see even more.”






