

Put your portfolio on an even keel in 2023
Watching the Fed and market movements are untenable for long-term portfolios; aim for a resilient portfolio that may not shoot for the stars and does not fall as badly as markets
Genevieve Cua
EVERY year seems to fly by at a faster pace than previous years. But as an investment year, 2022 may well count as a year that overstayed its welcome.
Will 2023 prove a turning point to last year’s poor showing? While the war in Ukraine continues unabated, some things have changed. China is in the early stages of reopening its economy, raising hopes for a softer economic landing in Asia.
US inflation also shows signs that it may have cooled. Consumer prices in the US rose 6.5 per cent in December, the slowest pace since October 2021, and the sixth consecutive monthly decline.
Already fund managers and investors are betting that inflation has peaked and the Fed would begin to cut rates later this year. Predictably, this spurred a market bounce last week.
To be sure, in today’s macro environment, expectations around Fed actions move markets. But watching the Fed and following daily market movements are untenable for retirement portfolios. It makes you prone to knee-jerk reactions that could exacerbate losses and robs you of peace of mind.
In this column, I’ll try to distil some insights, based on a compilation of outlook papers from money managers and my observations.
The best-case scenario for individual investors like you and me is that we persevere with a diversified, balanced approach to our long-term savings, and avoid getting whipsawed by markets.
What we aim for is a resilient portfolio, which may not shoot for the stars in the best of times but should not fall as badly as markets.
Risk on? Not so fast
Even as investors bet that peak inflation has occurred, the coast isn’t clear to warrant a doubling down on equities. Economies are yet to reflect the lag effect of significantly higher interest rates. Earnings expectations are subdued, and recession remains on the cards
Most strategists have called for a “neutral’’ equities weighting in balanced portfolios, with a preference for quality and income. The big shift is that fixed income assets – castigated last year for their failure to serve as a diversifier in portfolios – are in favour, and strongly so, thanks to significantly more attractive yields.
Standard Chartered Bank in its 2023 outlook said its diversified multi-income strategy is offering a yield of over 6 per cent, last seen prior to the 2008 global financial crisis. “We believe investors have a window to lock in an attractive yield given the Fed is likely to approach the peak of its hiking cycle in H1 23 and potentially cut thereafter.’’
DBS has upgraded bonds to “overweight’’, citing their defensive qualities and recession risks. In a high-inflation, low-growth scenario, bonds historically fare better than equities. “There is never a better time for investors to buy bonds… The relative attractiveness of bonds is evident in the bond-equity yield gap (bond yield vs equity dividend yield) which is standing at the widest level since the GFC.’’
It’s helpful to revisit the role of yield, as UBS Asset Management points out in its Panorama publication. Yield is by far the most stable and reliable component of total returns for bonds, says Charlotte Baenninger, the firm’s head of fixed income.
In fact, for certain fixed income segments, like high yield and emerging markets, “price return has been negative over the long term yet performance has been positive and very strong, demonstrating the power of yield’’.
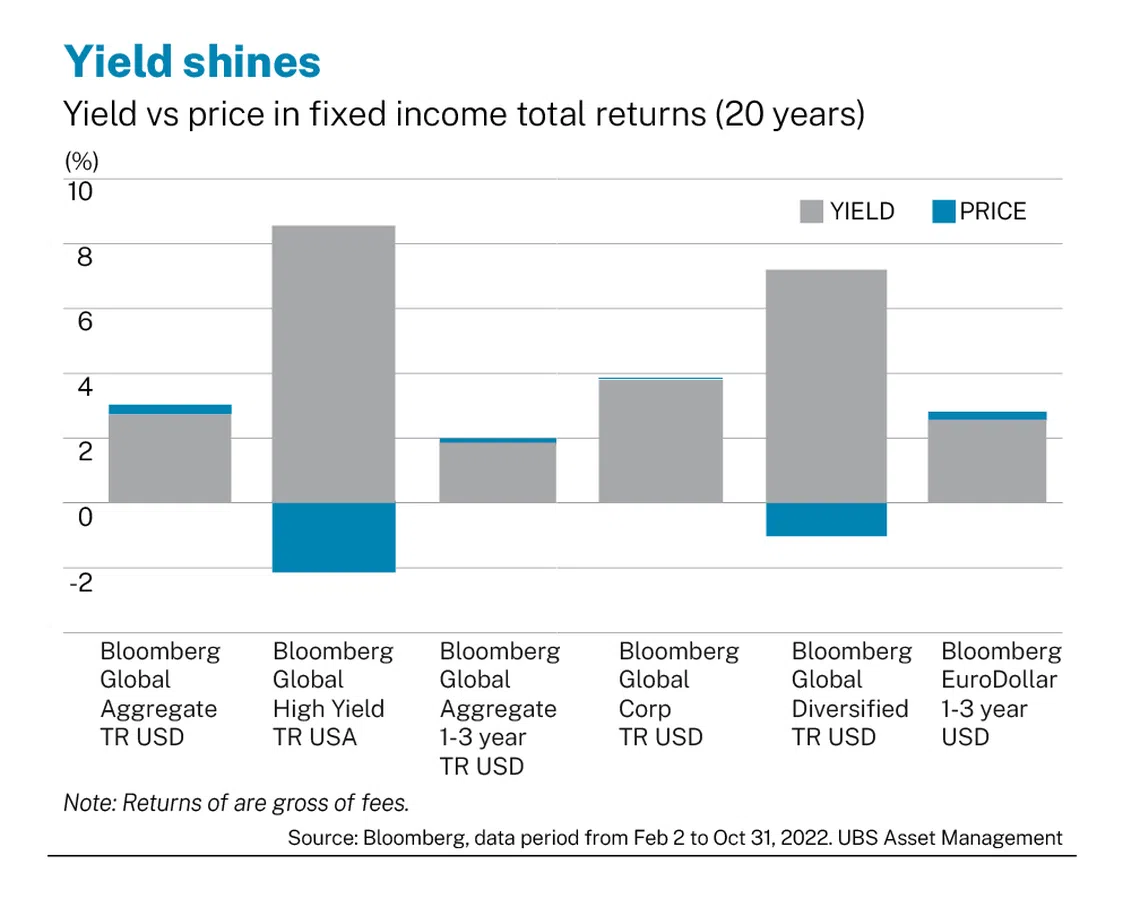
The silver lining today, she adds, is that investors no longer have to reach for yield by taking unnecessary credit risk, unlike in the past decade when rates were ultra-low. Until end-2021, only a quarter of the market offered yields of more than 2 per cent. This universe has since more than tripled to 83 per cent.
“We would argue that this development allows for a much better starting point for investors to achieve their investment goals, with an ability to build a much more diversified portfolio in terms of both issuers and sectors,’’ she says.
Balanced portfolios still relevant
Prior to 2020, depressed and negative yields on bonds prompted observers to sound the death knell for the 60/40 (60 per cent equities, 40 per cent bonds) portfolio, which has been a mainstay of retirement investing for decades.
The proverbial last straw seemed to occur last year when bonds and equities fell in tandem, leaving no respite for balanced investors. This synchronised downdraft is, however, unusual in the long history of markets.
In any case, thanks to the bear market, valuations have become much more attractive, giving long-term investors a chance to lock in attractive bond yields, in particular.
UBS Asset Management’s capital market expectations for the next five years for a global 60/40 portfolio are now significantly higher – 7.1 per cent vs 3.3 per cent in July 2021. Real or inflation-adjusted returns are pegged at 4.2 per cent vs 1.2 per cent in 2021.
“But regardless of what 2023 brings, we believe the inflation, growth, and geopolitical factors that have caused market strife in 2022 are increasing the potential rewards for medium and long-term investors willing to bear these risks. This is the good news about bad markets,’’ noted UBS.
DBS also advised a relook at the 60/40 strategy, where the risk-reward equation has become attractive.
An anchor in higher fixed deposit rates
Cash does not keep up with inflation, but the higher rates on offer are still a boon for retirees and offer an oasis for portfolios. As at early 2023, you can secure FD rates of up to 4.2 per cent, for tenors ranging from seven to 12 months. The minimum deposit required will vary depending on the bank. A shorter tenor enables you to stay nimble should you wish to dial up your risk by reinvesting elsewhere.
The latest Singapore Savings Bond (SSB) on offer (apply by Jan 26) is quoted at an average return of 2.97 per cent over 10 years. Interest has also been keen on six-month Treasury bills, which in mid-December yielded 4.2 per cent.
Maximise your CPF
Even as we puzzle over market direction, we are fortunate to have a stable savings base in our CPF, earning compounded interest over the long term, risk-free. There are a few ways to enhance the interest rates you can get.
- Top up your CPF Special Account (SA) early in the year, in order to earn 20 per cent more interest in your CPF over the next 10 years. Top-ups for yourself and family members will also earn a tax relief, subject to limits. Younger members below 55 may transfer Ordinary Account (OA) savings into their SA to earn higher rates.
- Maximise the ways you can earn a higher rate within the CPF. You could apply T-bills, where yields exceed the OA interest rate. For now this requires a visit to the bank, but from the first quarter this year CPF agent banks are expected to enable digital applications. Savings in the SA, Medisave and Retirement Account earn 4 per cent. The first S$60,000 of the combined balances earns an extra 1 per cent interest per annum. If you are 55 years old or older, you earn 2 per cent extra interest on the first S$30,000 of your combined balances and 1 per cent extra interest on the next S$30,000.
TRENDING NOW

He built the Vingroup empire. Now South-east Asia’s richest man is handing some key roles to his sons
Developers rush to build homes on Vietnam’s breathtaking coast, testing a new urban model

US dollar falters after Iran’s offer to reopen Hormuz sends oil lower

Tokyo reverses baby bust with AI matchmaking and generous subsidies

