

Regionalisation of supply chain networks benefits Asean and India
Supply chain migration to Asean economies gathers momentum on the back of strong foreign direct investment
THE Covid-19 pandemic revealed the risks of a globalised supply-chain system focused on low costs that depends heavily on Asian (especially Chinese) manufacturers.
China’s stringent pandemic controls added to the tremendous supply-chain pressure and uncertainties caused by Covid-19.
On the geopolitical front, heightened tensions between the US and China have also increased the incentives for companies to reduce their dependence on China and to distribute production across multiple suppliers and regions.
Consequently, the trend towards supply-chain regionalisation – a process that involves reorganising manufacturing into smaller, more localised blocks – has likely accelerated. The shift to a more regionalised sourcing model has been underway for some time, particularly in the Asean economies, whose trade exposures to China climbed steadily from 10 per cent in 2012 to 16 per cent in 2022.
Supply-chain migration to the Asean economies continues to gather momentum on the back of strong flows of foreign direct investment (FDI) into the region. In the decade 2011-2021, the six major Asean countries’ exports grew 41 per cent, much higher than global export growth of 22 per cent. While the region has as a whole improved its manufacturing capabilities, certain countries and industries have grown disproportionately.
Vietnam
We believe Vietnam could be one of the top beneficiaries of the relocation trend. Vietnamese exports have grown a remarkable 219 per cent in the past 10 years, led by labour-intensive industries (including textile, garments and footwear) as well as the machinery and electronics sectors. Heavy government investment in infrastructure to stay competitive has contributed to the strong growth in fixed-asset investment in the past decade.
Indonesia
Indonesia – Asean’s largest economy and the world’s fourth-largest country by population (282 million) – has been stepping up its strategy to extract economic benefits from its rich natural resources as the global energy transition gathers pace. In 2014, the Indonesian government banned exports of nickel ore in order to encourage domestic production of processed metals. It plans to follow the same strategy for copper and other raw materials such as bauxite, cobalt and tin. With these industrial policies in place, Indonesia may be able to unleash its potential and greatly increase its industrial footprint, particularly in the commodity and refining industries.
Thailand
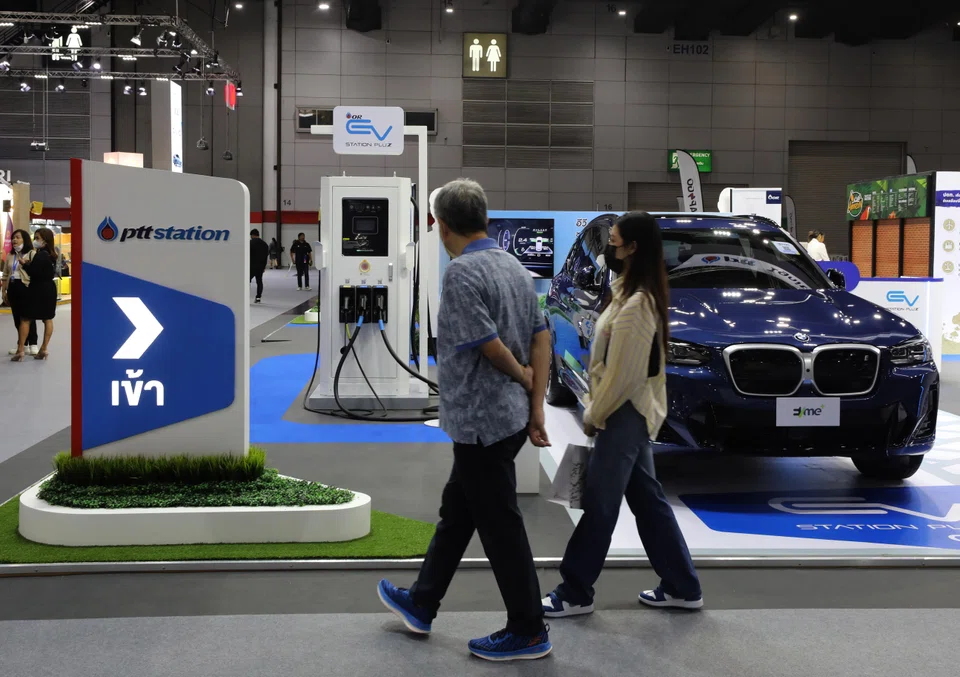
Thailand has successfully developed into South-east Asia’s leading producer of motor vehicles, with production expanding by 18 per cent in 2021 alone. The country could also become a major producer of electric vehicles. Under the country’s 30:30 electrification policy, Thailand wants at least 30 per cent of all new vehicles produced in the country to be zero-emission vehicles by 2030. In addition, the government aims to have 12,000 charging points available by 2030, up from about 1,000 in early 2022. Government incentives will likely encourage global auto manufacturers to further expand their production base in the country.
Malaysia
Malaysia has established a strong footprint in the electrical and electronics (E&E) industry, which has been contributing significantly to the country’s industrial growth, investments and employment. In 2021, foreign investment in E&E was worth RM146.3 billion (S$42.6 billion), representing around 70 per cent of total annual FDI. In 2022, E&E products represented 38.3 per cent of Malaysia’s total exports, up from 32.9 per cent in 2012.
India
The need for many multinational companies to diversify supply chains away from China could also benefit India. However, efforts to transform India into a major manufacturing hub are at an early stage given numerous hurdles, including underdeveloped infrastructure and regulations unfriendly to foreign investors.
In an effort to boost the manufacturing sector and reduce imports, the government introduced the Production-Linked Incentive Scheme in 2020 to incentivise companies to sell products made in India. Simultaneously, the Indian government has been trying to catch up in infrastructure by significantly increasing its related capital spending in recent years. In the country’s federal budget for the current fiscal year (2023-24), capital spending will increase by 37 per cent from last year and will be three times higher than in 2019.
In addition, India has demographic advantages. It has a vast domestic market and an abundant labour force whose median age is about 10 years lower than China’s. India has room for future growth as per-capita income is only about a fifth of China’s. All these factors will likely provide structural tailwinds for its industrial and exports growth and could help it benefit from supply-chain relocation in the coming years.
Outlook for supply-chain relocation
Regionalisation of supply chains will likely continue to gather momentum. To the extent that their focus shifts from cost optimisation to building supply-chain resilience, companies may see an increasing need to relocate their production facilities. This may imply sustained inflows of FDI and increased corporate capital spending in the destination countries. In our view, FDI inflows into Asia will continue to be stronger than for Europe and the Americas, as they have been in the past decade.
Emerging industrial hubs, including Asean and India, may gain in market share in global exports – particularly in labour-intensive sectors as corporates seek to diversify production capacities under “China Plus One” strategies.
Still, China will likely remain a global manufacturing powerhouse while moving up the industrial value chain. Economic bonds between Asian countries will likely be strengthened by the signing of the Regional Comprehensive Economic Partnership in 2022, which could also lead to stronger complimentary trade relationships between China and Asean economies in the years ahead.
Investment opportunities
As the long-term trend of supply-chain regionalisation continues to unfold, Asean is a major beneficiary and India a strategic opportunity. The region’s favourable demographics with a relatively young and growing working population provide a structural tailwind for international supply-chain potential and bode well for long-term growth, especially in digital/financial adoption and decarbonisation efforts.
Quality and sustainability of earnings in Asean are also seeing improvements on the back of better and more prudent macro policies, resumption of economic activity and supportive earnings growth.
Among our Asian equity coverage, we see two broad ways to play the theme. Industrial real estate and logistics service providers that own modern warehouses across Asia or industrial parks developments will benefit from rising industrial activities and consumer demand. Banks with direct exposure to broad economic growth in the region could benefit from higher corporate loan demand and other advisory services. Singapore banks could serve as a gateway for investment flows in the region, while Indonesian and Indian banks offer good structural growth opportunity (low loan-to-GDP penetration).
There are also factors to consider when trying to play this theme. This is a long-term theme, which may play out in the coming decade, not just in the coming months. Investors need to be thoughtful and assess factors such as market access, valuation and local knowledge.
Active management is even more important in emerging markets than in developed ones because of market inefficiency and more policy uncertainties. It is important to select the best managers who specialise in the relevant markets.
The writer is Asia chief investment officer and head of discretionary portfolio management, Pictet Wealth Management
TRENDING NOW

Grab CEO’s wife Chloe Tong on life with Anthony Tan and finding her purpose

What role can Japan play in Asean’s future?

He built the Vingroup empire. Now South-east Asia’s richest man is handing some key roles to his sons

Asean’s challenge is to become resilient against global geopolitics: former Indonesia trade minister

