

Rich valuations leave little room for disappointment in Indian equities
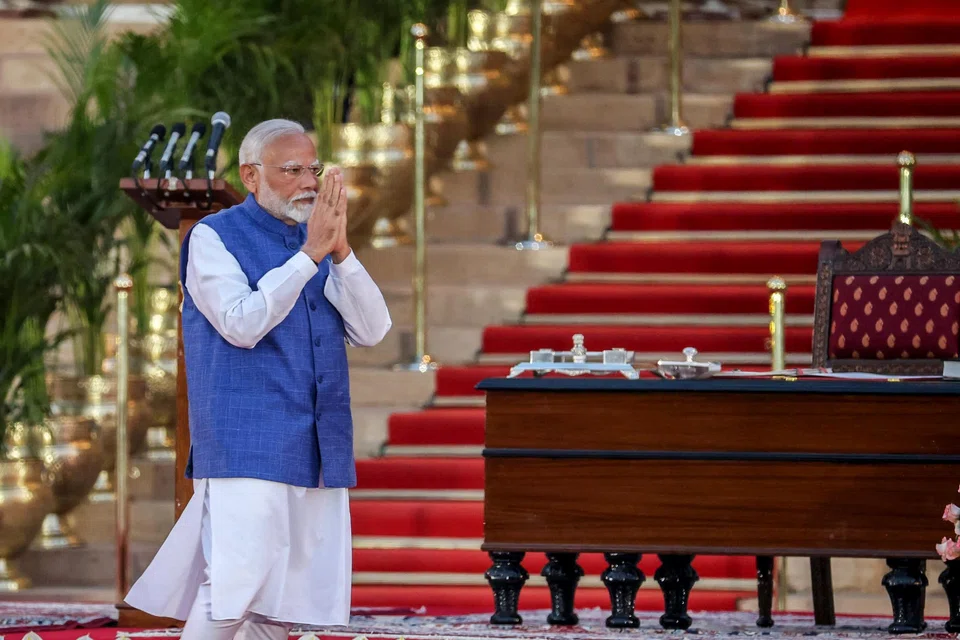
ON JUN 9, Narendra Modi was sworn in as India’s prime minister for a third term. This followed surprising election results; Modi’s ruling party secured a narrower-than-expected victory, despite exit polls predicting a landslide win.
The outcome is seen as a setback for the leader who has driven significant reforms and delivered high economic growth in the country.
India’s equity market responded to the results with volatility. The Sensex Index, comprising 30 large and most actively traded corporations on the Bombay Stock Exchange, tumbled 6 per cent on Jun 4, the day of the election results. It marked the worst trading session in four years.
However, the index rebounded in the days that followed, overcoming wild swings to reclaim new highs and post its strongest week of 2024. Similarly, the MSCI India Index – a key gauge of large and mid-cap segments of the Indian market – has quickly recouped its losses from the Jun 4 session.
Coalition challenges
With a weaker-than-expected mandate, Modi must now rely on allies to form a government for the first time since coming to power a decade ago. Coalition governments are not new to India, but this could delay reforms and decision making, which are seen as crucial to drive the country’s long-term economic growth.
Notably, a single-party government led by Modi has produced significant reforms over the past decade, such as demonetisation and the implementation of the goods and services tax. He also launched the “Make In India” campaign to facilitate companies to develop, manufacture and assemble products made in India – an initiative that has garnered greater attention as multinational companies look to shift production away from China. Such political stability and policy continuity have made India a preferred investment destination for global funds.
Additionally, Modi has previously pledged ambitious economic growth targets, including making India a developed country by 2047. Economists estimate that India would need to achieve growth of 8 to 9 per cent per annum for the next 20 years in order to meet this goal. This is a challenging target as the country has never consistently achieved such levels of growth.
There is also debate among investors that Modi may announce populist measures to consolidate political support, likely leading to a sustained high fiscal deficit. India’s fiscal deficit stood at 5.63 per cent for fiscal 2023/24.
Next month’s budget will be the new government’s first test, and all eyes are on whether Modi’s policy direction will continue.
High youth unemployment
Furthermore, unemployment has been a pressing challenge for India. It emerged as a key election campaign issue, with opposition parties criticising the government for failing to deliver enough jobs, especially for young people.
The unemployment rate in India rose to 8.1 per cent in April this year from 7.4 per cent in March, according to the Centre for Monitoring Indian Economy, a private research company. The majority of the country’s unemployed are its youth, with the jobless rate of those aged 20 to 24 standing at a staggering 44.5 per cent in the October-December quarter of 2023. As such, India has one of the highest youth unemployment rates in Asia.
Employers have found a shortage of young people with specific skills. Poor schooling and high drop-out rates mean young people are not adequately equipped to take on the jobs needed to sustain India’s high growth.
We believe this is especially important as India seeks to join the global semiconductor supply chain, covering aspects like chip packaging and design. Following investments by US chipmakers Micron and AMD in the country amid rising geopolitical tensions, India aims to be among the world’s chip powerhouses.
A common factor among top economies excelling in the semiconductor industry – such as South Korea, Singapore, the US, Taiwan and Japan – is an exceptional education system as well as a highly skilled and productive workforce. While India boasts a large labour pool, it still has a long way to go to equip its people with niche skills needed to compete on the global stage.
Valuations leave little room for disappointment
Following the surprise election results, we expect to see increased volatility in Indian equities in the near term, as some investors re-evaluate their India positioning while others are in a wait-and-see mode. Moving forward, the focus will be on India’s priorities and whether the country’s structural challenges like high youth unemployment will be addressed.
We believe that the upside potential of Indian equities is currently constrained by elevated valuations. Indian stocks are trading at a premium of over 80 per cent to emerging market peers, based on forward PE ratios for the MSCI India Index and MSCI Emerging Markets Index. Such rich valuations raise the risk of a market correction if future economic and earnings growth fail to meet expectations.
Additionally, for foreign investors, a depreciating rupee can erode returns on Indian stocks when converted back to their home currency. In the last decade, the Indian rupee has depreciated by an average rate of 4 per cent annually against the US dollar. To put this into perspective, a 225 per cent gain in the MSCI India Index over the last decade in rupee currency terms translated into a substantially lower 130 per cent gain in US dollar terms.
But not all is doom and gloom in India. The country is increasingly viewed as a prime destination for companies seeking to diversify their supply chains away from China, while the rising middle class holds promise.
Also, coalition governments typically serve as a built-in system of checks and balances. The key challenge is to live up to expectations and justify the premium that investors are currently paying.
The writer is an assistant manager with the research and portfolio management team at FSMOne.com, the B2C division of iFast Financial, a subsidiary of iFast Corporation






