

Scenario planning helps Income Insurance add resilience to life fund
Income Insurance’s life fund tends to outperform when the market environment is poor. Returns in 2023 are expected to be stronger than 2022
Genevieve Cua
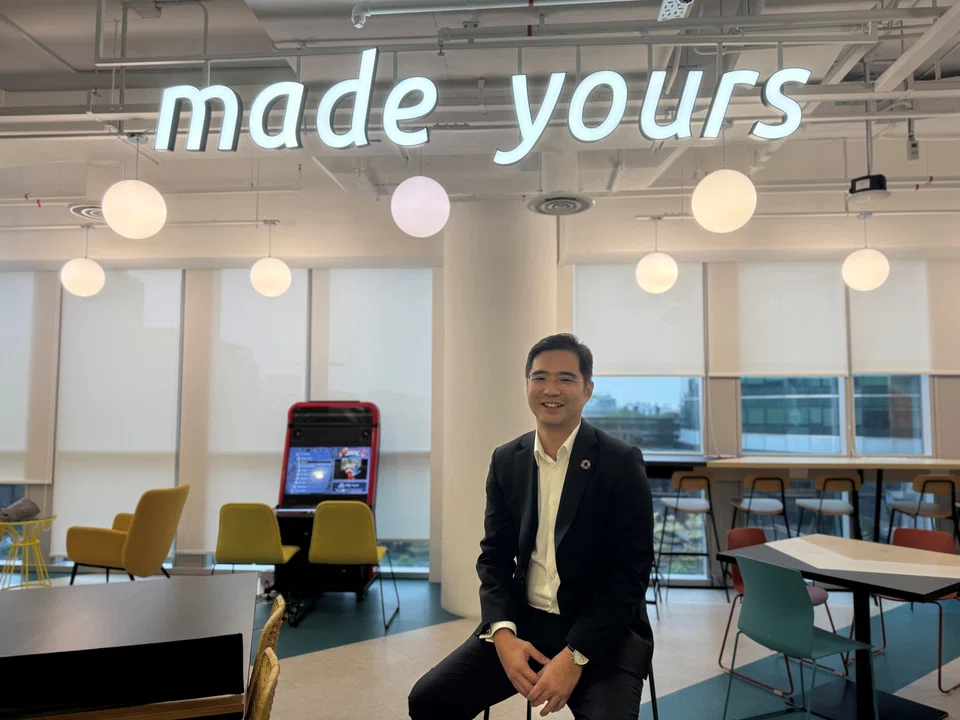
SCENARIO-BASED planning has become a key part of portfolio risk management for Income Insurance, under the watchful eye of chief investment officer David Chua.
Income Insurance manages roughly S$40 billion in assets, comprising participating (par), non-par and investment-linked funds. Par funds are managed with a view to meeting long-term liabilities, which include death and maturity benefits, and annual bonuses.
Chua said: “We want to be able to meet policyholder expectations with regards to returns at the time they bought the policy. In the past 15 years, expectations of returns have come down gradually as interest rates dropped.
“We constantly review our long-term market assumptions in the light of the rising rate environment. Our expectation of returns over the next 15 to 20 years will catch up with what we’re seeing in the market. We also examine how to best optimise the return and risk versus the capital. I’ve started to incorporate more scenario-based planning.”
Climate transition risks and opportunities are factors that he is examining closely. He hints that the group is considering climate-themed investments.
“I would split climate risk into physical and transition risks. We think about incorporating climate transition into our return assumptions: what’s the potential impact on returns? (The) energy transition will add to the cost of business, including carbon tax, which was not incorporated into business plans.”
Chua added: “We’re in the process of setting interim targets or milestones to measure ourselves. At the same time, we’ll look into investing directly in companies in the energy transition space. We’re also engaging with fund managers whom we deem as more strategic partners. Are there impact investments where we can put capital to work and generate returns?”
Income Insurance has committed to net-zero emissions by 2050. It aims to have zero coal-related exposure in its portfolio.
Systematically important
Last year, Income Insurance was one of four insurers designated by the Monetary Authority of Singapore as “systematically important” to the Republic. This subjects them to higher regulatory standards and closer supervision, as well as higher capital requirements to buffer losses. The other three are AIA, Prudential Assurance and Great Eastern Life Assurance.
Chua has had a two-decade career in finance. Prior to joining Income Insurance in 2023, he was head of investment strategy with Prudential Singapore, and was chief of staff to the Prudential group chief executive.
For insurance companies, interest rates wield an impact on returns and liabilities. Most insurers invest largely in fixed-income assets in which interest rate trends affect mark-to-market values and yields. A risk-free rate is also used to discount the values of long-term liabilities to the present. Falling rates magnify the value of liabilities and vice versa.
As much as possible, insurers seek to match assets to liabilities, but this is a challenge if yields are low. In Singapore, there is also a dearth of attractive long-dated bonds.
“Our life par fund has been relatively resilient and tends to outperform when the market environment is poor. In fact, we are likely going through a regime shift where the fundamentals of inflation and growth trajectory could differ from how we experienced them (previously),” Chua said.
“This is where working out the possible scenario outcomes is useful and necessary from a total portfolio perspective. We act by making portfolio adjustments or putting on hedges to mitigate the tail risks.”
Interest rates dropped to nearly zero after the 2008 global financial crisis, and low bond-yields were challenging for insurers. But global central banks have raised interest rates since 2022 following a surge in inflation. Yields on high-quality bonds are also more attractive now, which is a plus for insurers.
Chua said modelling different scenario outcomes serves as a framework to guide return assumptions, asset allocation, risk management and fund manager selection.
Aiming for resilient returns
Income Insurance’s life fund is managed by more than 10 external fund managers, including Fullerton Fund Management, Pimco and JP Morgan Asset Management. As at 2022, the life fund was 55 per cent invested in fixed income, 33 per cent in equities, and 4 per cent in property.
“We focus on identifying managers with characteristics that can deliver sustainable outperformance; we tend to look for managers that possess differentiated investment processes or styles which complement our existing manager line-up,” he said.
The year 2022 was a poor one for all insurers as fixed income and equity returns fell by double digits. Income Insurance generated returns of minus 8.73 per cent; this was relatively better than most other insurers. However, 2023 is expected to have been a stronger year. Chua said Income Insurance has been able to lock in higher yields and also extend the duration of its bond portfolio.
“Given the disinflationary trend over the past 15 years, most multi-asset portfolios are less equipped to handle higher inflation and slower growth environments. We evaluate and look for asset classes that do well in such an environment, and see how they can better diversify the overall portfolio risks, thereby lowering return volatility,” he said.
“We want to have the most consistent approach towards delivering returns. We’re not trying to exceed in terms of performance; especially in down markets, it’s more about preservation of capital.”
Inflation has prompted closer examination of underlying portfolio holdings, such as whether companies are able to pass on higher costs to consumers. Some instruments, he said, help to hedge inflation such as commodities, real estate, infrastructure and floating-rate instruments.
Income Insurance engages with and reviews the performance of third-party managers in its portfolio. Chua said: “We take appropriate action including, but not limited to, reviewing the mandate guidelines and/or replacing the underperforming manager where changes to the manager’s team or process have been assessed to impede its ability to deliver on return objectives. Our focus is to secure long-term sustainable performance for our policyholders in the face of a changing market regime.”
He added: “There is a lot of talk about factors, like growth versus value. But we don’t try to time the factors, which is a difficult task. We aim for not just manager diversification but also factor diversification. As a philosophy, we like quality companies, which helps us to manage volatility.”
TRENDING NOW

MAS allocates S$1.45 billion to five asset managers in third EQDP batch: Chee Hong Tat

‘My grandfather’s legacy’: Sherman Kwek lays out three-year plan for CDL to drive returns

He built the Vingroup empire. Now South-east Asia’s richest man is handing some key roles to his sons

‘How many will survive?’: Bubble fears arise as China’s humanoid robotics face reality check

