

Allocate to optimism – Positioning for growth and innovation in 2025
The US stands at the threshold of an innovation-led economic expansion. AI-driven productivity gains, accommodative monetary policy and forward-looking deregulation set the stage for meaningful economic growth in the year
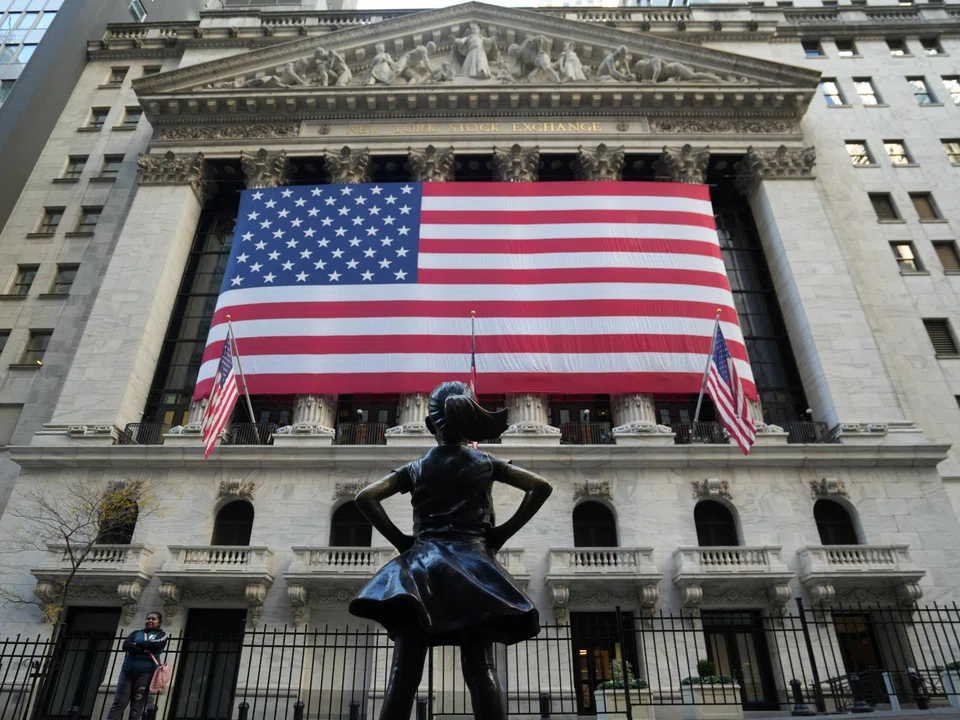
AS WE enter 2025, we believe US equity markets are poised for continued growth, supported by three factors:
- The US economy appears to be entering a new, innovation-led business cycle fuelled by the rapid application of artificial intelligence (AI) across multiple sectors, healthcare innovation, energy infrastructure investment, and reindustrialisation as manufacturers move onshore to avoid tariffs.
- We anticipate a supportive interest rate environment as the Federal Reserve maintains a neutral-to-dovish stance, especially if inflation remains subdued and real gross domestic product growth is supportive.
- The incoming Trump administration’s deregulatory efforts, combined with Silicon Valley’s rising political influence, particularly in support of “little tech”, are likely to foster a more dynamic business landscape. We see significant opportunities with a lighter regulatory touch for the financial services, crypto, technology, industrial and energy industries.
While risks exist, we view them as manageable. To some, valuations may appear elevated, but we believe earnings estimates may be too low, given the potential acceleration in growth and innovation in coming quarters. In aggregate, our outlook is positive, and we encourage investors to allocate to optimism in 2025.
Dawn of a new business cycle
We believe the US is on the cusp of an AI-driven productivity boom that could profoundly impact all sectors of the economy, and that many investors continue to underestimate the scale of this opportunity.
Even modest gains in productivity, spread across the world’s billion knowledge workers, would represent a massive shift in economic output and profitability. Additional value could be unlocked by new science and discovery opportunities beginning to emanate from AI reasoning models.
While early, key industries, including technology, healthcare, consumer staples, financial services and energy, are already beginning to see tangible benefits from AI experimentation and adoption. We believe the US is uniquely positioned to lead this transformation for three reasons:
- The US is home to the world’s leading AI suppliers;
- The nation’s cultural and business environment fosters technological experimentation and implementation;
- The Trump administration should reduce regulatory obstacles to AI development and deployment, extending our head start over global competitors.
In addition, we see promise in continued healthcare innovation, advanced energy production and a “reindustrialisation” of the US economy. Easing regulatory constraints, especially those affecting the financial services industry, could spur significant growth in the crypto opportunity.
Donald Trump’s administration aims to achieve what it calls “energy dominance” on a global scale. Energy infrastructure development holds significant strategic importance, aligning closely with the interests of Trump’s tech and industrial-focused supporters.
We expect the administration to prioritise expanding electricity and energy capacity across oil, coal, natural gas, nuclear and interstate transmission, as well as to update and expand electric generating capacity, enhance grid reliability and encourage energy storage technologies, such as batteries.
This infrastructure focus supports national priorities, including economic growth and job creation, enhanced energy security and reduced dependence on foreign energy. It could bolster US competitiveness in emerging technologies, particularly AI, while simultaneously addressing rising electricity costs and grid stability issues.
A neutral-to-dovish Fed
The Fed is expected to maintain a growth-supportive stance through 2025. Market expectations suggest interest rates may settle into a 3.75 to 4 per cent range by mid-year, which should help sustain equity valuations.
The Fed’s careful calibration (supporting growth while balancing inflation risks) should underpin stable financial conditions in 2025, providing a favourable backdrop for equities. While investors should remain vigilant, especially given that any Fed action can sway markets, the current trajectory suggests moderate rates and a measured approach to policy changes.
This environment should support innovation-led growth and enhance investor confidence across sectors.
Deregulation and the influence of innovators, disruptors and operators
A major catalyst for growth and optimism in 2025 is the incoming administration’s push towards deregulation and government efficiency. Drawing inspiration from Reagan-era efforts, current policy direction aims to reduce bureaucratic red tape, rationalise government spending and streamline federal agencies.
The result should be a business-friendly environment that stimulates competition, lowers compliance costs and encourages innovation in finance, transportation, energy and technology.
This movement is reinforced by a new generation of influential policymakers: Silicon Valley entrepreneurs, disruptors and other business leaders. While many of these new players are public policy neophytes, their focus on growth, rapid decision-making, and technological advancement echoes past deregulatory cycles that unleashed periods of robust economic performance.
Key objectives include dismantling outdated dealmaking regulations, accelerating capital formation and ensuring “little tech” companies can thrive under transparent and minimal regulatory oversight.
The emphasis on national security, energy independence and productivity aligns with a broader vision to maintain US global leadership in innovation. Investments in areas like space exploration, AI-driven manufacturing, robotics and logistics automation all stand to benefit.
Trump’s pro-innovation policies do carry tension and contradictions. They could come with substantial fiscal costs, which could spur inflation and interest rate challenges. They could also result in significant changes to current policies, such as the Chips Act and the Inflation Reduction Act.
In addition, innovators such as Elon Musk simultaneously advocate for rapid technological advancement, while also voicing concern over the dangers of unchecked AI development. Investors should note this inherent unpredictability, as shifts in regulation or sentiment could alter investment dynamics.
Key risks
Despite our optimism, several risks warrant close attention.
On the geopolitical front, tariff policies could disrupt supply chains and push inflation higher, potentially pressuring interest rates and equity valuations. Federal tax cuts must translate into real economic growth, or heightened fiscal deficits may undermine credit and equity markets.
Narrow majorities in Congress and pushback from left-leaning US states and others could slow or dilute reforms, reducing the scope of deregulation and fiscal restructuring. While Trump has promised resolution, the Russia/Ukraine conflict remains highly volatile, with tensions moving higher in recent weeks.
In addition, economic pressures on China are high, and could be exacerbated by additional US tariffs and technology restrictions.
While there are numerous AI-application green shoots across software development, IT and customer support, marketing, document summarisation and media creation, broad AI adoption will take time. For the past two years, we have been solidly in the “build and experimentation” phase of AI, which has benefited chip suppliers, cloud computing vendors and other infrastructure providers.
AI governance, predictability and explainability remain open challenges in this emerging era of probabilistic computing. We see some challenges to continued training scaling, although we believe these will be offset by inference time scaling and other algorithmic improvements.
While we are optimistic about sustained growth and innovation in the healthcare sector, particularly regarding demographics, the adoption of GLP-1s (glucagon-like peptide 1), ongoing biotechnology and genomic advancements, and the application of AI, there is considerable policy uncertainty associated with Trump’s healthcare appointments. We anticipate public health agencies will experience substantial changes in leadership and policy focus.
Valuations do not screen cheap. As of late December, the market-cap weighted S&P 500 appeared expensive at +25x forward earnings, but this metric was dominated by the largest companies in the index.
Many of these businesses have offered resiliency, quality and earnings growth through their leadership in structural opportunities such as AI. But while we continue to favour many of these companies (and believe that their earnings potential may be undervalued as AI adoption accelerates and the business cycle builds momentum), we also see relative value down the market-cap spectrum.
To this point, the equal-weighted S&P 500 trades at a relatively more attractive +21x earnings. During the first half of 2024, 100 per cent of the S&P 500’s positive returns came from less than 45 companies. During the second half of the year, that number was nearly 100. Markets appear to be broadening out.
Conclusion
As we enter 2025, the US stands at the threshold of an innovation-led expansion. The interplay of AI-driven productivity gains, accommodative monetary policy and forward-looking deregulation sets the stage for meaningful economic growth.
Though uncertainties persist, the opportunities – especially among smaller, emerging companies and sectors poised to benefit from a lighter regulatory touch – are compelling.
By maintaining a positive investment outlook and focusing on innovators leading the charge, investors can position themselves to capitalise on a year that promises significant advances in technology, productivity and long-term prosperity.
The writer is chief investment officer of Franklin Equity Group
TRENDING NOW

Two Singapore-listed palm oil firms named in Greenpeace report on Indonesian plantation fires

Singapore Airlines flight returns to San Francisco after ‘unruly’ passenger incident

Singapore looking into which companies responsible for haze-causing fires: PM Wong
Deluge IPO 3.86 times subscribed ahead of SGX debut

