Asia investors shift from money market funds to active funds, alternatives: Wellington Management head of Apac
Fixed income and 140/40 extension strategies have also drawn interest in the past 12 months, says Janet Perumal
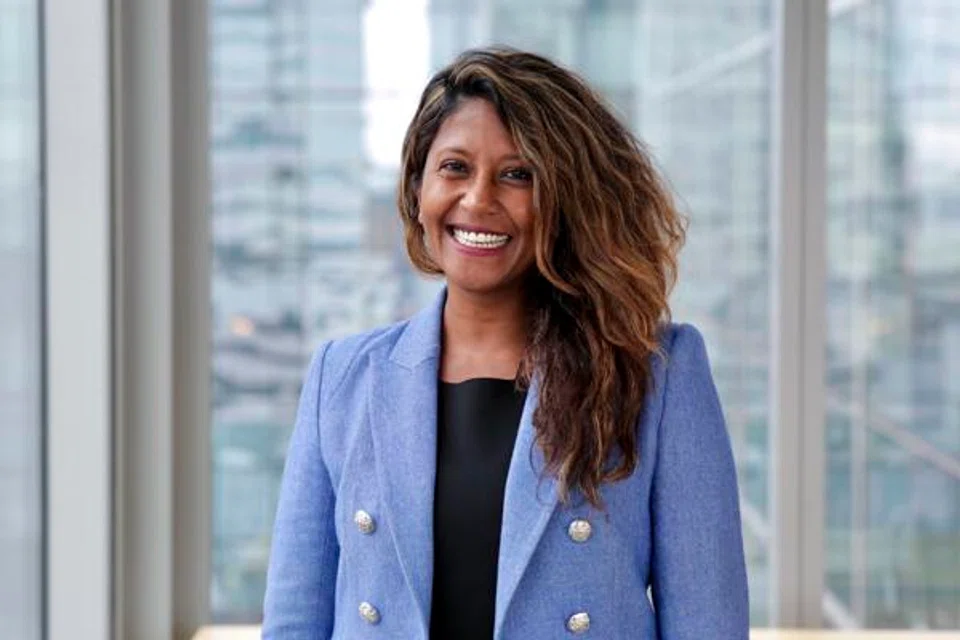
[HONG KONG] Asia’s investors are starting to move assets out of the sidelines from money market funds to areas of opportunity such as actively managed funds, fixed income and alternatives, said Janet Perumal, head of Asia-Pacific and head of investments for Apac at Wellington Management, to The Business Times in an exclusive interview.
It has been a “stellar year” for the asset manager’s Singapore business as there have been more inflows. Also, “money was on the sidelines in money market funds, and (investors) are starting to deploy out of money market funds”, she added.
This applies to investors in the wider Asia region, not just in Singapore, she noted, as people move into areas of opportunity as markets face increased uncertainty and volatility.
Passive investing has become a “pretty big risk” as index-tracked funds become concentrated in a handful of big names dominating the indices, she said.
The Magnificent Seven (Apple, Microsoft, Alphabet, Amazon, Nvidia, Meta and Tesla) account for more than 30 per cent of the S&P 500 index’s total market capitalisation.
She admitted that while valuations are high “or top-ish” at the moment in certain segments of the market, earnings are coming through, which justify these valuations.
“We’ve had accommodative fiscal and monetary policy as well,” she added.
“There is always going to be a place for passive management, but you also need to think about diversifying and think about all of the levers that are available to you from an investment perspective.”
Since September, net flows to active funds in Singapore and Hong Kong have outpaced flows to passively managed funds each month, except November, according to Morningstar Direct data. Over the past six months, passive funds saw three months of outflows: in September, October and December.
Active management also goes in cycles, pointed out Perumal.
In geographies such as Japan and Europe, there are opportunities in active “because of the level of dispersion”.
“There’s change happening, and it’s at those points of change that you want to have experienced investors navigating for you – where there’s uncertainty, there’s opportunity (to take) advantage of.”
On artificial intelligence (AI), she does not believe that we are in a bubble yet, but “there are things to definitely watch for if any of those cracks come through”, she said.
Those “cracks” will start to show in the form of low returns on the AI capex if expectations are not being met and, on the fiscal side, continued debt growth and inflation, she added.
Sensing opportunities
Wellington has observed interest in US small-cap and European equities among institutional investors in Singapore, she said.
In addition, over the last year, there has been interest in 140/40 extension strategies, which typically involve shorting stocks equal to 40 per cent of the fund’s net asset value and reinvesting the proceeds along with the original 100 per cent of capital in a long position.
The firm’s global 140/40 extension strategy platform has grown from US$3.4 billion to US$19.1 billion in the last three years, with US$4.6 billion in net flows in 2025 alone, shared the Apac head.
In Singapore, the platform grew from about US$13 million to more than US$1 billion in the past 12 months, driven mainly by institutional clients, she added.
This rapid pace of asset growth coincided with strong performance – absolute and relative to peers – of the strategy, along with growing client awareness of the benefits of an extension approach in a concentrated market environment, she noted.
There has also been such a “huge demand” for income among wealth clients in Asia that Wellington has been launching Asian credit income and Asia quality income products, which produce strong income as well as total returns, said Perumal, who is also head of office for Singapore.
In December, the firm expanded its partnership with Standard Chartered Bank to make the Wellington Asia Quality Income Fund available to the bank’s clients through new Class B shares – without upfront sales charges.
Growing its private-investment side
Wellington Management is headquartered in Boston in the US and managed US$1.3 trillion in assets globally as at Dec 31. The asset management firm has had a presence in Singapore for more than 25 years.
It has also been growing its private-investment capabilities as clients seek fresh avenues for deployment.
While private investing has been part of the firm’s business for more than a decade, it was focused primarily on late-stage growth in areas such as the biomedical sector.
In recent years, however, the asset manager has branched out into private debt, such as growth lending and commercial real estate debt.
In March 2025, the firm hired a team of four in the US led by Ravi Anand, head of private real estate credit, from US$2.23 trillion investment management firm Pimco.
“This was really an exciting opportunity for us, because they have experience working together, and they (could) really hit the ground running,” said Laura Kirk, New York-based head of private investments capital formation, in a separate interview.
“We think it is a compelling time to be allocating to the commercial real estate debt, and are seeing interest among our clients who are interested in the team’s differentiated approach to origination, underwriting and what we are building.”
Additionally, the firm anticipates the continued growth of mergers and acquisitions (M&A).
Activity around initial public offerings has been quite limited in recent years. Investors have seen more exit opportunities in the form of strategic acquisitions, which is likely to continue in 2026, noted Zhang Xiaying, the firm’s Singapore-based director of private investments for Apac.
“M&A activity will continue to pick up, especially in key sectors that are of interest to strategics,” she said. “We’ve seen some high-profile positions like (the acquisition of) Wiz by Google, and Scale AI by Meta.”
Zhang added: “Secondary markets have become more mature, and are providing a positive avenue for both exit and price discovery.”
Wellington has been expanding its other private-investment offerings, such as introducing an evergreen vehicle amid growing demand for semi-liquid assets.
In January, the firm hired Alex Behm in the US as head of secondaries, venture growth evergreen and private investments. It had earlier in October also hired Michael Trihy in the US to lead the expansion of the asset manager’s evergreen private-investing capabilities for the private-wealth segment.
Last year, the firm announced plans to launch a multi-asset fund solution created with Vanguard and Blackstone, which combines public and private assets across active and index strategies.
“A lot of these strategies might sound a bit uncorrelated to each other, but as we build our private business, one of the key philosophies that we’re looking for is trying to look for adjacencies to the broader Wellington platform,” Zhang said.
“So whoever we bring on board can tap into the overall Wellington resources and expertise and create that ecosystem where our private investors can be actively involved and actively getting insights from the public side (of the firm).”