

Brokers' take
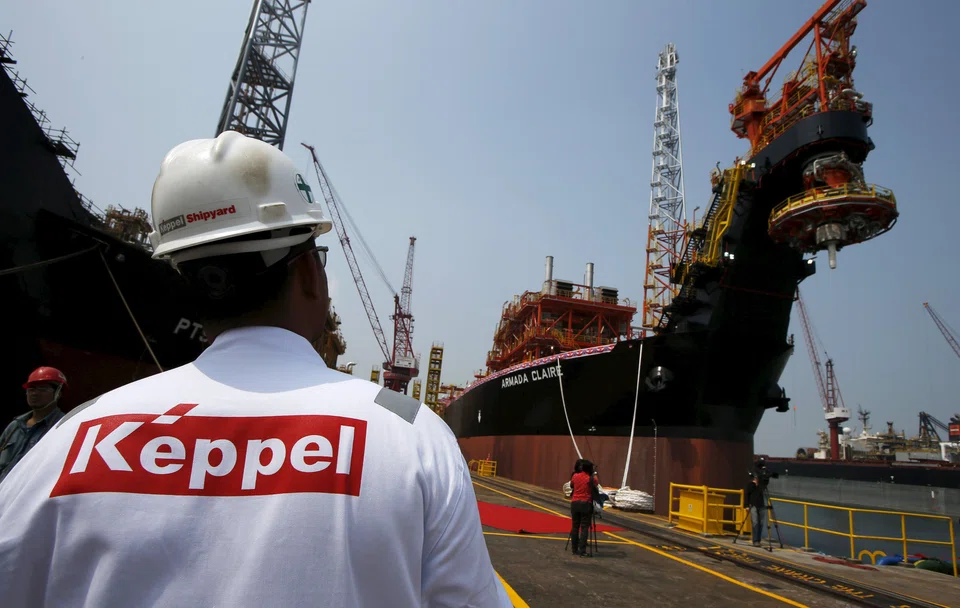
Keppel Corp
Sell
KGI Fraser | Jan 22 |
Target price: S$4.26
Jan 22 close: S$5.02
KEPPEL'S P/B valuations are trading at 15-year lows (-1.5 SD to 15-year average), which may appear to provide a buying opportunity to accumulate a well-diversified company with a good track record of consistently delivering ROEs of about 15 per cent per annum over the last 10 years. However, we are cautious on Keppel's outlook this year as its O&M may be facing multiple downside risks, thus bringing ROEs below 10 per cent.
First, we expect Keppel to recognise more provision for its Sete Brasil semisubs as Sete Brasil and Brazil remain mired in financial woes, worsened by political deadlock. Second, the offshore rig industry may be in a long-term cyclical downturn as the overcapacity built over the last decade takes at least two to three years to balance out. Third, net gearing has increased to 0.5x from 0.1x in FY14 . . . We expect this to increase as customers defer deliveries, presenting more downside risks to dividends.
Singapore property
Overweight
CIMB | Jan 22 |
PROPERTY developers are trading at a 45 per cent discount to RNAV, their lowest levels post-global financial crisis and below -1 SD discount to mean. We think it is time to relook the sector as much of the extreme pessimism has been priced in.
The strong appetite for investment properties would mean opportunities to recycle capital through asset monetisation activities and benefit developers with a deep portfolio. We retain our "overweight" stance on the sector on attractive sector valuation, after the recent market rout. Our top picks are City Developments, CapitaLand, CapitaLand Mall Trust, Mapletree Greater China Commercial Reit and Keppel DC Reit.
Singapore telcos
No rating
Credit Suisse | Jan 21 |
OTT services establish a direct connection between consumers and content owners, hence reducing the relevance of aggregators such as pay TV operators.
Recently, both Singtel and StarHub have announced partnerships with Netflix. We think these partnerships are unlikely to stem pay TV churn in the medium to long term, as choices for consumers enhance both in terms of amount of content and the medium to access the same.
We reduce our medium to long-term pay TV forecasts for StarHub. As a result, our target price reduces to S$3.05 (from S$3.10 previously). We maintain our "underweight" rating on M1 and StarHub as we believe they have yet to bake in the complete financial impact from the potential entry of a fourth cellular operator. Singtel is our top pick in the sector as Singapore business only contributes about 20 per cent to our SoTP-based target price and within that Singapore mobile only constitutes 5 per cent.
Compiled by Melissa Tan
Disclaimer: All analyses, recommendations and other information herein are published for general information. Readers should not rely solely on the information published and should seek independent financial advice prior to making any investment decision. The publisher accepts no liability for any loss whatsoever arising from any use of the information published herein.
Brokers who wish to send in their reports can email us at btnews@sph.com.sg
TRENDING NOW

One-third of Singapore-listed firms at risk in severe AI downturn: MAS

‘We don’t want to stay as we are’: CEO Patrick Ng builds a more resilient Huationg

He built the Vingroup empire. Now South-east Asia’s richest man is handing some key roles to his sons
Radiant World table shows six lenders with US$870 million exposure

